Auto Loan With Only Disability Income: Approval Guide
Get approved for an auto loan with only disability income by learning which documents replace pay stubs and how lenders calculate DTI with benefit income.
By Megan Brooks
Living on disability benefits does not have to mean giving up on the idea of owning a reliable vehicle. Whether you receive Social Security Disability Insurance (SSDI), Supplemental Security Income (SSI), or long-term private disability payments, that income is real, predictable, and legally countable when a lender evaluates your application. The challenge is that many traditional banks and credit unions are wired to approve borrowers with traditional pay stubs, and they may not have a clear process for verifying fixed benefit income. That gap leaves many disabled borrowers wondering if an auto loan with only disability income is even possible. The short answer is yes, but the path to approval looks different from a standard W-2 application. You will need to understand how lenders verify non-wage income, which documents replace pay stubs, how debt-to-income ratios work when your income comes from benefits, and which types of lenders are most comfortable working with fixed-income borrowers. This guide walks through each of those areas so you can approach your auto loan search with confidence and a clear plan.
How Lenders Verify Disability Income for Auto Loans
When you apply for an auto loan with only disability income, the lender's first concern is verification. They need to confirm that your benefits are ongoing, stable, and sufficient to cover the proposed monthly payment. Unlike a paycheck, which arrives on a predictable schedule and can be confirmed with a phone call to an employer, disability income often requires a paper trail that proves both the amount and the continuity of the payments. Lenders typically want to see that your benefits have been active for a meaningful period, often at least six to twelve months, and that there is no scheduled end date in the near future. For SSDI and SSI, the Social Security Administration provides benefit verification letters that state your monthly amount and your eligibility status. For private disability insurance, you may need a letter from the insurer confirming the payment schedule and the remaining term of coverage.
Some lenders will also ask for bank statements showing the deposits over the last several months. This serves two purposes. It confirms the amount you receive and it demonstrates that the payments arrive consistently. If your benefits are deposited directly into a bank account, those statements become a powerful verification tool. Lenders may also request a copy of your award letter or a recent cost-of-living adjustment notice. The key is to be prepared with a complete documentation package before you apply, because missing paperwork is one of the most common reasons applications stall or get denied.
It is worth noting that not all lenders treat disability income the same way. Some will count it fully toward your qualifying income, while others may apply a discount or require a longer history. Working with a lender or a connection service that understands fixed-income borrowers can save you time and frustration. StartAutoLoan.com, for example, connects borrowers with a network of participating lenders and dealers who are accustomed to working with non-traditional income profiles, including disability benefits. Their application process is designed to streamline the verification step so you are not left guessing which documents to send.
Documentation That Substitutes for Pay Stubs
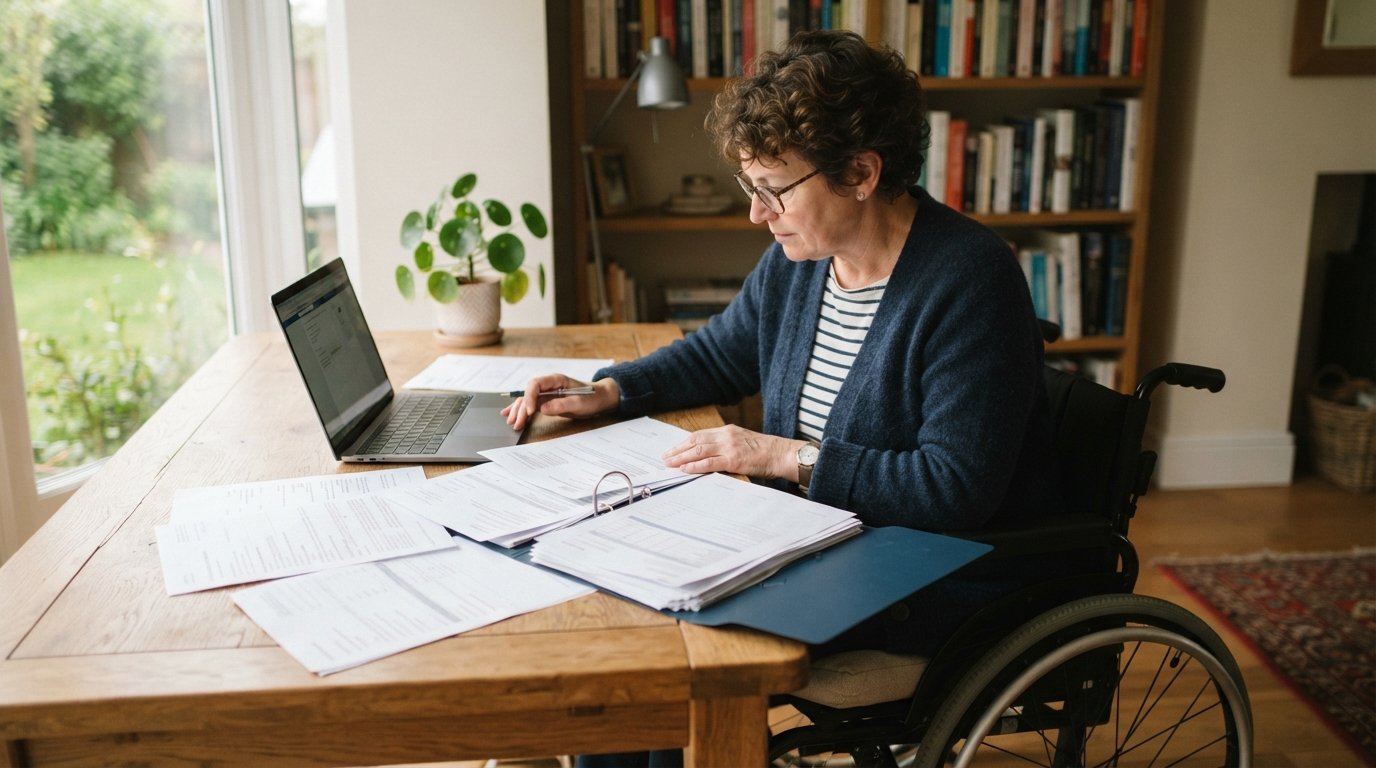
The single biggest hurdle for disabled borrowers is the absence of traditional pay stubs. The good news is that lenders have established alternatives, and most are willing to accept them when they are presented clearly. The exact list varies by lender, but the following documents are commonly accepted as proof of disability income:
- Social Security benefit verification letter: Available from your my Social Security account or by visiting a local office, this letter states your monthly benefit amount and your eligibility status.
- Bank statements: Three to six months of statements showing consistent direct deposits from the Social Security Administration or a private insurer.
- Award letter or decision notice: The original letter you received when your benefits were approved, which confirms the start date and payment amount.
- Form SSA-1099 or 1099-DIV: Tax forms that report the total benefits you received in a given year, useful for showing a longer income history.
- Insurer payment letter: For private disability policies, a letter from the insurance company confirming the payment amount and the remaining duration of coverage.
In addition to income documentation, lenders will still ask for standard items such as a government-issued ID, proof of residence, and insurance information for the vehicle. If you have a co-borrower, their income and documentation will also be part of the package. The goal is to paint a complete picture of your financial situation so the underwriter can see that your disability income is stable and sufficient. Keeping these documents organized in a folder, either physical or digital, will make the application process smoother and faster.
One practical tip: order your benefit verification letter and your bank statements before you start shopping. Some lenders can pull verification electronically, but having your own copies ensures you are not delayed by administrative processing times. If you are working with a dealer or a connection service, ask upfront which documents they require so you can submit everything in one go. For a broader look at how rates and income profiles interact, see our guide on auto loan rates today, which explains how lenders price loans for different borrower profiles.
Debt-to-Income Calculation With Benefit Income
Debt-to-income ratio, or DTI, is one of the most important numbers in any auto loan application. It compares your total monthly debt obligations to your gross monthly income. Lenders use DTI to gauge whether you can comfortably handle a new car payment. When your income comes entirely from disability benefits, the calculation works the same way, but there are a few nuances to understand. First, confirm whether the lender uses gross or net benefit income. Social Security benefits are typically paid net of Medicare premiums, and some lenders will use the gross amount while others use the net deposit. Ask the lender which figure they use so you can estimate your DTI accurately.
Second, be aware that some lenders apply a conservative treatment to fixed income. They may count only a percentage of your disability income, or they may require a lower DTI threshold than they would for a salaried borrower. This is not a penalty; it is a risk management approach. You can offset this by reducing your existing debts before you apply, saving for a larger down payment, or adding a co-borrower with additional income. A lower DTI signals to the lender that you have room in your budget for a car payment, even on a fixed income.
Here is a simple framework to estimate your DTI before you apply:
- Add up your gross monthly disability income from all sources (SSDI, SSI, private policies, and any part-time work).
- Add up your minimum monthly debt payments, including rent or mortgage, credit cards, personal loans, and any other installment loans.
- Divide your total monthly debt by your gross monthly income to get your DTI percentage.
- Compare that percentage to the lender's guideline, which is often 40% to 50% for auto loans, though some lenders are more flexible.
If your DTI is high, focus on paying down revolving balances or increasing your down payment. Both steps reduce the amount you need to finance and improve your chances of approval. Remember that the car payment itself will be added to your debt total, so leave room in your budget for the new obligation.
Lenders and Dealers Comfortable With Fixed-Income Borrowers
Not all lenders are equally equipped to work with disability income. Traditional banks often prefer W-2 employees because the verification is straightforward. Credit unions can be more flexible, especially if you have an established relationship and a history of direct deposit with them. But the lenders most comfortable with fixed-income borrowers tend to be those that specialize in non-traditional credit profiles, including subprime lenders and dealers that work with a variety of financing sources. These lenders see disability income regularly and have established processes for verifying it. They may also be more willing to consider alternative credit data, such as rent payment history or utility payments, when your credit file is thin.
Dealer financing is another strong option. Many dealerships have relationships with multiple lenders and can shop your application to find one that accepts disability income. This is where a connection service like AutoTitleLoan can be helpful. AutoTitleLoan.com is an independent online platform that connects consumers with auto loan financing options, serving as a connection service rather than a direct lender. The site primarily targets individuals who have faced rejection from traditional lenders due to bad credit, no credit history, or past bankruptcies, as well as first-time car buyers. It offers a streamlined loan application tool that can match you with participating lenders and dealers who are more likely to work with fixed-income borrowers. Using a service like this can expand your options beyond the banks that have already turned you down.
When you approach lenders, be upfront about your income source. Hiding it or hoping it will not come up will only slow the process. Instead, present your documentation confidently and explain that your disability income is stable and ongoing. Many lenders appreciate transparency and will work with you to find a loan structure that fits your budget. If you have a co-borrower, consider adding them to the application to strengthen the income profile. And if you are refinancing an existing loan, the same principles apply: show your benefit verification and bank statements, and work with a lender that understands fixed income.
Steps to Improve Your Approval Odds
Beyond documentation and lender selection, there are several practical steps you can take to strengthen your application for an auto loan with only disability income. Start by checking your credit reports for errors. Disputing inaccuracies can raise your score and improve your terms. Save for a down payment, even a modest one, because it reduces the lender's risk and shows commitment. Consider a shorter loan term if the monthly payment fits your budget, as it reduces the total interest you pay. And avoid applying to multiple lenders in a short window, as each application can generate a hard inquiry on your credit report.
It also helps to understand how lenders view disability income in the context of your overall financial picture. If you have savings, a stable housing situation, and a history of on-time payments on other obligations, those factors can offset concerns about fixed income. Some lenders offer preapproval, which gives you a clear budget before you shop and signals to dealers that you are a serious buyer. Preapproval can also reveal which lenders are willing to count your disability income, saving you from wasted applications.
Finally, do not overlook the importance of a realistic budget. Your auto loan payment should fit comfortably within your monthly income after covering essential expenses. Lenders will assess this, but you should too. A vehicle that stretches your budget too thin can lead to missed payments and damage your credit. Choose a loan amount that leaves room for insurance, maintenance, and unexpected costs. With the right preparation and the right lending partner, your disability income can be the foundation for a successful auto loan.
Securing financing on a fixed income is entirely achievable when you know how to present your income, which documents to gather, and where to look for lenders who understand your situation. Take the time to prepare, ask questions, and use the resources available to you. Your next vehicle may be closer than you think.