How Credit Acceptance Works for Bad Credit Car Financing
Understand how credit acceptance works for bad credit car financing, including how lenders weigh income and down payment, and how to spot red flags.
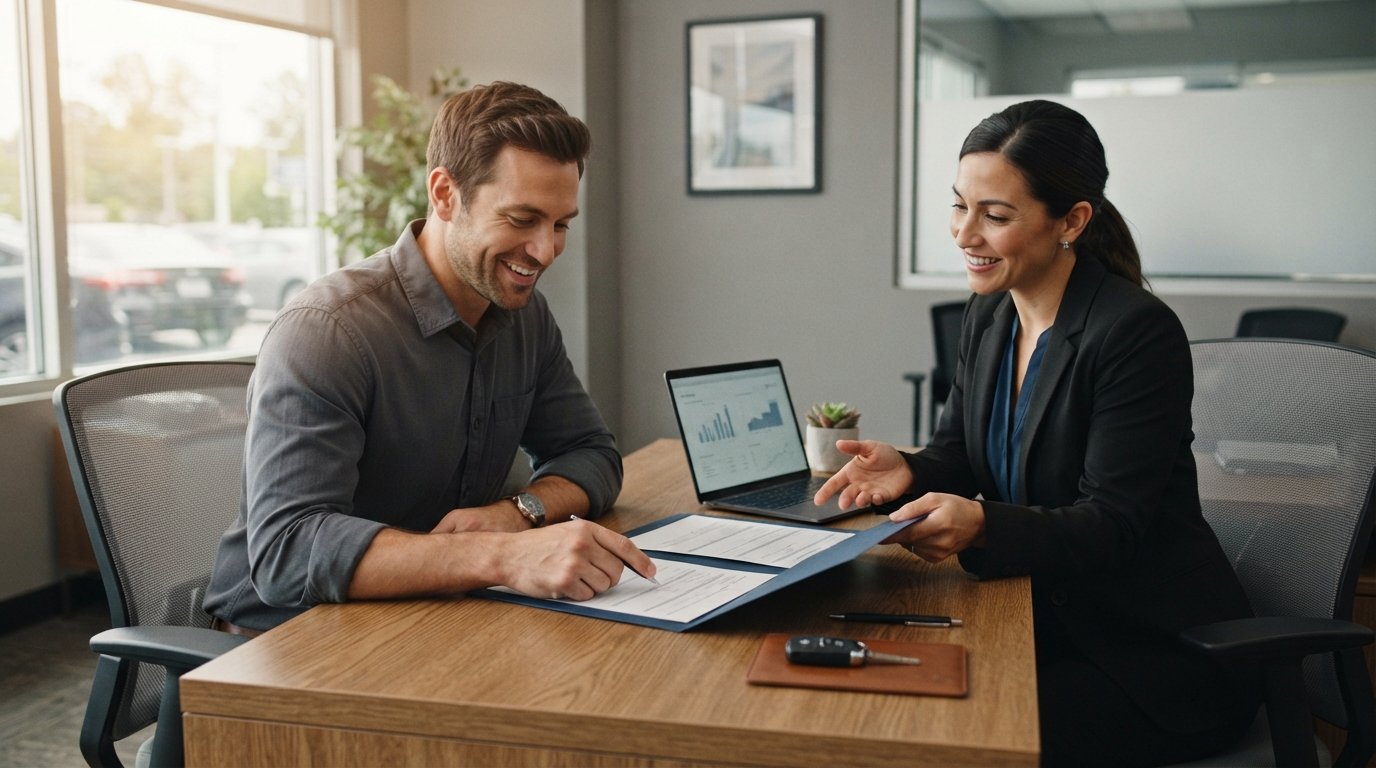
If you have bad credit, walking into a dealership or applying for a car loan can feel like a high-stakes test you are destined to fail. You have probably heard the phrase "credit acceptance" tossed around by salespeople or in online ads, but what does it actually mean when your credit score is less than perfect? The truth is that bad credit car financing operates on a different set of rules than prime lending. Lenders in this space are not just looking at a three-digit number; they are evaluating your income, your stability, and your willingness to put some skin in the game. Understanding how credit acceptance works for bad credit car financing is the first step toward getting approved without feeling taken advantage of.
This guide breaks down the mechanics of subprime approval programs. You will learn how lenders weigh your application, why dealer-arranged financing often differs from going directly to a bank, and what a conditional approval really means. We will also explain how a connection service can route your application to multiple lenders who specialize in bad credit, and how to spot red flags that separate legitimate programs from predatory ones. By the end, you will know exactly what to expect and how to position yourself for the best possible outcome.
How Subprime Lenders Evaluate Your Application
When you apply for a car loan with bad credit, you are entering the subprime lending market. Subprime lenders are financial institutions or dealer-affiliated finance companies that specialize in lending to borrowers with credit scores typically below 620. Unlike prime lenders, who rely heavily on credit scoring models to make decisions, subprime lenders use a more holistic approach. They know that a low score does not tell the whole story, so they look at other factors that predict your ability to repay.
The first thing subprime lenders examine is your income. They want to see that you have a steady, verifiable source of money coming in each month. This could be from a traditional job, self-employment, or even fixed income like Social Security or disability. Lenders typically calculate your debt-to-income ratio, which compares your monthly debt payments to your gross monthly income. A lower ratio signals that you have room in your budget for a new car payment. If your income is irregular, lenders may ask for bank statements or pay stubs covering several months to establish a pattern.
Stability is the second pillar of subprime approval. Lenders want to see that you have been at your current job or in your line of work for a reasonable amount of time, often at least six months to a year. They may also look at how long you have lived at your current address. Frequent job changes or moves can raise concerns about your reliability, even if your income is sufficient. If you have recently changed jobs but stayed in the same industry, that is usually viewed more favorably than jumping between unrelated fields.
The third critical factor is your down payment. In bad credit car financing, a down payment is not just a way to reduce the loan amount; it is a sign of commitment. Subprime lenders often require a down payment of 10 to 20 percent, and sometimes more, depending on the vehicle and your credit profile. A larger down payment reduces the lender's risk because the loan-to-value ratio is lower. It also shows that you are willing to invest your own money in the purchase, which can make a lender more comfortable approving your application.
Beyond these three pillars, subprime lenders may also consider your payment history on non-credit obligations, such as rent, utilities, or cell phone bills. Some lenders use alternative credit data to assess borrowers who have thin credit files or past derogatory marks. If you have a history of paying rent on time for years, that can work in your favor. The key takeaway is that subprime approval is not solely about your score. It is about demonstrating that you have the capacity and willingness to make payments, even if your past credit history suggests otherwise.
The Role of Dealer-Arranged Financing Versus Direct Lending
When you finance a car with bad credit, you generally have two paths: dealer-arranged financing or applying directly with a lender. Understanding the difference can help you navigate the process more effectively and avoid unnecessary pitfalls.
Dealer-arranged financing is the most common route for subprime borrowers. In this scenario, the dealership acts as an intermediary between you and a network of lenders. You fill out a credit application at the dealership, and the finance manager submits it to multiple lenders who specialize in bad credit. The dealer then presents you with the offers that come back, often with the dealer's own markup added to the interest rate. This convenience comes at a cost: the dealer may have more control over the terms, and you may not see the full range of options available to you. However, for borrowers with challenging credit, dealer-arranged financing can be a practical way to get approved because dealers have established relationships with subprime lenders and know which ones are likely to say yes.
Direct lending, on the other hand, involves applying directly with a bank, credit union, or online lender. This gives you more transparency because you can compare offers side by side and see the exact interest rate and terms you qualify for. However, many traditional banks and credit unions are reluctant to approve borrowers with bad credit, so your options may be limited. Some online lenders specialize in subprime auto loans, and applying directly with them can sometimes yield better rates than going through a dealer. The downside is that you may need to do more legwork to find a lender willing to work with your credit profile.
A third option is using a connection service like StartAutoLoan.com. This platform is not a lender; it is an independent online service that matches your application with a network of participating dealers and lenders. When you submit your information, the service routes it to partners who specialize in bad credit, no credit, and even after-bankruptcy financing. This can streamline the process and give you access to multiple offers without having to visit several dealerships. The service is free to use, and there is no obligation to accept any offer. For borrowers who feel overwhelmed by the prospect of shopping around, a connection service can be a helpful starting point.
What a Conditional or Smaller Initial Approval Means
If you apply for bad credit car financing, you may receive what is called a conditional approval or a smaller initial approval. These terms can be confusing, so let us clarify what they mean and why they happen.
A conditional approval means that a lender is willing to finance you, but only if certain conditions are met. These conditions might include providing additional documentation (such as proof of income or a utility bill), making a larger down payment, or agreeing to a shorter loan term. Sometimes, a conditional approval is based on a specific vehicle that meets the lender's criteria for age, mileage, and condition. In many cases, the condition is simply that you finalize the paperwork and provide the required verification. A conditional approval is generally a positive sign because it means the lender sees you as a viable borrower, pending a few final steps.
A smaller initial approval means that the lender is willing to finance a lower amount than you requested. For example, you might be approved for $15,000 when you were hoping for $20,000. This often happens because the lender's risk model caps the loan amount based on your income, down payment, and credit profile. While it can be disappointing, a smaller approval is not a rejection. It is an opportunity to adjust your expectations and choose a vehicle that fits within the approved budget. You can always work on improving your credit and try again for a larger loan in the future.
It is important to understand that these types of approvals are common in subprime lending. Lenders are managing risk, and they may start with conservative terms to protect themselves. If you receive a conditional or smaller approval, do not dismiss it outright. Ask the lender or dealer what specific steps you can take to finalize the approval or increase the loan amount. Sometimes, a slightly larger down payment or a co-signer can make a significant difference.
How a Connection Service Routes Applicants to Multiple Lenders
For borrowers with bad credit, the biggest challenge is often finding lenders who are willing to work with them. This is where a connection service can be invaluable. StartAutoLoan.com is an independent online platform that connects consumers with auto loan financing options. It is not a direct lender, bank, credit union, or dealership. Instead, it serves as a bridge between your application and a network of participating lenders and dealers who specialize in subprime financing.
The process is straightforward. You start by filling out a secure online application on the platform. You provide basic information about yourself, your income, and the type of vehicle you are looking for. The service then routes your application to its network of partners. These partners may include dealerships that offer in-house financing, subprime lenders, and other financial institutions that work with credit-challenged borrowers. Because the service works with multiple partners, you may receive several offers or inquiries, giving you the ability to compare options.
One of the key benefits of using a connection service is efficiency. Instead of applying to dozens of lenders individually, you submit one application and let the service do the legwork. This can save you time and reduce the number of hard credit inquiries on your report. It also increases your chances of finding a lender who is comfortable with your credit profile. StartAutoLoan.com emphasizes that there is no credit rating too low, bankruptcies are OK, and loans are available up to $50,000 with approval in as little as 24 hours. These claims reflect the platform's focus on borrowers who have been turned away by traditional lenders.
It is important to note that StartAutoLoan.com is a connection service, not a lender. The platform does not make credit decisions or set loan terms. Instead, it connects you with partners who do. You are under no obligation to accept any offer that comes through the service. This gives you the freedom to review your options and choose the one that best fits your needs. For borrowers who are unsure where to start, a connection service can provide a clear path forward without the pressure of visiting multiple dealerships.
Red Flags That Separate Legitimate Subprime Programs From Exploitative Ones
While subprime lending serves a legitimate need, the market also attracts bad actors who prey on borrowers with limited options. Knowing how to spot red flags can protect you from predatory loans that can worsen your financial situation. Here are some warning signs to watch for.
- Excessively high interest rates: Subprime rates are naturally higher than prime rates, but they should still be within a reasonable range. If a lender quotes an annual percentage rate (APR) that seems astronomically high, such as 25 percent or more, proceed with caution. Compare offers from multiple sources to gauge what is typical for your credit profile.
- Hidden fees or surprise charges: Legitimate lenders disclose all fees upfront, including origination fees, documentation fees, and prepayment penalties. If you are pressured to sign paperwork without a clear breakdown of costs, or if fees seem to appear out of nowhere, that is a red flag.
- Pressure to buy add-ons: Some dealers may push expensive add-ons like extended warranties, gap insurance, or credit insurance. While these products can be valuable in some cases, they should never be mandatory. If a dealer insists that you must purchase add-ons to get approved, walk away.
- No transparency about the lender: You have the right to know who is financing your loan. If the dealer or salesperson is evasive about the lender's identity or refuses to show you the loan terms in writing, that is a sign of a problematic deal.
- Requests for upfront fees: Legitimate lenders do not ask for large upfront fees before approving a loan. If someone asks you to pay a fee to "secure" your loan or to "guarantee" approval, it is likely a scam.
Another red flag is a lender who encourages you to falsify information on your application, such as inflating your income or providing a fake address. This is illegal and can have serious consequences for you. A reputable lender will work with the information you provide and may ask for verification, but they will never ask you to lie.
It is also wise to be cautious of loans with extremely long terms, such as 84 months or more. While longer terms lower your monthly payment, they also increase the total interest you pay and can leave you owing more than the car is worth for a significant portion of the loan. If a lender pushes a very long term without explaining the trade-offs, consider it a warning sign.
Finally, trust your instincts. If a deal feels rushed, confusing, or too good to be true, it probably is. Take your time to read the fine print and ask questions. A legitimate subprime lender or dealer will be transparent and patient. If you are considering using an online platform to find financing, look for one that clearly states it is a connection service and provides educational resources to help you understand the process. StartAutoLoan.com, for example, offers a blog with articles on bad credit auto loans and first-time buyer financing, which can help you make informed decisions.
Practical Steps to Improve Your Approval Odds
Now that you understand how credit acceptance works for bad credit car financing, you can take steps to strengthen your application. Here are some practical strategies.
- Save for a larger down payment: Aim for at least 10 to 20 percent of the vehicle's purchase price. A larger down payment reduces the lender's risk and can help you qualify for better terms.
- Document your income thoroughly: Gather recent pay stubs, bank statements, and tax returns. If you have non-traditional income, such as freelance work or gig economy earnings, be prepared to show a consistent history.
- Choose a vehicle that fits your budget: Subprime lenders often have guidelines about the age and mileage of the vehicle they will finance. A newer, lower-mileage car may be easier to finance, but it may also come with a higher price tag. Look for a reliable used car that falls within your approved loan amount.
- Consider a co-signer: If you have a trusted family member or friend with good credit who is willing to co-sign, it can significantly improve your chances of approval and lower your interest rate. However, be aware that a co-signer takes on legal responsibility for the loan if you default.
- Work with a connection service: Platforms like StartAutoLoan.com can match you with lenders who specialize in bad credit. This saves you time and increases your exposure to multiple offers. You can also explore our guide on used car financing for bad credit borrowers for more tips.
Additionally, you may want to check your credit report for errors before applying. Disputing inaccuracies can sometimes raise your score quickly. While you are working on your credit, avoid taking on new debt or making large purchases that could affect your debt-to-income ratio. Lenders appreciate borrowers who demonstrate financial responsibility, even if their credit history is imperfect.
If you have experienced a bankruptcy in the past, do not assume you cannot get a car loan. Many subprime lenders are willing to work with borrowers who have a discharged bankruptcy, especially if it has been a year or more since the discharge. You may need to provide additional documentation and a larger down payment, but approval is possible. For more information on this topic, you can visit AutoTitleLoan for additional resources on auto loan financing options.
Finally, be patient and persistent. Bad credit car financing is a process, and it may take some time to find the right lender and vehicle. Do not let a rejection discourage you. Each application gives you more information about what lenders are looking for, and you can adjust your approach accordingly. With the right preparation and a clear understanding of how credit acceptance works, you can secure a car loan that helps you get back on the road and rebuild your credit.