Auto Loan Refinance With Bad Credit: Worth It or Not?
Auto loan refinance with bad credit worth it or not depends on break-even math, term length, and credit improvement. Run the numbers before you apply.
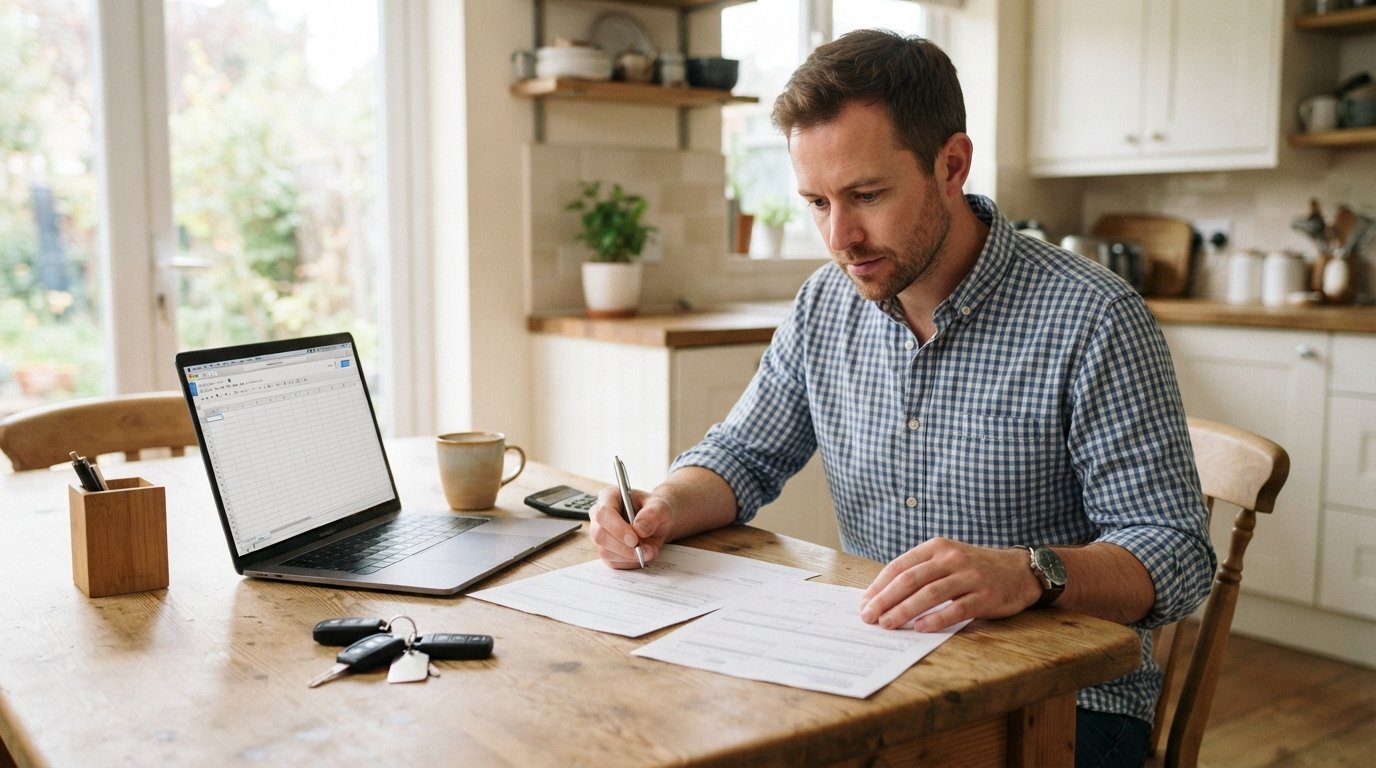
You are staring at a monthly auto loan payment that feels like it belongs to someone with a much bigger budget. Every time you check your credit score, the number stings a little, and you wonder if refinancing is even an option. The question isn't just whether you can refinance with bad credit, it's whether doing so actually makes financial sense. The answer depends on a handful of numbers, a clear-eyed look at your credit trajectory, and a willingness to run some simple math before signing anything. This guide walks you through the decision framework that lenders and financial coaches use, so you can determine if auto loan refinance with bad credit is worth it or not for your specific situation.
Understand What Refinancing Actually Does
Refinancing replaces your current auto loan with a new one. The new lender pays off the old loan, and you make payments to the new lender under new terms. The goal is usually to secure a lower interest rate, a lower monthly payment, or both. But when you have bad credit, the pool of lenders willing to work with you shrinks, and the rates they offer may not be dramatically better than what you already have. That doesn't mean refinancing is automatically a bad idea. It means you need to be more deliberate about when and how you pursue it.
The core mechanics matter here. Your new loan will have its own interest rate, term length, and fees. If the new rate is lower and the term is the same or shorter, you save money. If the new rate is lower but the term is stretched out, your monthly payment drops but you may pay more interest over the life of the loan. If the new rate is higher, refinancing is almost never worth it unless you are trying to remove a cosigner or escape a predatory loan structure. Understanding these trade-offs is the first step in answering the worth it or not question.
One often overlooked factor is the source of your current loan. Dealer-arranged financing sometimes carries a markup that a direct lender or credit union would not apply. If you bought your car at a dealership and accepted the financing offered on the spot, there is a reasonable chance you are paying more than necessary. Refinancing with a different type of lender can sometimes produce savings even if your credit has not improved much, simply because you are no longer paying the dealer's markup.
Run the Break-Even Math Before You Decide
The break-even calculation is the single most important tool in your decision. It tells you how long it will take for your monthly savings to outweigh the costs of refinancing. Start by gathering three numbers: your current monthly payment, your current interest rate, and your remaining loan balance. Then get a realistic estimate of the new rate you could qualify for and any fees the new lender charges. Origination fees, title transfer fees, and application fees all count. Some lenders charge none of these, which makes the math simpler.
Here is the framework in plain steps. First, subtract the new monthly payment from the old monthly payment to find your monthly savings. Second, add up all upfront costs associated with the new loan. Third, divide the total upfront costs by the monthly savings. The result is the number of months it will take to break even. If you plan to keep the car and the loan for longer than that break-even period, refinancing is likely worth it. If you plan to sell the car or pay off the loan before that point, the savings may never materialize.
Consider a concrete example. Suppose your current payment is $450 per month at 14 percent interest. A refinance offer comes in at $390 per month at 9 percent interest, with $150 in fees. Your monthly savings are $60. Divide $150 by $60, and your break-even point is two and a half months. That is an easy yes, assuming the term length is not extended in a way that erases the savings. Now suppose the new payment is $430 per month with $600 in fees. Your monthly savings are $20, and your break-even point is 30 months. If you plan to keep the car for five more years, it still works, but the margin is thinner and you need to be confident about your job stability and your plans for the vehicle.
Be careful with term extensions. A lender can offer you a lower monthly payment by stretching the loan term from 48 months to 72 months. Your payment drops, but you pay interest for two extra years. Run the total interest calculation, not just the monthly payment comparison. Add up all remaining payments on the current loan and compare that to all payments on the new loan. If the new loan costs more in total, the lower monthly payment is a trap, not a benefit.
How Much Credit Improvement Do You Actually Need?
There is no universal credit score threshold that unlocks dramatically better auto loan rates. Lenders set their own criteria, and the rate sheets they use are tiered. Moving from a 580 to a 620 might get you a slightly better rate. Moving from a 620 to a 680 often produces a meaningful drop. Moving from 680 to 720 can shave another point or two off your APR. The key insight is that refinancing with bad credit is not a single decision, it is a decision you can revisit as your credit improves.
If you are currently in the subprime tier, which generally means a score below 600, refinancing may still be possible, but the rate improvement might be modest. Some subprime lenders specialize in refinancing loans that were originated by other subprime lenders. The rate reduction might only be two or three percentage points, but on a $20,000 balance, that can still translate to real savings. The question is whether the fees and the hassle justify the gain. In many cases, waiting six to twelve months while making on-time payments and reducing your credit utilization can move your score enough to qualify for a noticeably better rate.
A year of on-time payments is a powerful signal to lenders. Payment history is the largest component of most credit scoring models. If you have made twelve consecutive on-time payments on your current auto loan, you have demonstrated that you can handle the obligation. That track record, combined with a modest reduction in credit card balances, can sometimes push you into a better rate tier even if your score has not moved dramatically. This is why many financial advisors suggest waiting at least twelve months after origination before pursuing a refinance, unless you have a compelling reason to act sooner, such as a cosigner release or an urgent need to lower your payment.
You should also check your credit reports for errors before applying. A collections account that was paid off but still shows a balance, or a late payment that was reported incorrectly, can drag your score down unnecessarily. Disputing errors takes time, but it is free and can sometimes produce a quick score bump. The Consumer Financial Protection Bureau offers guidance on how to dispute errors directly with the credit bureaus. Cleaning up your reports before you apply for refinancing increases your chances of getting the best possible offer.
The Risks of Extending Your Loan Term
Term extension is the most common way lenders make a refinance offer look attractive when it is not. A lower monthly payment feels like relief, especially when money is tight. But a longer term means more months of interest accruing on the same balance. If you are already several years into your current loan, extending the term back out to 60 or 72 months resets the clock and can significantly increase the total interest you pay.
There is also the depreciation problem. Cars lose value over time. If you extend your loan term, you increase the likelihood that you will owe more than the car is worth at some point during the loan. That situation, known as being upside down or underwater, makes it harder to sell or trade the vehicle without bringing cash to the table. It also increases your risk if the car is totaled in an accident, because your insurance payout may not cover the remaining loan balance. Gap insurance can mitigate that risk, but it adds another cost to the equation.
The smart approach is to compare total cost, not monthly payment. Ask the new lender for the total of all payments over the life of the loan. Compare that number to the total of all remaining payments on your current loan. If the new loan has a lower total cost and a payment you can comfortably afford, it passes the test. If the new loan has a lower monthly payment but a higher total cost, you are trading short-term relief for long-term expense. That trade-off is sometimes necessary, but it should be a conscious choice, not an accident.
When Refinancing After a Year of On-Time Payments Makes Sense
The twelve-month mark is a natural decision point for several reasons. First, you have established a payment history that lenders can evaluate. Second, your credit score has had time to recover from the initial hit of opening the auto loan. Third, the balance on your loan has decreased, which improves your loan-to-value ratio and makes you a less risky borrower in the eyes of many lenders. Fourth, you have had time to observe whether your financial situation is stable enough to commit to a new loan.
If you have made twelve on-time payments and your credit score has improved even modestly, it is worth gathering quotes. The process of getting a quote does not obligate you to accept anything. You can compare offers and decide whether the savings justify the switch. If the offers are not compelling, you can wait another six months and try again. There is no penalty for checking, as long as you do not submit multiple full applications in a short window, which can temporarily ding your credit score.
There are also situations where refinancing after a year is clearly the right move. If your current loan has a prepayment penalty, which is rare but not unheard of, you will want to factor that into your break-even calculation. If your current loan has a high fixed rate and you can qualify for a lower one, the savings accumulate every month. If you have a cosigner and you want to release them from the obligation, refinancing in your own name after a year of on-time payments is a common path. Each of these scenarios has its own math, but the twelve-month mark is a reasonable time to run the numbers.
How to Submit a Refinance Request and Compare Responses
The refinance process itself is straightforward if you approach it in an organized way. Start by pulling your credit reports and your current loan statement. You need to know your exact payoff amount, your current interest rate, and your remaining term. Then decide how much time you are willing to spend shopping. A focused week of gathering quotes is usually enough to get a clear picture of the market.
Here is a practical sequence to follow. First, use a connection service to submit a single request that reaches multiple lenders. This saves you from filling out the same form a dozen times and keeps your credit inquiries consolidated. Second, gather at least three offers so you can compare rates, fees, and terms side by side. Third, ask each lender for the total cost of the loan, not just the monthly payment. Fourth, read the fine print on fees, prepayment penalties, and any conditions attached to the offer. Fifth, choose the offer that produces the lowest total cost over the period you actually plan to keep the loan.
One option for borrowers with challenged credit is to use a platform that specializes in connecting applicants with lenders who work with less-than-perfect credit. If you have faced rejection from traditional banks, you might explore AutoTitleLoan as a starting point to see what types of financing options might be available to you. These services function as connectors, not direct lenders, and they can save you time by routing your request to multiple potential lenders at once. The key is to read the terms carefully and compare the total cost, not just the headline rate.
When you receive offers, pay attention to the APR, not just the interest rate. The APR includes fees, so it gives you a more accurate picture of the true cost of borrowing. A loan with a lower interest rate but high upfront fees can have a higher APR than a loan with a slightly higher rate and no fees. Compare APRs across offers to make an apples-to-apples comparison. Also check whether the new loan has a fixed or variable rate. Variable rates can rise over time, which introduces uncertainty into your budget. Fixed rates are generally safer for borrowers who need predictable payments.
If you are refinancing to lower your payment because of a temporary financial squeeze, consider whether a longer term is truly necessary or whether a smaller reduction in payment would suffice. Sometimes a modest rate reduction with the same term produces enough savings to ease the budget without extending the loan. Run the numbers both ways and see which one produces the better long-term outcome. If you are refinancing to save money over the long haul, prioritize total cost. If you are refinancing to survive a short-term crisis, prioritize payment relief but go in with a plan to refinance again or pay extra when the crisis passes.
The decision to refinance with bad credit is not a simple yes or no. It is a calculation that depends on your current rate, your new rate, the fees involved, the term length, and your plans for the vehicle. If the math works in your favor and you have a stable income, refinancing can be a smart move that lowers your monthly burden and reduces the total interest you pay. If the math does not work, waiting and improving your credit is often the better path. The important thing is to run the numbers, gather real offers, and make a decision based on your actual situation rather than a general rule of thumb. For more on timing your refinance around rate changes, see our guide on auto loan refinance when interest rates drop.