What Credit Score Do You Need for a Car Loan?
Your credit score is not the only factor in car loan approval. See the score tiers lenders use and how to offset a lower score with a larger down payment.
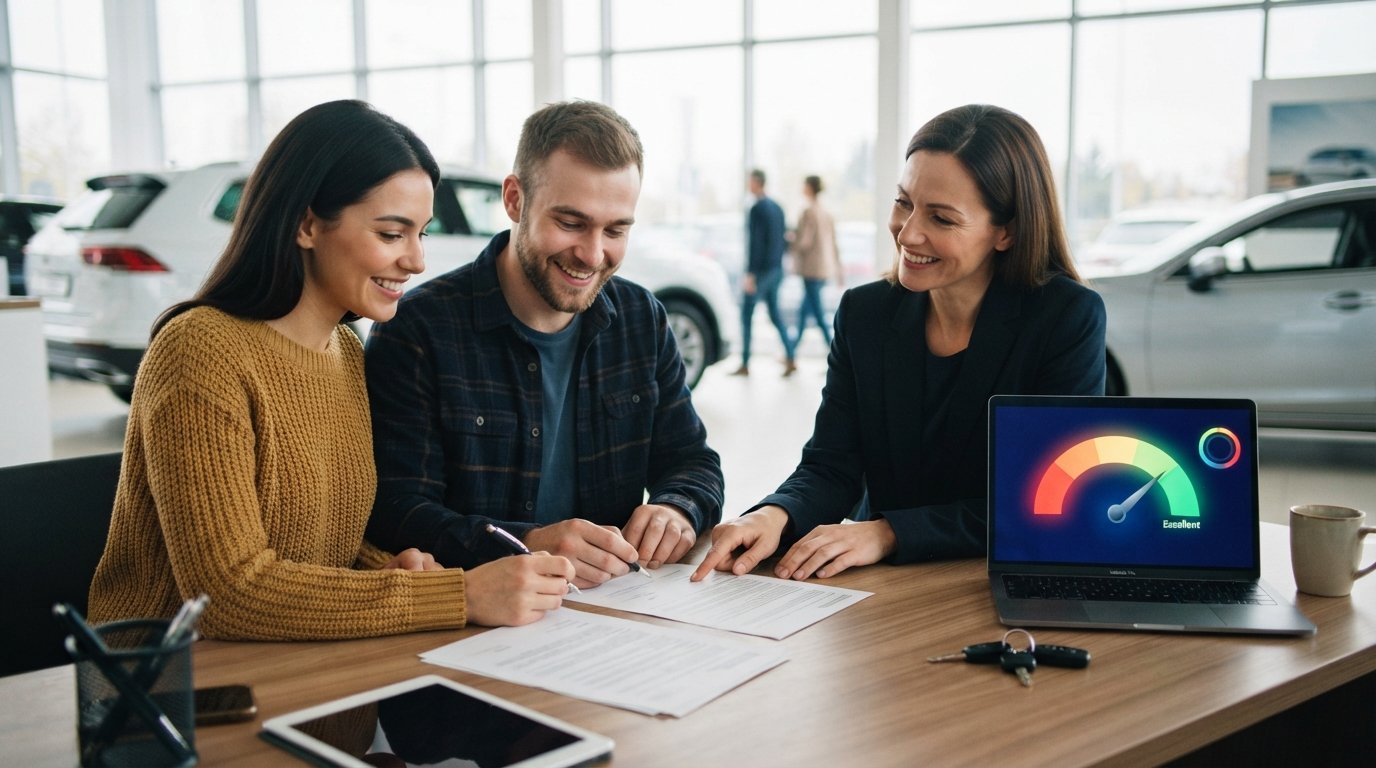
You are sitting in the dealership, or maybe just browsing online listings, and you have found the car you want. The only question standing between you and the keys is whether a lender will approve your loan. If your credit history is less than perfect, you are probably asking yourself a very specific question: what credit score do you need for a car loan? The answer is not a single number carved in stone. It is a range, a moving target that shifts based on the lender, the vehicle, and the rest of your financial profile. Understanding how lenders view your score, and what you can do to offset a lower number, is the key to getting approved and driving away with a payment you can afford.
Understanding the Credit Score Tiers Lenders Use
When lenders evaluate your application, they group borrowers into risk tiers based on credit score ranges. These tiers help them predict the likelihood that you will repay your loan on time. While different lenders and credit bureaus may adjust the exact cutoffs, the tiers generally follow a standard structure. Knowing where you land helps you set realistic expectations and understand the interest rate you are likely to see.
Here is a common breakdown of credit score tiers and what they typically mean for auto loan pricing:
- Super Prime (781 to 850): You are the lowest-risk borrower. Lenders compete for your business, and you qualify for the best advertised rates. Approval is almost certain for most vehicles and loan amounts.
- Prime (661 to 780): You are still a strong candidate. You will see competitive rates, though slightly higher than super prime. Most lenders will approve you without hesitation.
- Non-Prime (601 to 660): This is where the landscape starts to change. You may still qualify for traditional financing, but rates will be noticeably higher. Some banks may pass, while others will approve with conditions.
- Subprime (501 to 600): This is the territory where many traditional lenders stop approving. You will need to work with lenders that specialize in bad credit auto loans, and rates will be significantly higher. A larger down payment can help your case.
- Deep Subprime (300 to 500): Approval is difficult but not impossible. You will likely need a lender that focuses on this segment, and you should expect to provide a substantial down payment or a cosigner to secure a loan.
Understanding these tiers helps you estimate your position before you apply. If you fall into the subprime or deep subprime range, you are not out of options, but you need to approach the process strategically. The good news is that the auto lending market is diverse, and many lenders specialize in working with borrowers who have challenging credit histories.
Why Approval Can Happen Below the Commonly Cited Minimum
You may have heard that you need a score of 600 or 650 to get a car loan. While that is a common benchmark, it is not a hard floor. Lenders look at the full picture, not just the number. A score below 600 does not automatically disqualify you, especially if you work with a lender that specializes in subprime financing. These lenders have built their business models around assessing risk in different ways, and they may approve you based on factors beyond your credit score.
For example, a lender might consider your income stability, your down payment amount, and the type of vehicle you are buying. If you are putting down a large down payment, the lender has less exposure, which can offset a lower score. Similarly, if you are buying a newer, reliable car, the lender may feel more confident that the collateral will hold its value. This is why some borrowers with scores in the 500s get approved while others with scores in the 600s get rejected: the score is one piece of a larger puzzle.
It is also important to understand that auto loans use a specialized credit score called an auto-enhanced score. This version of your credit score weighs your history with auto loans and leases more heavily than general credit obligations. If you have a positive auto loan history, your auto-enhanced score may be higher than your general FICO score. Conversely, if you have never had an auto loan, your auto-enhanced score might be lower. This nuance can explain why a lender's decision seems to contradict the score you see on a consumer app.
The Difference Between Auto-Enhanced Scores and General Credit Scores
When you check your credit score through a bank or a free app, you are usually seeing a general credit score. This score is designed to predict the likelihood that you will repay any type of debt, from credit cards to mortgages. Auto lenders, however, often pull an auto-enhanced score, which is a version of your credit score tailored specifically to auto lending. This score emphasizes your history with car loans and leases, and it may weigh other factors differently.
The practical implication is that the score you see may not match the score the lender sees. If you have a strong history of paying auto loans on time, your auto-enhanced score could be higher, giving you a better shot at approval and a lower rate. If you have no auto loan history, your auto-enhanced score might be lower, which could make approval more challenging. This is why it is helpful to request a copy of your credit report and review it for any errors, and to understand that your general score is not the final word.
For borrowers with bad credit, the auto-enhanced score can be a double-edged sword. If you have a past auto loan that you paid on time, it can help you. If you have a repossession or a series of late payments, it can hurt you more than a general score would. In either case, the key is to know where you stand and to address any negative items on your report before you apply.
How Income, Down Payment, and Vehicle Age Can Offset a Lower Score
A low credit score does not exist in a vacuum. Lenders evaluate your application holistically, and several factors can compensate for a score that falls below the prime threshold. If you are worried about your score, focus on strengthening these other areas to improve your chances of approval and to secure a more favorable interest rate.
The most influential factors that can offset a lower score include:
- Income and employment stability: A steady job with a consistent income history reassures lenders that you can afford the payments. If you have been with the same employer for several years, that stability can work in your favor.
- Down payment size: A larger down payment reduces the amount you need to borrow, which lowers the lender's risk. If you can put down 20 percent or more, you may be approved even with a subprime score.
- Vehicle age and type: Newer cars and those with a strong resale value are more attractive to lenders because the collateral is more secure. Older, high-mileage vehicles may be harder to finance, or they may come with stricter terms.
- Debt-to-income ratio: Lenders look at how much of your monthly income goes toward debt payments. A low debt-to-income ratio can offset a lower credit score because it shows you have room in your budget for a new car payment.
These factors are not just theoretical. In practice, a borrower with a 580 score and a 20 percent down payment may get approved at a better rate than a borrower with a 620 score and no down payment. The lesson is that your credit score is not the only lever you can pull. By improving your income documentation, saving for a larger down payment, and choosing a vehicle that holds its value, you can strengthen your application and improve your odds.
If you have faced rejection from traditional lenders, it may be worth exploring low credit score car financing options that work in 2026, which can connect you with lenders who specialize in your situation. These options often consider the factors above, giving you a path forward even if your score is not perfect.
Steps to Estimate Your Position Before Applying
Before you fill out a single application, you should take steps to understand where you stand. This preparation can save you time, help you avoid unnecessary hard inquiries on your credit report, and increase your chances of getting approved with terms you can afford. The process does not need to be complicated, but it does require a bit of homework.
Follow these steps to estimate your credit position and prepare for the application process:
- Check your credit reports from all three major bureaus. You are entitled to free reports from Equifax, Experian, and TransUnion. Review them for errors, such as accounts that are not yours or payments reported late incorrectly. Dispute any inaccuracies before you apply.
- Obtain your credit scores. Many credit card companies and banks offer free access to your FICO score or VantageScore. While these may not be the exact auto-enhanced score a lender uses, they give you a ballpark figure. You can also purchase a FICO Auto Score from myFICO.com for a more precise estimate.
- Calculate your debt-to-income ratio. Add up your monthly debt payments (including rent or mortgage, credit cards, student loans, and any other loans) and divide by your gross monthly income. Lenders typically look for a ratio below 50 percent, and a lower number is better.
- Determine your down payment and budget. Decide how much cash you can put down and what monthly payment you can comfortably afford. Use an auto loan calculator to see how different loan amounts and interest rates affect your payment.
- Research lenders that match your profile. If your score is below 600, focus on lenders that specialize in bad credit auto loans. StartAutoLoan.com can connect you with a network of participating lenders and dealers who work with a range of credit profiles.
Once you have completed these steps, you will have a clearer picture of your credit position and the loan terms you can expect. This preparation also helps you avoid the trap of applying to multiple lenders in a short period, which can temporarily lower your score. Instead, you can target your applications to lenders that are likely to approve you, saving time and preserving your credit.
If you are ready to explore your options, you can find auto loan financing options through platforms that connect borrowers with lenders. These services are designed to help people who have been turned down elsewhere, and they can be a valuable resource as you navigate the process.
Strategies for Improving Your Chances with a Lower Score
If your credit score is below the prime threshold, you may be wondering what you can do to improve your chances of approval. The good news is that there are concrete steps you can take, both before you apply and during the loan process, to strengthen your application. These strategies are especially relevant for borrowers with bad credit or no credit history.
One of the most effective strategies is to save for a larger down payment. A down payment of 20 percent or more reduces the lender's risk and can make the difference between approval and rejection. It also reduces the amount you need to finance, which lowers your monthly payment and the total interest you pay over the life of the loan. If you can wait a few months and save more, it is often worth it.
Another strategy is to add a cosigner to your application. A cosigner with good credit can help you qualify for a loan that you might not get on your own. However, you should be aware that the cosigner is taking on significant risk, and if you miss payments, it will affect their credit as well. This option works best when you have a trusted family member or friend who is willing to help and who understands the commitment.
You can also work on improving your credit score before you apply. Simple steps like paying down credit card balances, making all payments on time, and disputing errors on your credit report can boost your score over time. Even a modest increase of 20 or 30 points can move you into a better tier and save you money on interest. If you are planning to buy a car in the next few months, start working on these habits now.
Finally, consider the type of vehicle you are buying. Lenders are often more willing to finance newer cars with lower mileage because they are more reliable and hold their value better. If you have a lower score, choosing a slightly newer, more dependable vehicle can improve your approval odds and your interest rate. On the other hand, very old or high-mileage cars may be harder to finance, or they may come with shorter loan terms and higher rates.
What to Expect During the Application Process
Once you have estimated your position and prepared your finances, the application process itself is straightforward. Most lenders will ask for basic information about your identity, income, and the vehicle you plan to purchase. They will then pull your credit report and score, and they may ask for additional documentation such as proof of income or residence.
If you apply through a connection service like StartAutoLoan.com, the process is designed to be streamlined. You submit your information once, and the service matches you with participating lenders or dealers who are likely to work with your credit profile. This can save you from having to fill out multiple applications, and it can increase your chances of finding a lender who is willing to approve you. The service is not a lender itself, but it connects you with a network of partners who can help.
After you receive an offer, review the terms carefully. Pay attention to the interest rate, the loan term, and any fees. Compare offers if you have more than one, and do not feel pressured to accept the first one you see. You are not obligated to take any loan, and it is always wise to read the fine print before you sign. If you have questions, ask the lender to explain anything that is unclear.
Remember that your credit score is a starting point, not a destiny. With the right preparation and a clear understanding of how lenders evaluate applications, you can find a car loan that fits your budget and your needs. Whether you have a perfect score or a challenged one, the key is to know your options and to approach the process with confidence.