Car Loans Explained: Rates, Approval, and Smart Borrowing
Car loans can be simple with the right approach. Compare rates, get preapproved, and even find options for bad credit to save money.
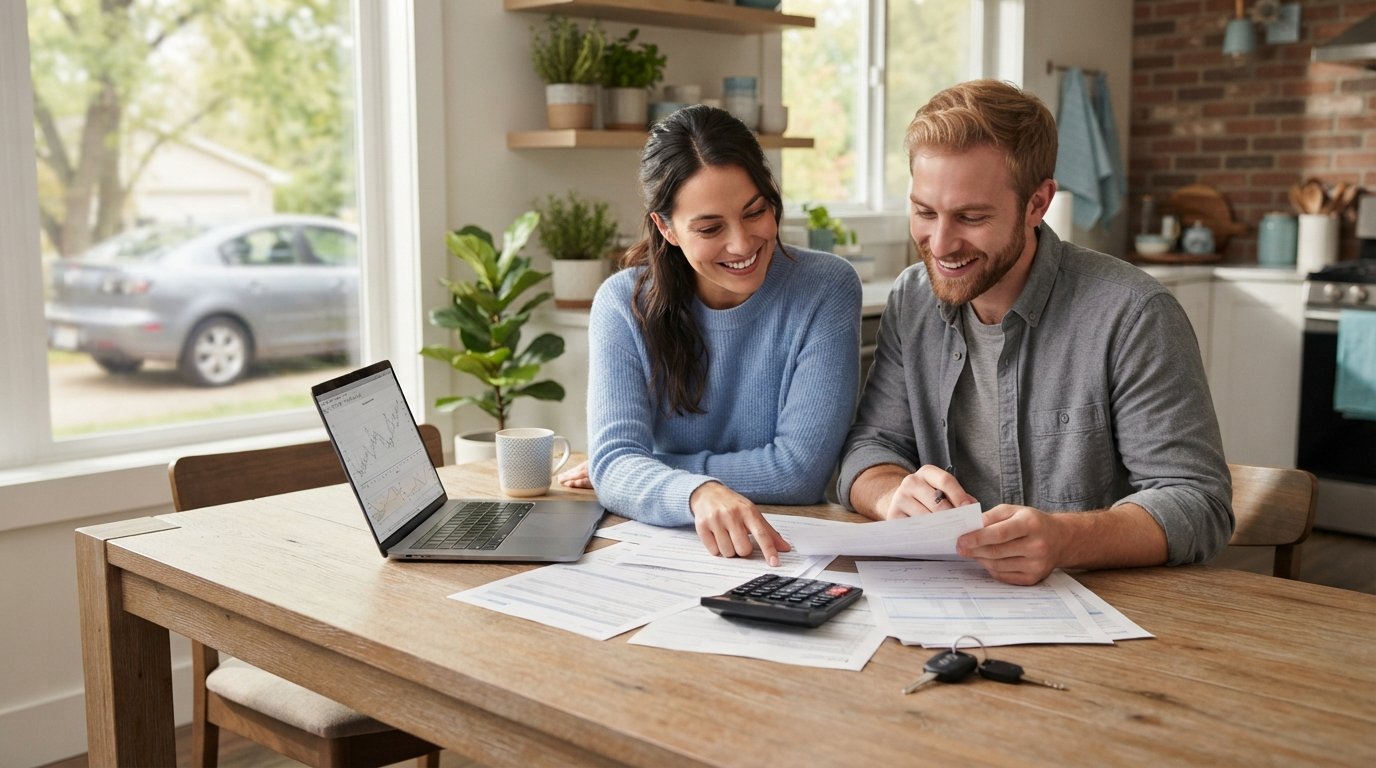
Buying a car is exciting, but the financing part can feel like a maze. Whether you have perfect credit or you have been turned down before, understanding how car loans work is the key to driving away with a deal you can afford. This guide breaks down everything you need to know about car loans, from how interest rates are set to how you can improve your chances of approval, even if your credit history is less than perfect.
How Car Loans Work: The Basics
A car loan is a secured loan, meaning the vehicle itself serves as collateral. When you borrow money to purchase a car, you agree to repay the loan amount plus interest over a set period, typically 36 to 72 months. The lender holds a lien on the vehicle until the loan is paid off. If you fail to make payments, the lender can repossess the car. Understanding this fundamental structure helps you see why lenders focus so heavily on your creditworthiness and the value of the vehicle.
The total cost of a car loan depends on several factors: the loan amount, the interest rate (APR), the loan term, and any fees. A longer term lowers your monthly payment but increases the total interest you pay over time. A shorter term does the opposite. Your goal is to find a balance that fits your budget while minimizing the overall cost. Before you start shopping, it helps to get preapproved for a car loan so you know your budget and can negotiate like a cash buyer.
Understanding Interest Rates and Your Credit Score
Your credit score is the single biggest factor lenders use to determine your interest rate. Borrowers with excellent credit (typically 720 and above) qualify for the lowest rates, while those with bad credit (below 600) may face significantly higher rates or outright rejection from traditional lenders. But your credit score is not the only factor. Lenders also consider your income, employment history, debt-to-income ratio, and the loan-to-value ratio (how much you borrow compared to the car's value).
If your credit is less than perfect, do not despair. Many lenders specialize in bad credit auto loans, and some even offer financing after bankruptcy. The key is to shop around and compare offers from multiple sources, including banks, credit unions, and online connection services like StartAutoLoan.com. Even a small difference in your interest rate can save you hundreds or thousands of dollars over the life of the loan.
Steps to Get Approved for Car Loans
Getting approved for a car loan requires preparation. Whether you are a first-time buyer or have been through financial difficulties, following a structured approach can improve your odds. Here is a step-by-step framework to guide you:
- Check your credit reports and scores. Obtain free copies from AnnualCreditReport.com and dispute any errors. Knowing where you stand helps you target the right lenders.
- Determine your budget. Use a car payment calculator to estimate monthly payments, factoring in insurance, fuel, and maintenance. Aim for a total car expense that is less than 15-20% of your take-home pay.
- Save for a down payment. A larger down payment reduces the loan amount and can offset bad credit. Even $1,000 or $2,000 can make a difference.
- Get preapproved. Preapproval gives you a clear idea of how much you can borrow and at what rate, and it signals to dealers that you are a serious buyer.
- Compare offers from multiple lenders. Do not settle for the first offer. Compare APR, fees, and terms from at least three lenders to ensure you are getting a fair deal.
Following these steps not only improves your chances of approval but also empowers you to negotiate better terms. Remember, lenders want your business, but they also want to minimize risk. By presenting yourself as a low-risk borrower, you can secure more favorable conditions.
Car Loans for Bad Credit and First-Time Buyers
Having bad credit or no credit history does not mean you cannot get a car loan. It simply means you need to look for lenders who specialize in these situations. Subprime lenders, credit unions, and online connection services cater to borrowers with challenging credit profiles. StartAutoLoan.com, for example, connects you with a network of participating lenders and dealers who work with bad credit, no credit, and even bankruptcy. The process is straightforward: you submit a secure application, and you can be matched with a local dealer or lender, sometimes within minutes.
First-time buyers face a similar challenge: no established credit. To overcome this, consider adding a co-signer with good credit, or look for lenders that offer first-time buyer programs. Making a larger down payment and choosing a less expensive car can also improve your approval odds. For a deeper dive into financing options for challenged credit, see our guide on used car loans for bad credit borrowers, which explains how to navigate the process and find competitive rates.
Comparing Car Loan Offers: What to Look For
When comparing car loan offers, the interest rate is just one piece of the puzzle. You also need to consider the loan term, fees, and any prepayment penalties. A lower rate with a longer term might cost more in total interest than a slightly higher rate with a shorter term. Always ask for the APR (annual percentage rate), which includes both the interest rate and certain fees, giving you a more accurate picture of the loan's cost.
Additionally, check whether the lender reports to credit bureaus. On-time payments can help you build or rebuild your credit, which is a valuable benefit. Also, inquire about any discounts, such as automatic payment discounts or loyalty programs. Do not be afraid to negotiate; some lenders may match or beat a competitor's offer if you present a written quote.
The Role of Connection Services in Auto Financing
Navigating the world of car loans can be overwhelming, especially if you have been rejected by traditional lenders. That is where connection services come in. These platforms, like StartAutoLoan.com, are not direct lenders; they are matchmakers. They connect you with a network of lenders and dealers who are more likely to approve your application based on your credit profile. This saves you time and effort, as you can fill out one application and receive multiple offers.
Using a connection service is particularly beneficial if you have bad credit, no credit, or a past bankruptcy. These services understand that traditional banks may not be the best fit for everyone, and they work with partners who specialize in these situations. The application process is secure and quick, and there is no obligation to accept any offer. It is a smart way to explore your options without damaging your credit further, as many connection services use a soft credit pull for prequalification.
Refinancing Your Car Loan: When and How
If you already have a car loan with a high interest rate, refinancing can save you money. Refinancing involves taking out a new loan to pay off the old one, ideally at a lower rate. This can lower your monthly payment or shorten your loan term, depending on your goals. You might consider refinancing if your credit score has improved since you originally financed the car, or if market rates have dropped.
To refinance, you will need to apply with a new lender, provide information about your current loan, and go through a similar approval process. It is important to compare offers and calculate the break-even point, considering any fees associated with the new loan. Refinancing is not for everyone, but for many, it is a path to significant savings. For those with bad credit, refinancing can be more challenging, but specialized lenders and connection services can help.
Frequently Asked Questions About Car Loans
What is the difference between a car loan and a lease?
A car loan finances the purchase of a vehicle, and you own the car once the loan is paid off. A lease is essentially a long-term rental; you make monthly payments to use the car for a set period, but you do not own it at the end. Leases often have mileage restrictions and wear-and-tear fees. Loans typically result in higher monthly payments but build equity.
Can I get a car loan with no credit history?
Yes, it is possible. Lenders that specialize in no-credit or first-time buyer programs may approve you, especially if you have a steady income and a down payment. A co-signer can also help. Connection services can match you with such lenders.
How much should I put down on a car?
A general rule is to put down at least 10-20% of the car's purchase price. A larger down payment reduces your loan amount and monthly payment, and it can help you get approved if your credit is imperfect. For bad credit borrowers, a down payment of 20% or more is often recommended.
When you are ready to explore your car loan options, consider using a connection service like AutoTitleLoan to compare offers from multiple lenders. It is a convenient way to see what you qualify for without impacting your credit score.
Car loans do not have to be a source of stress. With the right knowledge and preparation, you can find financing that fits your budget and your lifestyle. Whether you are buying your first car or refinancing an existing loan, take the time to understand your options, compare offers, and choose the path that sets you up for financial success.