First Time Car Buyer Auto Loan Scams to Avoid in 2026
First time car buyer auto loan scams to avoid include bait-and-switch rates and hidden add-ons. Learn the red flags that can save you thousands before you sign.
By Nicole Thompson
Buying your first car should feel exciting, not like a high-stakes negotiation where the deck is stacked against you. Yet first-time buyers are prime targets for deceptive financing tactics because they often lack experience with loan paperwork, interest rate math, and dealer sales pressure. The Federal Trade Commission has repeatedly warned that auto financing fraud costs consumers billions each year, and first-time buyers absorb a disproportionate share of that damage. Understanding the most common first time car buyer auto loan scams to avoid is not about becoming cynical. It is about walking into the dealership or lender's office with clear eyes and a short list of red flags that should make you pause, ask questions, or walk away entirely.
The good news is that most scams follow predictable patterns. Once you recognize the bait-and-switch rate quote, the mystery add-on package, or the blank contract slide, you gain the upper hand. This guide breaks down the specific tactics scammers use, how to spot them before you sign, and where to report suspected fraud if something goes wrong. If you have been turned down by traditional lenders or worry that your credit history limits your options, you have a right to transparent financing. Platforms like StartAutoLoan.com exist to connect buyers with lenders who operate above board, so you never have to accept shady terms out of desperation.
Bait-and-Switch Auto Loan Rates: The Advertised Number Is Rarely the Real One
You see a banner ad or a dealership window sticker promising 2.9 percent APR on a new car loan. You walk in, fill out an application, and suddenly the finance manager tells you the best rate they can offer is 8.9 percent because of your credit score or because that promotional rate "expired yesterday." This is the classic bait-and-switch, and it remains one of the most common first time car buyer auto loan scams to avoid. The advertised rate was never available to most buyers. It was a hook designed to get you through the door, where high-pressure tactics take over.Federal law requires that advertised rates include clear disclosures about who actually qualifies. If those disclosures are buried in tiny print or missing entirely, that is a warning sign. Legitimate lenders and dealers will tell you upfront that the best rates go to borrowers with excellent credit, and they will give you a realistic estimate based on your actual credit profile before you commit to anything.
To protect yourself, follow these steps before you ever set foot in a dealership:
- Get preapproved through a credit union, bank, or online lending platform. A preapproval letter gives you a concrete rate and loan amount, which becomes your baseline for comparison.
- Ask for the out-the-door price in writing. This includes the vehicle price, taxes, fees, and the total financed amount. If the dealer will not provide it, that is a red flag.
- Compare the dealer's offer side by side with your preapproval. If the dealer's rate is higher, ask why and do not accept vague answers about "market conditions."
- Walk away if the numbers change after you have agreed. A legitimate deal does not shift after a handshake.
If you have bad credit or no credit history, you may face higher rates regardless. That is why starting with a preapproval through a platform that works with subprime lenders can give you a realistic picture before you shop. Our guide on best financing options for first time car buyers walks through how to build that baseline so you are never negotiating blind.
Hidden Add-Ons: How Extra Products Get Folded Into Your Loan
You agree to a loan amount, sign the paperwork, and drive home. Weeks later, you notice your monthly payment is higher than you expected, or you receive a welcome packet for products you never asked for: extended warranties, gap insurance, paint protection, credit life insurance, or rustproofing. These add-ons can add thousands of dollars to your loan and are often slipped into the contract without clear disclosure. This is not always illegal, but it is deceptive when the finance manager rushes through the paperwork or buries the line items in a dense contract.
The FTC has taken action against dealers who packed add-ons into loans without consumer consent, and several state attorneys general have pursued similar cases. The pattern is consistent: the buyer is told to sign here and initial there, with no explanation of what each product costs or whether it is optional. First-time buyers are especially vulnerable because they may not know that gap insurance, for example, can often be purchased separately for far less, or that extended warranties are almost always negotiable.
Here is how to protect yourself from add-on fraud:
- Ask for an itemized breakdown of every charge. Every fee, product, and service should be listed separately with its price.
- Decline everything you did not ask for. You have the right to say no to any add-on, and the dealer cannot make the loan contingent on purchasing them.
- Check whether the add-on is already covered by your auto insurance. Many gap insurance and roadside assistance products duplicate coverage you already have.
- Read the finance contract before signing. Look for line items labeled "optional" or "dealer-installed" and question each one.
If a finance manager tells you that an add-on is "required by the lender" or "mandatory for approval," that is almost always false. Lenders may require certain coverage, such as collision insurance, but they do not require dealer-specific products like paint sealant or VIN etching. If you feel pressured, ask to take the contract home overnight. A legitimate dealer will let you review it. A scammer will insist you sign immediately.
Blank or Incomplete Finance Paperwork: Never Sign What You Cannot Read
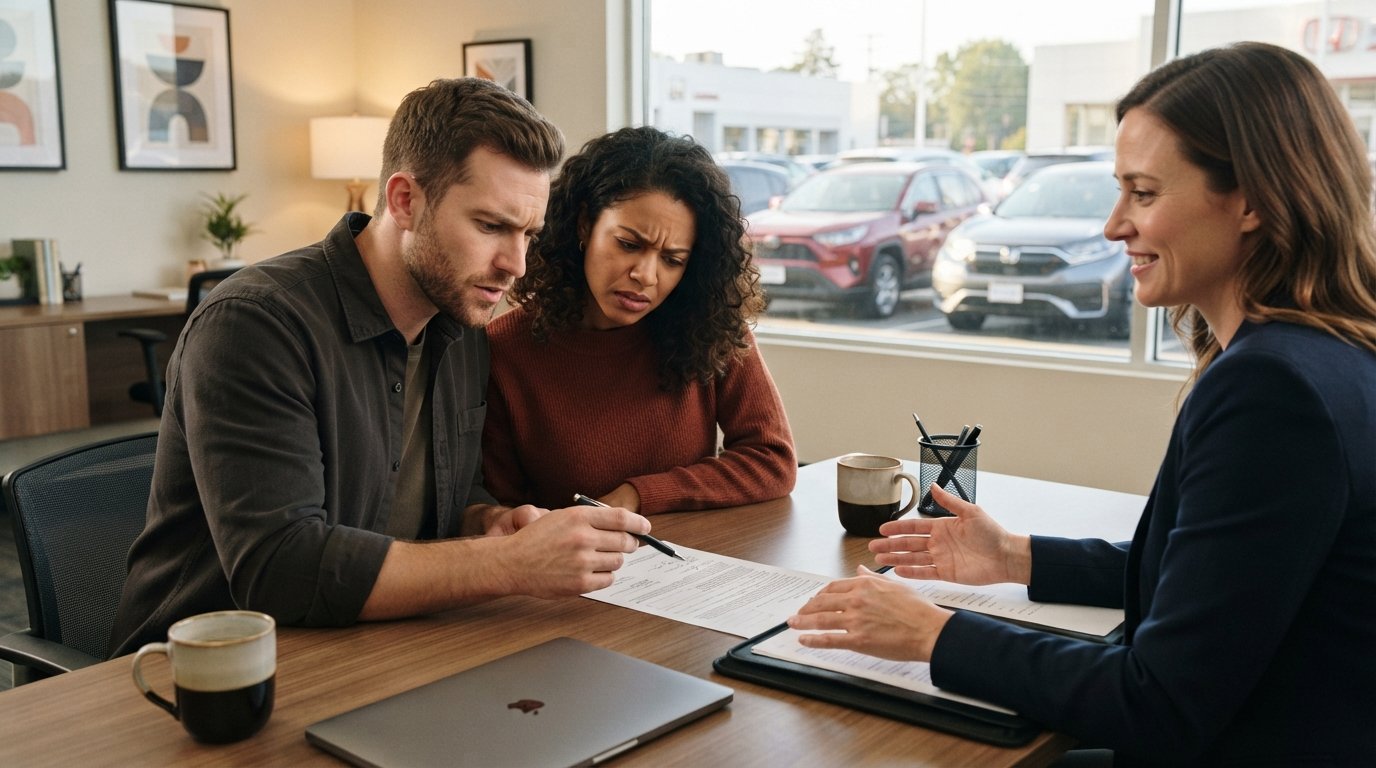
One of the most dangerous tactics in auto financing is the pressure to sign a contract with blank fields or incomplete terms. The finance manager might say, "We will fill in the final numbers later," or "This is just a standard form, do not worry about the details." Once you sign, you have agreed to whatever they write in those blank spaces. This is how buyers end up with interest rates far higher than discussed, loan terms extended by years, or add-ons they never approved.
Consumer protection attorneys consistently warn that signing incomplete paperwork is one of the fastest ways to lose legal leverage. If the contract does not match what you negotiated, you may have little recourse because your signature indicates agreement. Some predatory dealers use this tactic specifically on first-time buyers, knowing they are eager to get the keys and less likely to demand a complete document.
The rule is simple: never sign a contract with blank fields. If the dealer says the numbers will be filled in later, insist that they be filled in now, in your presence, before you sign. Take a photo of every page with your phone. If the dealer refuses to let you photograph the contract or review it at your own pace, leave. No car is worth signing away your financial protection.
Similarly, be wary of any dealer who presents a "spot delivery" contract, which allows you to take the car home before financing is finalized. In a spot delivery, the dealer may later call you back and demand you sign a new contract with worse terms, claiming the original financing fell through. This practice, sometimes called a "yo-yo" sale, is illegal in many states but still happens. If you are asked to sign a second contract with different terms, you have the right to refuse and return the car under the original agreement.
Misrepresented Loan Terms: When the Numbers Do Not Add Up
Misrepresenting loan terms is broader than bait-and-switch. It includes lying about the interest rate, the length of the loan, the total amount financed, or whether the loan includes a prepayment penalty. A finance manager might tell you the loan is a 60-month term when the contract says 72 months, or quote you a monthly payment without disclosing that it includes a balloon payment due at the end.
One common trick is the "monthly payment focus." The dealer asks, "What monthly payment can you afford?" and then works backward to structure a loan that meets that number by extending the term or adding fees. A longer term lowers the monthly payment but dramatically increases the total interest you pay. A seven-year loan on a used car can cost you thousands more than a five-year loan, even at the same interest rate.
Another red flag is when the dealer refuses to give you the annual percentage rate (APR) in writing. The APR is the true cost of borrowing, including fees. If a dealer only talks about monthly payments and avoids discussing APR, that is a sign they are hiding something. Legitimate lenders will always disclose the APR clearly.
To verify the terms you are offered, use an online auto loan calculator before you sign. Plug in the loan amount, interest rate, and term, and see whether the monthly payment matches what the dealer quoted. If the numbers do not align, ask for an explanation. If the explanation does not make sense, walk away.
For buyers with bad credit, the risk of misrepresented terms is even higher. Predatory lenders may target subprime borrowers with loans that carry triple-digit APRs or require large down payments that are never applied to the principal. If you have been rejected by traditional lenders, working with a connection service that pre-screens lenders can help you avoid these traps. StartAutoLoan.com, for example, connects buyers with a network of lenders who specialize in bad credit and first-time buyer financing, giving you multiple offers to compare rather than a single take-it-or-leave-it deal.
Where to Report Suspected Auto Financing Fraud
If you believe you have been the victim of a first time car buyer auto loan scam, you have several avenues for reporting. Acting quickly can protect you legally and financially, and it helps regulators shut down predatory operations before they harm other buyers.
- File a complaint with the Consumer Financial Protection Bureau (CFPB). The CFPB accepts complaints about auto loans, dealer financing, and add-on products online or by phone.
- Contact your state attorney general's office. Many states have dedicated consumer protection divisions that investigate auto financing fraud.
- Report to the Federal Trade Commission (FTC). The FTC collects complaints and can take action against dealers or lenders engaged in deceptive practices.
- Notify your state's motor vehicle dealer licensing board. If the fraud involved a licensed dealer, the board can investigate and revoke their license.
- Consult a consumer protection attorney. If you have signed a fraudulent contract, an attorney can advise you on your rights and whether you can cancel the loan or recover damages.
Keep copies of every document you signed, every email or text exchange, and any notes you took during the negotiation. The more evidence you have, the stronger your case. Do not let embarrassment stop you from reporting. Predatory lenders count on silence, and speaking up is the best way to protect yourself and others.
If you are still in the shopping phase and want to avoid these scams altogether, consider working with a service that connects you to multiple lenders and lets you compare offers before you visit a dealership. CarLoanRefinancing.com offers educational resources and rate comparison tools that can help you understand what a fair loan looks like, and StartAutoLoan.com can match you with lenders who work with first-time buyers and challenged credit. The more offers you have in hand, the less power any single dealer has to pressure you into a bad deal.
Building a Scam-Resistant Mindset Before You Shop
The best defense against auto loan scams is preparation. Before you step onto a lot or submit an application, know your credit score, know your budget, and know the fair market value of the car you want. Get preapproved from at least one outside lender so you have a concrete offer to compare against whatever the dealer presents. Decide in advance that you will not sign anything you have not read, that you will not accept add-ons you did not request, and that you are willing to walk away if the numbers change.
First-time buyers often feel pressure to prove they are serious or to avoid disappointing a salesperson who has spent time with them. Remember that this is a business transaction, not a favor. A reputable dealer will respect your diligence. A scammer will try to rush you. The difference between a good loan and a predatory one can be tens of thousands of dollars over the life of the loan, so taking an extra hour to review paperwork is always worth it.
Finally, lean on educational resources. The more you understand about how auto loans work, the harder it is for anyone to deceive you. Whether you are buying new, used, or refinancing an existing loan, transparency should be non-negotiable. StartAutoLoan.com provides a streamlined application that connects you with participating lenders, and it does not pressure you to accept any offer. That is the standard every first-time buyer deserves.