Understanding APR on a Car Loan Beyond the Advertised Number
Understanding APR on a car loan beyond the advertised number helps you rank offers by total cost and avoid paying for fees and add-ons you did not expect.
A car loan advertisement usually leads with one big number: the APR. It might be 3.9 percent, 6.5 percent, or something that looks too good to pass up. But that advertised figure is a starting point, not the final word on what you will actually pay. Searchers who want to look past the headline rate need a clearer picture of how APR works, what it includes, and how competing offers can look completely different once you compare them on equal footing. This guide walks through the real math behind auto loan APR, the fees and terms that change the equation, and a simple method to rank offers apples to apples so you can choose the loan that costs the least over its full life.
What APR Actually Includes (And What the Interest Rate Leaves Out)
The interest rate is the cost of borrowing the principal balance, expressed as a percentage. The APR, or annual percentage rate, is broader. It folds in the interest rate plus certain fees and charges that are financed as part of the loan, then expresses that total cost as a yearly rate. That is why the APR on a car loan is almost always higher than the stated interest rate, and why the gap between the two tells you something useful about the loan's fee structure.
Under the federal Truth in Lending Act, lenders must disclose the APR along with the finance charge, amount financed, total of payments, and payment schedule. This standardized disclosure is designed to let you compare offers from different lenders more fairly. But the APR calculation assumes you keep the loan to maturity and make every payment on time. It does not account for prepayment penalties, optional add-ons you agree to at the dealership, or the cost of extending the term. Understanding APR on a car loan beyond the advertised number means recognizing both what the figure captures and what it leaves out.
Here is what the APR typically includes and excludes, which helps explain why two loans with the same interest rate can carry different APRs:
- Included in APR: The base interest rate, origination or loan processing fees, and certain required charges financed into the loan.
- Usually excluded from APR: Optional products like extended warranties, gap insurance, and credit insurance if you choose them separately, plus late fees and prepayment penalties.
- Sometimes excluded depending on structure: Dealer documentation fees, title and registration costs, and taxes, which vary by state and deal.
Because of these exclusions, the advertised APR is a useful benchmark but not a complete cost estimate. A loan with a slightly higher APR but no prepayment penalty and no mandatory add-ons may cost less overall than a lower-APR loan loaded with fees. The next sections show how to compare these differences systematically.
Comparing Offers With Different Terms and Down Payments
Two lenders can advertise the same APR and still produce very different total costs if the loan terms or down payments differ. A shorter term usually carries a higher monthly payment but less total interest, while a longer term lowers the monthly payment and raises the total interest paid. The APR alone does not tell you which structure is cheaper for your situation; you have to compare the total of payments and the finance charge side by side.
Down payments change the math in a similar way. A larger down payment reduces the amount financed, which lowers both the monthly payment and the total interest, even if the APR stays the same. A smaller down payment may come with a higher APR because the lender carries more risk, or it may require private mortgage insurance-like products such as guaranteed auto protection. When you compare offers, hold the down payment constant or compare the total cost for each down payment scenario separately. Otherwise you are mixing variables and the comparison becomes meaningless.
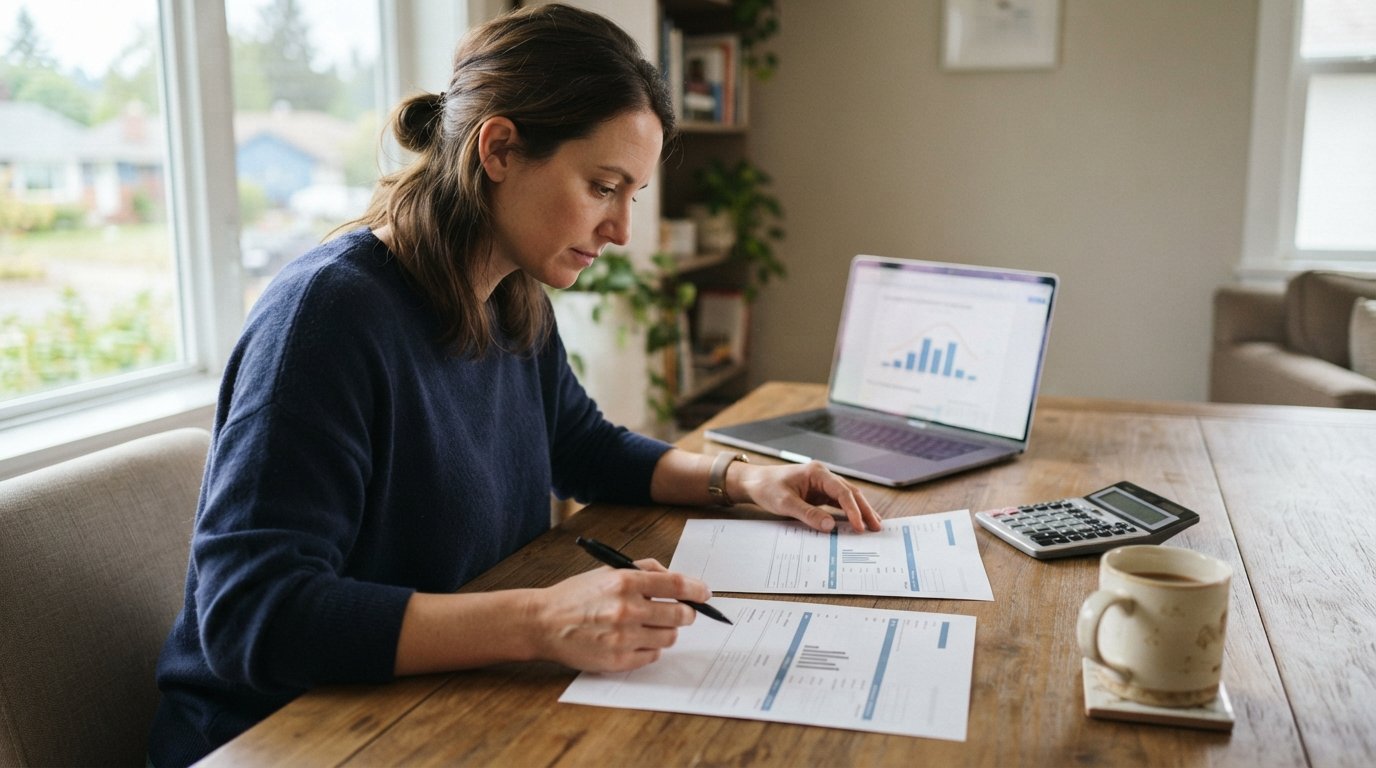
A practical way to compare offers with different terms and down payments is to build a simple comparison table for each scenario. List the amount financed, APR, term in months, monthly payment, total of payments, and total interest. Then rank the offers by total of payments, not by APR or monthly payment alone. The lowest total of payments over the period you actually plan to keep the car is usually the best deal, assuming the fees and add-ons are comparable. If you plan to sell or trade the car before the loan ends, the comparison should focus on the total cost up to that point, including any prepayment penalties.
Fees, Add-Ons, and Prepayment Penalties That Change the Math
The advertised APR is calculated on a specific set of assumptions, and dealership add-ons can quietly change the real cost. Extended warranties, gap insurance, paint protection, and credit insurance are often rolled into the loan. Even if these products are not part of the APR calculation, financing them increases the amount you borrow and the interest you pay on that amount. A $2,000 add-on financed at 7 percent over 60 months adds roughly $400 in interest, which effectively raises the cost of the loan beyond the advertised figure.
Prepayment penalties are another factor the APR often ignores. Some loans charge a fee if you pay off the balance early, which reduces the benefit of refinancing or making extra payments. Others allow prepayment without penalty but may have a minimum interest charge. Before signing, ask whether the loan has a prepayment penalty and how it is calculated. If you plan to refinance later, a no-penalty loan is usually worth a slightly higher APR because it preserves your flexibility.
Documentation fees, dealer fees, and title fees also vary by state and lender. These are sometimes financed and sometimes paid upfront. When comparing offers, add all upfront costs to the total cost of the loan, then compare that combined figure across lenders. A loan with a lower APR but a $599 documentation fee may be more expensive than a loan with a slightly higher APR and no documentation fee. The key is to normalize every offer to the same basis: total cash out the door, including fees, over the same holding period.
A Simple Method to Rank Offers Apples to Apples
To compare auto loan offers fairly, you need to convert each one into a common set of numbers. The method below works whether you are comparing dealer financing, credit union loans, or online lenders. It takes about ten minutes per offer and prevents the most common mistake: choosing the lowest APR when a different offer would have cost less overall.
- Collect the full disclosure for each offer. Ask for the APR, finance charge, amount financed, total of payments, payment schedule, and a list of all fees and optional products included. Lenders are required to provide this information before you sign.
- Normalize the down payment and term. Compare offers using the same down payment and the same number of months. If an offer requires a different down payment, calculate the total cost for that scenario separately and compare like with like.
- Add all upfront and financed fees. Include documentation fees, title fees, and any add-ons you actually want. Exclude optional products you would decline. This gives you the true amount financed and the true total cost.
- Calculate total cost over your expected holding period. If you plan to keep the car for the full term, use the total of payments. If you plan to sell or refinance earlier, estimate the payoff balance at that point and add the payments made plus any prepayment penalty.
- Rank by total cost, then check flexibility. The lowest total cost is usually the best deal, but also check for prepayment penalties and whether the lender reports to credit bureaus. A slightly higher total cost with no penalty and positive credit reporting can be worth it.
This method turns a confusing pile of offers into a clear ranking. It also reveals when an advertised APR is misleading: a loan with a low APR but a long term and financed add-ons can rank below a loan with a higher APR and a shorter term. The goal is not to find the lowest APR but to find the lowest total cost for the way you actually plan to use the loan.
Where to Find Offers and How StartAutoLoan.com Fits In
If you have been rejected by traditional lenders or have a thin credit file, comparing offers can feel impossible. That is where a connection service can help. StartAutoLoan.com is an independent online platform that connects consumers with auto loan financing options from a network of participating lenders and dealers. It is not a direct lender, bank, or dealership. The service is designed for people with bad credit, no credit history, past bankruptcies, and first-time buyers who need to see what options are available before committing.
Using a connection service does not replace the comparison method above; it feeds it. You can submit one request and receive multiple offers to compare, which makes it easier to normalize terms, fees, and down payments. For readers who want to explore financing options after a rejection, AutoTitleLoan is an independent platform that connects consumers with auto loan financing options and serves as a connection service rather than a direct lender. It focuses on individuals who have faced rejection from traditional lenders, and it provides educational resources to help you understand the process. Whether you use that service or another, the key is to gather multiple offers and rank them using total cost, not the advertised APR alone.
Putting It All Together: The Real Cost of a Car Loan
Understanding APR on a car loan beyond the advertised number means looking at the full picture: the interest rate, the fees folded into the APR, the add-ons and penalties outside it, and the term and down payment that shape the total cost. A low APR is a good starting point, but it is not a guarantee of the best deal. The most reliable approach is to collect full disclosures, normalize the terms, and rank offers by total cost over your expected holding period. That habit will save you money whether you are buying your first car, refinancing an existing loan, or rebuilding credit after a setback.