Car Loan Application Documents Checklist for Bad Credit Borrowers
Gather the right paperwork before you apply. This car loan application documents checklist for bad credit borrowers helps you avoid delays and get approved faster.
When you have bad credit, the paperwork you bring to a car loan application can make the difference between a quick approval and a frustrating dead end. Lenders see dozens of applications every day, and a complete, organized file signals that you are serious, stable, and worth the risk. This car loan application documents checklist for bad credit borrowers will help you assemble everything upfront, so you can avoid delays and put your best foot forward with subprime lenders.
StartAutoLoan.com works with a network of participating lenders and dealers who specialize in bad credit auto loans. The platform is a connection service, not a direct lender, and its application tool is designed to match you with financing options even if you have been rejected elsewhere. Before you submit your request, though, you need the right documents in hand. Below is a detailed breakdown of what to gather, why each item matters, and how to handle common problems like missing or inconsistent paperwork.
Why a Complete Document Package Matters for Bad Credit Borrowers
Subprime lenders take on more risk than traditional banks, so they rely heavily on documentation to verify your ability to repay. A missing pay stub or an unexplained gap in bank statements can push your application to the bottom of the pile or trigger a denial. On the other hand, a well-organized file shows that you are financially responsible and reduces the lender's uncertainty. In many cases, the difference between a conditional approval and a full approval comes down to how quickly you can provide the requested documents.
Keep in mind that every lender has slightly different requirements, but most will ask for the same core set of items. The checklist below covers the most common documents you will need. Having them ready before you apply can speed up the process and improve your chances of getting approved at a reasonable interest rate.
Proof of Identity: The Starting Point
Every auto loan application begins with verifying who you are. Lenders need to confirm your identity to prevent fraud and to comply with federal regulations. For bad credit borrowers, a clean identity verification also helps build trust and demonstrates that you are a legitimate applicant.
You will typically need one or more of the following documents:
- A valid driver's license or state-issued ID card
- A Social Security card (or proof of Social Security number)
- A passport or other government-issued photo ID
Make sure your name and address match across all documents. If you recently moved, update your ID or bring a utility bill that shows your current address. Lenders may also ask for a copy of your Social Security card, but some will accept a W-2 or pay stub that displays the number. If you do not have a Social Security number, some subprime lenders may accept alternative forms of identification, such as an Individual Taxpayer Identification Number (ITIN), so be sure to ask.
Proof of Income: Showing You Can Repay the Loan
Income verification is the most critical part of the application for bad credit borrowers. Lenders want to see that you have a steady, reliable source of income that can cover your monthly car payment and other obligations. The type of proof you provide depends on how you earn money.
If you are a traditional employee, you can usually supply:
- Your two most recent pay stubs
- A W-2 form from the previous year
- Bank statements showing direct deposit of your paycheck
For gig workers, freelancers, and self-employed applicants, the documentation requirements are more involved. Lenders may ask for:
- Your last two years of tax returns (personal and business, if applicable)
- 1099 forms or profit and loss statements
- Three to six months of business or personal bank statements
- Invoices or contracts showing ongoing work
If you receive income from sources other than employment, such as Social Security, disability, child support, or alimony, bring documentation for those as well. This could include award letters, court orders, or bank statements showing regular deposits. The key is to demonstrate that your income is consistent and sufficient to cover the loan. If you are wondering whether you can get approved without traditional income proof, our guide on getting a car loan without income proof explains alternative documentation options that some lenders accept.
When preparing income documents, make sure they are recent (usually within the last 30 to 60 days) and clearly show your name and the deposit amounts. Highlight or tab the relevant pages if you are submitting paper copies. For self-employed borrowers, a signed letter from your accountant or a current client contract can help strengthen your file if your tax returns show lower income than you actually earn.
Proof of Residence: Confirming Your Address
Lenders need to know where you live to verify your identity and to assess stability. A longer tenure at your current address can be a positive signal, especially if you have bad credit. You will typically need to provide one or two documents that show your name and current address. Common examples include:
- A recent utility bill (electricity, water, gas, or internet)
- A lease agreement or mortgage statement
- A bank statement or credit card statement mailed to your address
- A voter registration card or vehicle registration
Make sure the document is dated within the last 60 days and that your name appears exactly as it does on your application. If you live with someone else and your name is not on the bills, ask your landlord for a letter confirming your residency or provide a notarized statement from the person you live with. Some lenders may accept a recent pay stub with your address, but it is safer to bring a dedicated proof of residence document.
Bank Statements: More Than Just Numbers
Bank statements are a window into your financial habits. Lenders review them to verify your income, check for overdrafts, and assess how you manage your money. For bad credit borrowers, a clean bank statement with regular deposits and no negative balance days can be a strong point in your favor.
Most lenders will ask for the last two to three months of statements from your primary checking account. They look for:
- Regular, consistent deposits that match your stated income
- No repeated overdraft fees or returned payments
- Sufficient balance to cover a down payment or monthly payment
- No unexplained large deposits that could indicate borrowed funds
If your statements show irregular income or occasional overdrafts, do not panic. Be prepared to explain any anomalies. For example, if you received a tax refund or a one-time bonus, point that out. If you had a temporary financial setback, such as a medical bill, a brief explanation can go a long way. Lenders appreciate transparency, and a straightforward explanation can turn a potential red flag into a non-issue.
When submitting bank statements, make sure all pages are included, even the ones that seem unimportant. Missing pages can raise questions and slow down the process. You can often download statements directly from your bank's website and email them as PDFs, which is faster and cleaner than printing and scanning.
Insurance Requirements: Protecting the Lender's Collateral
Auto lenders require you to carry full coverage insurance on any vehicle they finance. This protects their investment if the car is totaled or stolen. Before you finalize your loan, you will need to provide proof of insurance that meets the lender's minimum requirements. Typically, this means comprehensive and collision coverage with deductibles that are not too high.
If you do not have insurance yet, you can usually get a quote and bind coverage once you have selected a vehicle. Some lenders will accept a binder or a declaration page from your insurance company. Be prepared to show the policy limits and deductibles. If you are unsure what coverage is required, ask the lender before you sign any paperwork. Driving without insurance is illegal in most states and can result in additional fees or loan default.
What to Do When a Document Is Missing or Inconsistent
Missing or inconsistent documents are common, especially for borrowers with complicated financial histories. The key is to address the issue proactively rather than hoping the lender will not notice. If you are missing a document, contact the lender or dealer and ask what alternatives they accept. Many subprime lenders are flexible and will work with you to find a solution.
For example, if you cannot find your W-2, you can request a transcript from the IRS or provide your last two pay stubs and a signed letter explaining the situation. If your bank statements show a name variation (such as a maiden name), bring a marriage certificate or a legal name change document to bridge the gap. If your income varies from month to month, a letter from your employer or a profit and loss statement can help clarify.
Inconsistencies between documents can also cause delays. Make sure your address, name, and income figures match across all paperwork. If you recently changed jobs or moved, bring a letter explaining the change. Lenders understand that life happens, but they need to see a coherent story. Being upfront and organized can turn a potential problem into a minor hurdle.
If you have already been rejected by traditional lenders, consider using a connection service like AutoTitleLoan to explore alternative financing options. These platforms work with lenders who specialize in bad credit and can guide you through the documentation process.
Additional Documents That Can Strengthen Your Application
Beyond the core checklist, some documents can boost your chances of approval or help you secure better terms. While not always required, having them ready can set you apart from other applicants.
Consider gathering:
- Proof of down payment (bank statement or cashier's check)
- References from previous landlords or employers
- Proof of any additional income, such as side gigs or rental income
- A letter of explanation for any credit blemishes (e.g., bankruptcy, repossession)
- Proof of enrollment in credit counseling or financial education courses
A down payment is particularly helpful for bad credit borrowers because it reduces the lender's risk. Even a modest down payment of 10 to 20 percent can improve your approval odds and lower your interest rate. If you have a trade-in vehicle, bring the title and any loan payoff information. The dealer can appraise the trade-in and apply the value toward your down payment.
A letter of explanation is your chance to tell your side of the story. If you went through a bankruptcy or had a repossession due to a job loss, a brief, honest letter can humanize your application. Keep it concise and focus on what you have done to improve your financial situation since then.
How to Organize Your Documents for a Smooth Application
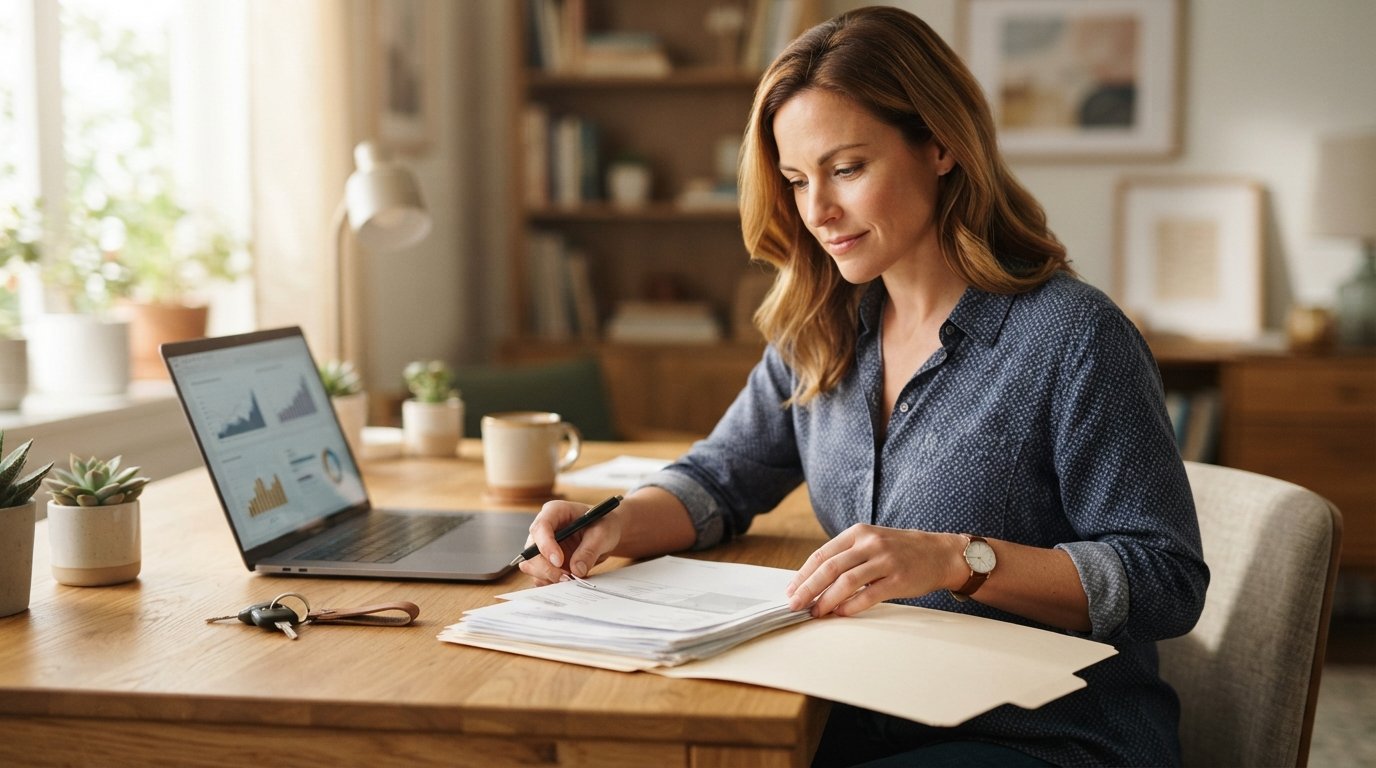
Organization is your secret weapon. Lenders process many applications, and a well-organized file makes their job easier, which can work in your favor. Create a folder (physical or digital) with clearly labeled sections for identity, income, residence, bank statements, and insurance. Use a checklist to track what you have and what you still need.
If you are applying online through StartAutoLoan.com, you can upload digital copies of your documents. Make sure the scans or photos are clear and legible. Name each file descriptively, such as "PayStub_Jan2026.pdf" or "BankStatement_Checking_3Months.pdf". This small step can prevent confusion and speed up verification.
Before you submit, review everything one more time. Check that your name and address are consistent, that dates are current, and that all pages are included. A few extra minutes of review can save you days of back-and-forth later.
Finally, remember that the car loan application documents checklist for bad credit borrowers is a starting point, not a guarantee. Each lender may have unique requirements, so always ask for a specific list before you apply. With the right paperwork and a proactive attitude, you can navigate the application process with confidence and drive away in the vehicle you need.