Classic Car Financing With Bad Credit: A 2026 Guide
Classic car financing with bad credit is possible with specialty lenders and larger down payments. Learn how to navigate approval and valuation issues.
By Lauren Mitchell
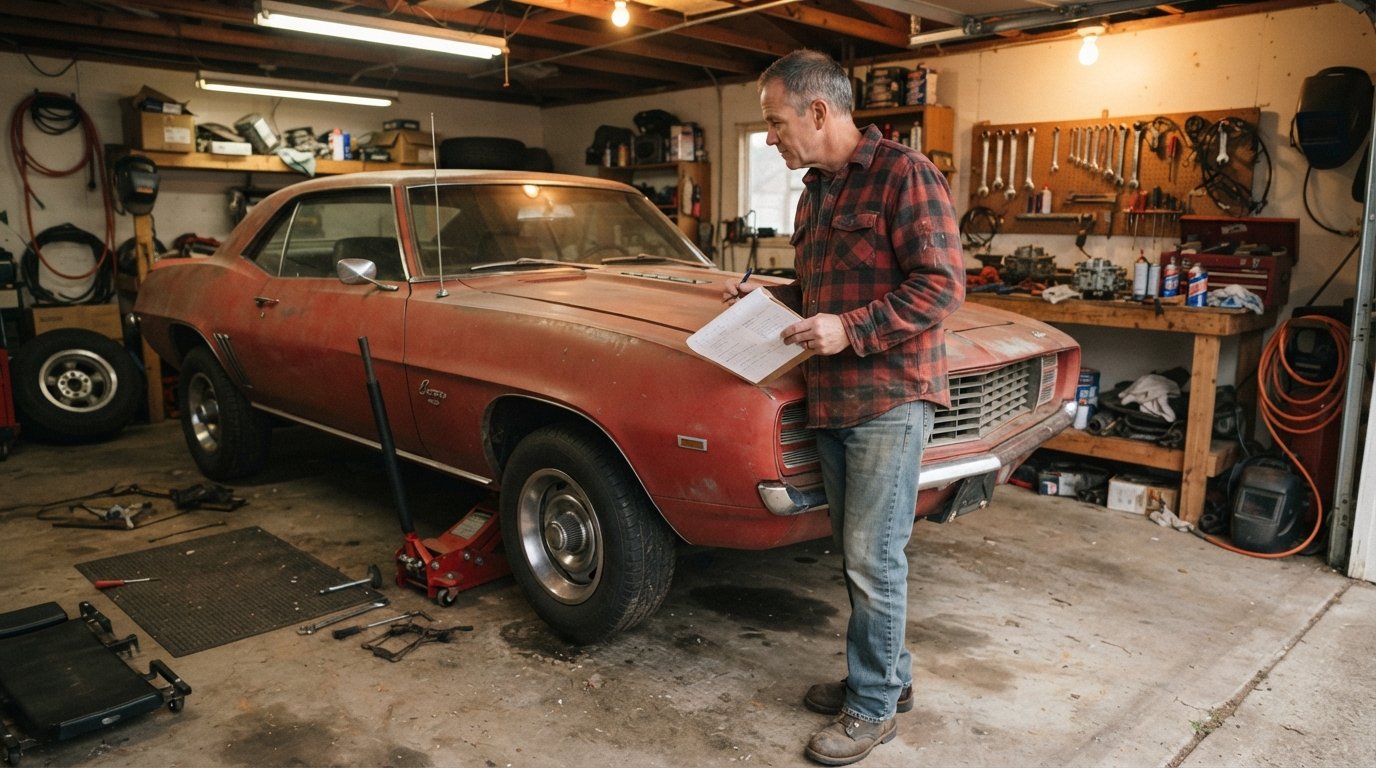
You have found the perfect 1969 Camaro, but your credit score is sitting in the 500s. The seller wants cash, your bank just said no, and you are wondering if the dream is dead. It is not. Classic car financing with bad credit is possible, but it requires a different playbook than the one you would use for a used Honda. Lenders see a 50-year-old vehicle as a risk, not an asset, and your credit history adds another layer of caution. The good news is that specialized lenders and creative structures exist for enthusiasts who have been turned down by traditional banks. This guide walks you through why classic cars fall outside standard underwriting, how to handle collateral and valuation issues, what down payment to expect, and which alternative financing paths actually work when your credit is less than perfect.
Why Classic Cars Fall Outside Standard Auto Loan Underwriting
Most auto loans are built around a simple formula: the vehicle is the collateral, and its value is easy to determine using industry guides like Kelley Blue Book or NADA. A 2018 Toyota Camry has a clear market value, a predictable depreciation curve, and a ready resale market. A 1965 Mustang does not. Standard underwriting models are not designed for vehicles that appreciate, sit in garages, or get driven fewer than 1,000 miles per year. When you add bad credit to the mix, the risk profile becomes too complex for mainstream lenders.
Banks and credit unions typically classify classic cars as specialty or collector vehicles. Their loan policies often exclude any car older than 10 years, and many draw a hard line at 15 or 20 years. A 25-year-old vehicle might qualify for a classic car loan through a specialty division, but that division will have its own credit score minimums, often 680 or higher. With a score below 600, you are outside the comfort zone of most traditional auto lenders, even those that advertise bad credit programs. The reason is simple: if the borrower defaults, the lender must repossess and sell a vehicle that may take months to move and whose value can swing wildly based on auction trends.
Another issue is that classic cars are often not daily drivers. Lenders worry that a borrower will treat the loan as a hobby expense and stop paying when money gets tight. Standard auto loans assume the car is essential for getting to work. Classic car financing with bad credit flips that assumption, and underwriters respond by tightening approval criteria or requiring larger down payments. Understanding this mindset is the first step toward finding a lender who sees the value in your project.
Collateral and Valuation Issues That Affect Approval
When a lender considers a classic car as collateral, they need to know what it is worth. Unlike a modern vehicle with a VIN that pulls up a clean history report, a classic car's value depends on condition, originality, documentation, and market demand. A numbers-matching 1970 Chevelle SS with original paint is worth far more than a restomod with a crate engine, even if both look similar in photos. Lenders do not have the expertise to evaluate these nuances in-house, so they rely on independent appraisals or collector vehicle valuation guides.
This appraisal requirement creates two problems for borrowers with bad credit. First, appraisals cost money, often $300 to $600, and that cost comes out of your pocket before you know whether you will be approved. Second, the lender will typically lend only a percentage of the appraised value, not the purchase price. If you are buying a car for $30,000 but the appraised value is $25,000, the lender will base the loan on the lower number. That means you need to cover the difference in cash, which increases your down payment.
Valuation guides like Hagerty or Classic.com can give you a ballpark, but lenders want a professional opinion. Some specialty lenders have their own appraisers or accept appraisals from certified professionals. If you are working with a private seller, you will need to arrange the appraisal yourself. If you are buying from a dealer that specializes in classics, they may have a relationship with a lender who understands the market. In either case, be prepared to document the car's condition, mileage, restoration history, and any upgrades. The more evidence you can provide that the car holds its value, the better your chances of approval.
Down Payment Expectations for Older Collectible Vehicles
Down payment requirements for classic car financing with bad credit are significantly higher than what you would see on a standard auto loan. Where a typical used car loan might require 10 percent down, a classic car loan with challenged credit can require 20 to 50 percent down. The exact number depends on the lender, the vehicle's appraised value, and your credit profile. If your score is below 550, expect to be at the higher end of that range.
Why so much? Because the lender needs a cushion in case the car's value drops or they have to repossess it. Classic car values can be volatile, and a lender who lends 90 percent of appraised value on a car that might sell for 70 percent at auction is taking a big risk. Your down payment reduces that risk. It also signals to the lender that you have skin in the game and are less likely to walk away from the loan.
Here is a quick breakdown of what you might expect based on credit tier:
- Score 600-679: 20-30 percent down, interest rates in the 8-12 percent range for specialty lenders.
- Score 550-599: 30-40 percent down, rates often 12-18 percent, and fewer lenders willing to work with you.
- Score below 550: 40-50 percent down, rates above 18 percent, or you may need to pursue alternative structures like personal loans or peer-to-peer lending.
These numbers are not set in stone. Some lenders specialize in classic car financing with bad credit and may offer more flexible terms, especially if the vehicle is highly desirable or you have a strong income and a long employment history. But in general, the worse your credit, the more cash you need upfront. If you cannot afford a large down payment, consider saving longer or looking for a less expensive project car that still fits your dream.
Alternative Structures: Personal Loans and Specialty Lenders
When traditional auto loans are not an option, you have to think beyond the bank. Two paths work for many enthusiasts with bad credit: personal loans and specialty lenders. Each has trade-offs, but both can get you behind the wheel of a classic car.
A personal loan is unsecured, meaning the lender does not use the car as collateral. That is a major advantage for classic car buyers because the lender does not care about the vehicle's age or appraised value. They care about your credit and income. If you have bad credit, personal loan rates will be high, often 15-30 percent, and loan amounts may be limited to $10,000 or $15,000. But for a lower-priced classic or a project car, a personal loan can be a practical bridge. You can also use a personal loan to cover the down payment on a specialty auto loan, though you should be careful not to overextend yourself.
Specialty lenders are the other option. These are companies that focus on collector cars, classic trucks, and exotics. They understand the market and are more willing to work with borrowers who have imperfect credit, provided the vehicle is desirable and the down payment is substantial. Some specialty lenders require a minimum credit score of 600, while others will go lower if the loan-to-value ratio is strong. You can find these lenders through classic car dealerships, collector car auctions, or online networks that connect borrowers with financing options. StartAutoLoan.com is one such platform: it connects consumers with a network of participating lenders and dealers who specialize in challenging credit situations, including bad credit and no credit. Submitting a request through their secure auto loan application takes minutes and can match you with lenders who understand classic vehicles. It is not a direct lender, but a connection service that can save you hours of searching.
Another structure worth considering is a home equity line of credit (HELOC) if you own property. HELOCs use your home as collateral, so the lender does not care about the car's age. Rates are often lower than personal loans, and you can borrow larger amounts. However, you are putting your home at risk, so this option requires discipline and a clear repayment plan. It is not right for everyone, but for a borrower with bad credit and significant home equity, it can be a viable path to classic car ownership. For more general guidance on overcoming financing obstacles, see our guide on guaranteed car financing options.
Steps to Improve Your Approval Odds Before You Apply
Before you start submitting applications, take a few weeks to strengthen your position. Lenders look at more than your credit score: they look at income stability, debt-to-income ratio, and the story your credit report tells. A few strategic moves can make the difference between a rejection and an approval.
- Pull your credit reports and fix errors. You are entitled to free reports from the three major bureaus. Look for accounts that are not yours, late payments that were reported incorrectly, or balances that are higher than they should be. Disputing errors can raise your score by 20-50 points in a matter of weeks.
- Save for a larger down payment. Every extra dollar you put down reduces the lender's risk and lowers your monthly payment. Aim for at least 30 percent of the purchase price, and more if your score is below 600.
- Get a pre-approval from a specialty lender. Pre-approval tells you exactly how much you can borrow and at what rate, so you can shop with confidence. It also signals to sellers that you are a serious buyer.
- Document the car's value. If you are buying from a private seller, arrange for an independent appraisal and gather receipts for any restoration work. A well-documented car is easier to finance.
- Consider a co-borrower. If you have a family member or friend with good credit who is willing to co-sign, your approval odds improve dramatically. Just be sure they understand the responsibility.
These steps take time, but they pay off. A borrower who walks into a specialty lender with a 550 score, a 40 percent down payment, and a clean credit report is in a much stronger position than one who applies on impulse with no preparation. Remember that classic car financing with bad credit is a process, not a single transaction. The more work you do upfront, the smoother the process will be. For borrowers who have faced bankruptcy, the same principles apply: rebuild your credit, save aggressively, and target lenders who explicitly work with post-bankruptcy borrowers. StartAutoLoan.com's network includes lenders who consider bankruptcies as part of a broader credit story, not an automatic disqualifier. You can learn more about their auto loan connection service and how it helps borrowers with challenged credit find options.
Understanding Interest Rates and Total Cost
Classic car financing with bad credit comes with higher interest rates than you would pay on a standard auto loan. That is simply the cost of risk. But the interest rate is only part of the picture. You also need to consider loan term, fees, and the total cost of ownership. A longer term lowers your monthly payment but increases the total interest you pay. A shorter term saves money but strains your budget. Finding the balance is key.
For example, a $30,000 loan at 15 percent interest over 60 months costs about $714 per month and $12,840 in total interest. The same loan over 36 months costs about $1,040 per month but only $7,440 in interest. If you can afford the higher payment, the shorter term is almost always the better financial choice. However, many borrowers with bad credit need the lower payment to make the numbers work. Be honest with yourself about what you can afford, and do not let the excitement of the purchase push you into a loan you will struggle to repay.
Also watch for fees. Specialty lenders may charge origination fees, appraisal fees, or documentation fees. These can add hundreds or thousands of dollars to the cost of the loan. Ask for a full breakdown of fees before you sign anything, and compare offers from multiple lenders. The difference between two offers can be significant, even if the interest rates look similar on the surface.
Insurance and Storage Costs You Must Budget For
Financing the car is only one piece of the puzzle. Classic car insurance is often more expensive than standard auto insurance, especially if you drive the car regularly. Collector car insurance policies are designed for vehicles that are driven infrequently and stored securely. They often have mileage limits and require proof of garaging. If you plan to drive your classic daily, you may need a specialty policy that costs more. Get quotes before you finalize your loan so you know the true monthly cost of ownership.
Storage is another consideration. Many lenders require classic cars to be stored in a garage or secure facility. If you do not have a garage, you may need to rent one, which adds to your monthly expenses. Some lenders also require you to carry comprehensive and collision coverage with a stated value, which can be more expensive than actual cash value coverage. These costs do not show up in the loan payment, but they affect your budget just the same. Factor them in before you commit.
Final Thoughts on Making It Work
Classic car financing with bad credit is not easy, but it is far from impossible. The key is to understand why lenders hesitate, address their concerns directly, and choose the right financing structure for your situation. Save for a substantial down payment, get a professional appraisal, and work with lenders who specialize in collector vehicles or alternative financing. Be patient, be prepared, and do not let a rejection from one lender stop you. The right financing partner is out there, and with the right approach, you can turn that dream car into a reality you can actually afford.