Auto Loans Near Me: How Local Dealer Financing Works
Local dealer financing can unlock approvals that banks miss. See how auto loans near me work and get matched with nearby lenders in minutes.
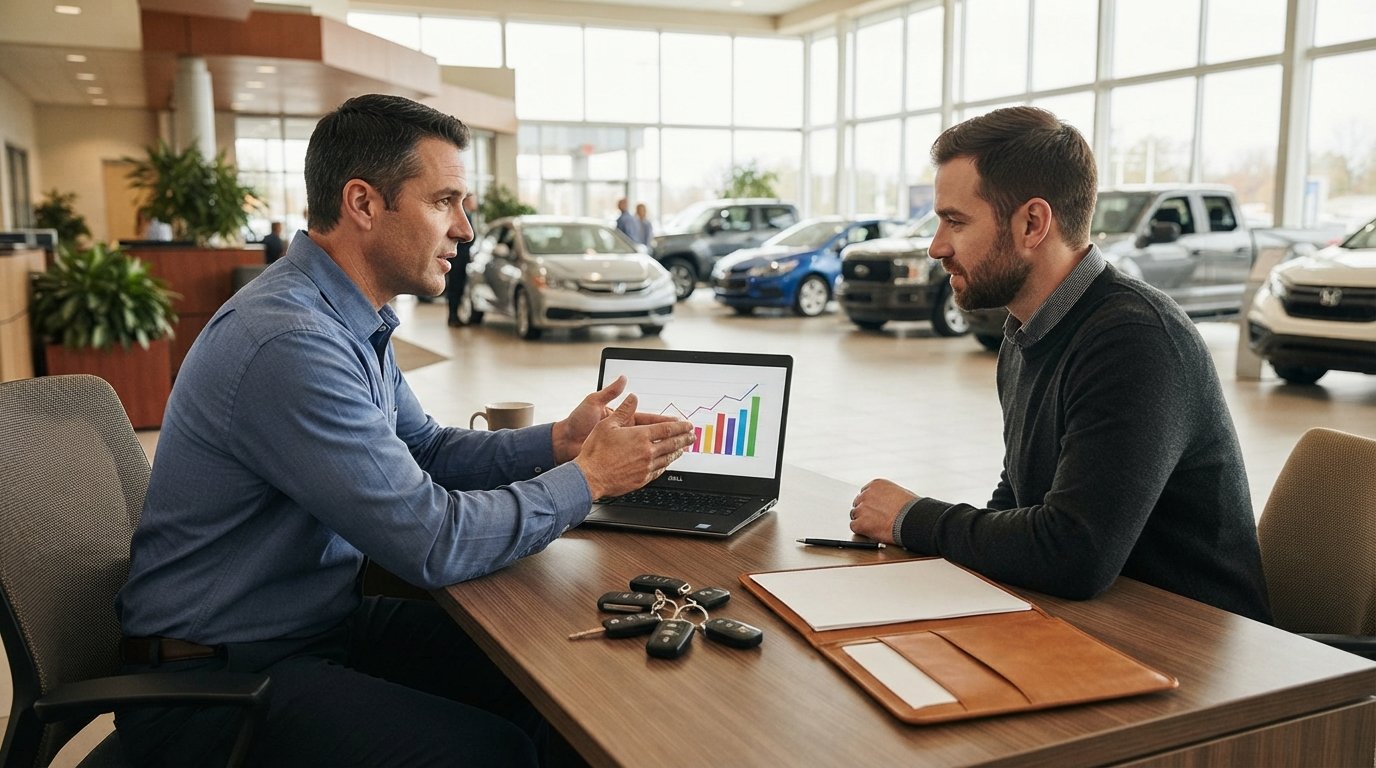
You need a car, and the financing piece feels like the hardest part. You have probably searched for auto loans near me and wondered why the results look different from what your bank offers. The answer often comes down to how local dealer financing works. Nearby dealerships do not just sell cars; they maintain relationships with a network of lenders, including many that specialize in less-than-perfect credit. Understanding this local ecosystem can save you time, money, and frustration.
Local dealer financing is not a single product. It is a process where a dealership submits your application to multiple lenders it works with, then presents you with the best available terms. That process is often faster and more flexible than applying directly to a bank, especially if your credit history has some dents. This guide breaks down exactly how the local piece fits into the auto loan puzzle, from why geography matters to what happens after you submit a request and how to compare offers without wasting hours.
Why Local Dealerships Often Have More Lending Options
When you walk into a bank or credit union, you are dealing with one institution and one set of underwriting rules. That institution might be conservative, especially for borrowers with bad credit, no credit, or a past bankruptcy. Local dealerships operate differently. They are in the business of moving inventory, so they build relationships with a wide range of lenders: national banks, regional credit unions, captive finance companies, and subprime lenders that specifically work through dealers.
That diversity matters. A local dealer near you may have relationships with lenders that do not advertise directly to consumers. These lenders rely on dealerships to originate loans because the dealer can verify the vehicle, inspect the paperwork, and handle the title work. For a borrower with a checkered credit history, that channel can be the difference between an approval and another rejection. Local dealers also see credit profiles from their specific community every day, so they often know which lenders are most likely to approve a given situation.
Geography amplifies this advantage. Lenders vary by state and region because of licensing, title laws, and local market conditions. A lender that is aggressive in one state might not operate in another. A nearby dealer knows which lenders are active in your area and which ones have competitive programs for your credit tier. That local knowledge is hard to replicate online, and it is why searching for auto loans near me often leads to dealer financing options that outperform a generic national quote.
What Happens After Your Request Is Matched with a Nearby Dealer
If you submit a financing request through a connection service like StartAutoLoan.com, the platform matches your information with participating dealers or lenders in your area. The key word is "participating." These are not random dealerships; they are partners who have agreed to work with the platform and who understand that applicants may have credit challenges. Once your request is submitted, the matching process typically moves quickly.
Here is what the sequence usually looks like from the moment you hit submit:
- Application review and matching. Your basic information (vehicle preference, income, credit situation) is reviewed and matched with a nearby participating dealer or lender whose programs fit your profile.
- Initial contact. A representative from the matched dealership or lending partner reaches out, often within minutes to a few hours, to confirm details and explain next steps.
- Document collection. You provide proof of income, identity, insurance, and any other required documents so the dealer can submit a complete package to lenders.
- Lender submissions and offers. The dealer submits your application to multiple lenders it works with, then collects the offers and terms.
- Offer presentation and vehicle selection. You review the offers, choose a vehicle from the dealer's inventory (or a vehicle the dealer can locate), and finalize the paperwork.
Speed is a real benefit here. Traditional bank applications can take days, and online-only lenders may not handle title work or vehicle verification. A local dealer handles those steps in-house, which is why some applicants hear back within 24 hours. If you want to understand how to prepare before this process begins, our guide on auto loan pre approval explains how a preapproval can strengthen your position and streamline the dealer's work.
How Geography Affects Lenders, Rates, and Vehicle Inventory
Where you live shapes your financing options more than most people realize. Lenders must be licensed to do business in your state, and some specialize in certain regions. A credit union in your city might offer excellent rates for members, while a national subprime lender might operate in your state but not the next one over. Local dealers know these licensing and program boundaries because they work within them daily.
Rates also vary by geography. Urban areas with more dealership competition tend to have more lender options, which can create pressure to offer competitive terms. Rural areas may have fewer participating dealers, but those dealers often have deeper relationships with regional lenders who understand the local economy. Vehicle inventory is another geographic factor: the types of cars available near you (trucks in one region, compact cars in another) influence which vehicles lenders will finance and at what loan-to-value ratios.
This is why a national online quote can be misleading. It might not account for local lender availability or state-specific fees. A nearby dealer, by contrast, can tell you which lenders are actually active in your area and what terms are realistic. If you have been rejected elsewhere, a connection service can match you with local partners who work with borrowers in your situation. Platforms like AutoTitleLoan also connect consumers with financing options, and the broader lesson is the same: local access to the right lenders matters.
Questions to Ask a Local Dealer About Their Lender Network
Not all dealer financing is created equal. Some dealerships work with a broad lender network and will shop your application around; others rely on a single finance company and may not get you the best terms. Before you commit, ask direct questions. A reputable dealer will answer them without hesitation.
Here are the questions that matter most:
- Which lenders do you work with for my credit tier? You want to hear specific names or categories (subprime, credit union, captive) rather than a vague "we work with everyone."
- Do you submit to multiple lenders or just one? Multiple submissions increase your chances of a competitive offer, but they also mean multiple credit inquiries, so ask how they manage that.
- What fees are included in the financing? Dealer documentation fees, title fees, and add-ons can change the total cost. Ask for a breakdown in writing.
- Can I bring my own financing? Some dealers prefer their network, but you should know whether an outside preapproval is accepted.
- What happens if I am not approved? A good dealer will explain alternatives, such as a co-signer, a larger down payment, or a different vehicle.
These questions also protect you. If a dealer is evasive about which lenders they use or pushes you toward a single high-rate offer without explanation, that is a signal to slow down. The goal is a financing package that fits your budget, not just an approval at any cost.
Keeping the Process Efficient When Contacting Several Local Options
You might be tempted to contact every dealership within driving distance. That approach can backfire. Each application can trigger a credit inquiry, and too many inquiries in a short window can look risky to lenders. A smarter strategy is to narrow your list before you apply.
Start by identifying three to five local dealers or lending partners that explicitly work with your credit situation. Connection services can help with this step by matching you with participating dealers who are more likely to approve your profile. Once you have a shortlist, prepare a single set of documents (income proof, ID, insurance, references) so you can move quickly when a dealer requests them. Ask each dealer whether they will shop your application to multiple lenders and how they handle credit inquiries. Finally, compare offers side by side: look at the APR, the term length, the total cost of financing, and any fees. The lowest monthly payment is not always the best deal if the term is stretched out or the fees are high.
Efficiency also means knowing when to stop. If you receive a reasonable offer from a dealer you trust, taking it can be better than chasing a marginally lower rate across town. The time and credit impact of additional applications often outweigh small savings. For borrowers with bad credit or no credit history, the priority is a reliable approval with transparent terms, not a perfect rate.
Local dealer financing works because it combines access, speed, and knowledge of your area. When you search for auto loans near me, you are really looking for a partner who knows which lenders will say yes and what terms are realistic. StartAutoLoan.com is a connection service that matches you with participating dealers and lenders in your area, including those who work with bad credit, no credit, and past bankruptcies. You submit one request, get matched with local options, and compare offers without obligation. If you have been rejected before, that local network can be the path to a yes.