Auto Loan Requirements for International Students and New Immigrants
Auto loan requirements for international students and new immigrants explained, including accepted IDs, proof of income, and how to get approved with no U.S. credit.
By Olivia Ramirez
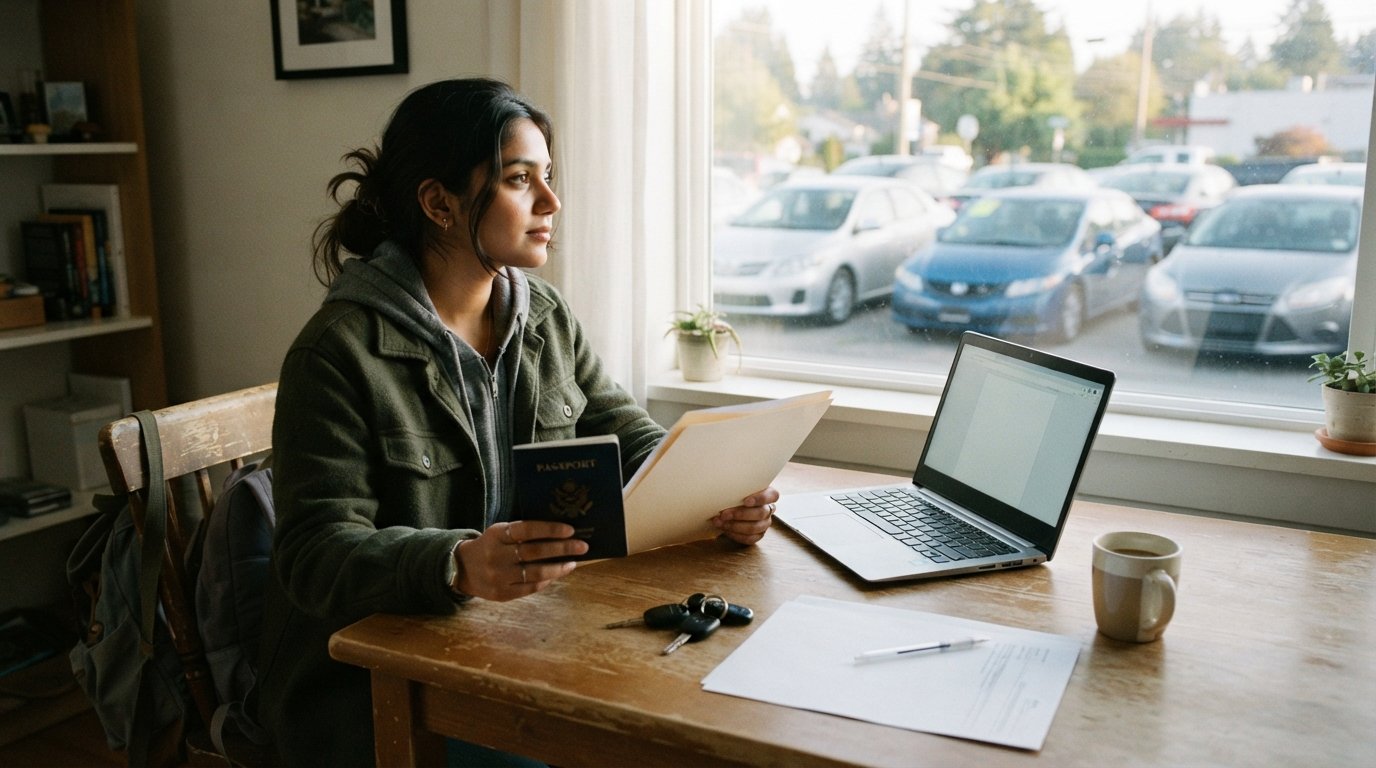
You just landed in the United States with a student visa, a work permit, or a green card in hand. You have a job offer, a university acceptance letter, or a fresh start waiting for you. Then you realize something simple and frustrating: you need a car to get to class, work, or the grocery store, but every lender you contact asks for a U.S. credit score you do not have yet. This situation stops thousands of international students and new immigrants every year, but it is not a dead end. Understanding the specific auto loan requirements for international students and new immigrants turns a confusing process into a manageable checklist, and it helps you find lenders who actually want your business instead of rejecting you at the first application screen.
Why Your Home Country Credit History Does Not Transfer
Credit reporting systems operate on a country by country basis. A perfect payment record with a bank in India, Brazil, Nigeria, or the Philippines means nothing to Equifax, Experian, or TransUnion because those bureaus have no data sharing agreement with foreign credit agencies. When a U.S. lender pulls your credit file, it sees a blank slate, often called a thin file or a no file. This does not mean you are a risky borrower. It means the lender cannot measure your risk using its usual tools, so it either declines your application automatically or offers you a higher interest rate to compensate for the uncertainty.
Some lenders have started accepting international credit reports as supporting documentation, but this remains rare and usually applies only to premium credit cards or specific bank programs, not mainstream auto financing. For a car loan, you should expect to build your case from scratch using income, residency status, and a down payment rather than a credit score. The good news is that many lenders in the subprime and near prime space specialize in exactly this scenario, and they evaluate applicants on a broader set of criteria than just a FICO number.
Accepted Identification and Documentation for International Applicants
When you apply for an auto loan without a U.S. credit history, the lender will ask for a different set of documents to verify who you are and whether you can repay. Requirements vary by lender, but most will accept a combination of the following items. Gathering these before you shop for a car speeds up the process and shows lenders you are organized and serious.
- Passport: Your home country passport serves as primary identification for most lenders, especially if you do not yet have a state issued driver license or ID card.
- Visa or immigration documents: F-1, J-1, H-1B, L-1, green card, or employment authorization documents help lenders confirm your legal status and how long you are likely to remain in the country.
- ITIN or SSN: An Individual Taxpayer Identification Number works for some lenders, but a Social Security Number opens more doors because it allows the lender to pull any existing U.S. credit file and report your new loan payments.
- Proof of income: Pay stubs, an offer letter, bank statements showing consistent deposits, scholarship documentation, or a letter from your employer or university confirming your stipend or wages.
- Proof of address: A utility bill, lease agreement, or university housing letter that matches the address on your application.
Some lenders will also ask for a reference or co-signer who is a U.S. citizen or permanent resident with established credit. A co-signer is not required for every loan, but it can dramatically improve your chances of approval and lower your interest rate. If you have a family member, a close friend, or even an employer willing to co-sign, that single document can turn a rejection into an approval. Before you apply, ask each lender directly which of these documents they accept, because some banks are stricter than others about ITIN only applications or about visas that expire within a year.
How International Student Status Affects Lender Risk Models
Lenders look at international students differently than they look at permanent residents or U.S. citizens, and the reason is not personal. It is mathematical. A student visa is temporary by design. A lender's risk model asks a simple question: if this borrower stops paying, can we collect? For a student who may leave the country after graduation, collection becomes difficult or impossible. That uncertainty translates into either a higher interest rate, a requirement for a larger down payment, or an outright denial from conservative banks.
Students who can demonstrate strong ties to the United States, such as a job offer after graduation, a spouse with work authorization, or a long term lease, present a lower risk profile. So do students who make a substantial down payment, because the lender has less money at risk if the loan goes bad. If you are an F-1 or J-1 student, expect to put down 20 to 30 percent of the vehicle price, or to bring a co-signer, or both. The same logic applies to new immigrants on temporary work visas. A green card holder, by contrast, has permanent residency and usually faces fewer restrictions, though a thin U.S. credit file still limits the best advertised rates.
One practical workaround is to apply through a dealer network rather than a traditional bank. Dealers work with multiple lenders, including finance companies that specialize in thin file and no file borrowers. They can submit your application to several lenders at once and find the one most comfortable with your specific immigration status. This is where a connection service like StartAutoLoan.com becomes useful. Instead of visiting five banks and filling out five applications, you submit one request and let participating dealers and lenders compete for your business. You can explore new car loans and financing options made simple to see how that matching process works in practice.
Dealer Networks Versus Banks for Thin File Applicants
Banks and credit unions tend to have rigid underwriting boxes. If your credit file is empty, you fall outside the box, and the application gets declined regardless of your income or down payment. Dealer networks operate differently. They maintain relationships with a wide range of lenders, from major banks to subprime finance companies, and they know which lender approves which profile. A dealer who works with international students every day knows which finance company accepts an ITIN, which one wants a co-signer, and which one will approve a J-1 visa holder with six months of pay stubs.
That said, not all dealer financing is equal. Some dealers mark up the interest rate to increase their profit, and some push add-ons like extended warranties and gap insurance that you may not need. Your best protection is to get preapproved through a connection service before you set foot in a dealership. A preapproval letter tells you the maximum amount you can borrow and the rate you qualify for, which gives you negotiating power and prevents the dealer from steering you into a worse loan. If you have bad credit or no credit, a platform that specializes in connecting applicants with lenders who accept thin files is far more productive than applying directly to a bank that will reject you in seconds.
Another option worth considering is a credit union, especially one that serves a university or a specific immigrant community. Some credit unions offer newcomer loan programs that accept foreign credit history, a work visa, and a letter from your employer. These programs are not advertised widely, so you may need to call and ask. The rate is often better than what a subprime dealer lender offers, but the approval process takes longer and requires more documentation. If you have time before you need the car, this route can save you hundreds of dollars over the life of the loan.
Steps to Build U.S. Credit Alongside Your First Auto Loan
An auto loan is one of the most effective tools for building a U.S. credit history because it reports to all three bureaus every month. A single year of on time car payments can move you from no file to a score in the low 700s, which unlocks better rates on your next loan, a credit card, or even an apartment rental. The key is to treat the loan as a credit building opportunity, not just a way to buy a car. Here is a simple framework that international students and new immigrants can follow.
- Apply for a secured credit card at the same time as your auto loan. A secured card requires a cash deposit, usually 200 to 500 dollars, and reports to the bureaus just like a regular card. Use it for small purchases and pay the balance in full every month.
- Make every auto loan payment at least five days early. Payment history is the single largest factor in your credit score, and a single 30 day late payment can drop your score by 50 to 100 points.
- Keep your credit utilization below 30 percent. If your secured card has a 500 dollar limit, try not to carry a balance above 150 dollars at the end of each statement period.
- Ask a family member to add you as an authorized user. If a trusted relative or friend has a U.S. credit card with a long history and perfect payments, being added as an authorized user can give your file an immediate boost.
- Check your credit reports every four months. You are entitled to free reports from each bureau, and reviewing them helps you catch errors or fraudulent accounts before they damage your progress.
After 12 to 18 months of consistent payments, you can refinance your auto loan at a lower rate. Refinancing replaces your original loan with a new one, ideally at a lower interest rate and sometimes with a lower monthly payment. For international students and new immigrants, refinancing is the reward for building credit, and it can save you thousands of dollars compared to the subprime rate you accepted on day one. Many lenders that would have declined you as a no file applicant will eagerly approve you once you have a year of auto loan history on your report.
One more piece of the financial puzzle deserves attention: auto insurance. Lenders require you to carry full coverage, and for a new immigrant with no U.S. driving history, insurance premiums can be surprisingly high. Before you finalize your car purchase, spend an hour comparing quotes from multiple carriers. A service like FreeAutoInsuranceQuotesOnline lets you request free, no obligation quotes from several insurers so you can see how much coverage will cost before you commit to a loan. Bundling your auto insurance with renters insurance, or choosing a higher deductible, can lower the premium enough to offset a portion of your car payment. Lenders do not usually verify your insurance until after the loan is approved, but driving without it violates your loan agreement and can lead to repossession, so treat insurance shopping as part of the auto loan process rather than an afterthought.
Putting the Pieces Together
Securing a car loan as an international student or new immigrant requires more preparation than it does for a lifelong U.S. resident, but the path is well worn. Gather your passport, visa, ITIN or SSN, proof of income, and proof of address before you apply. Expect to make a larger down payment or to add a co-signer if your immigration status is temporary. Apply through a dealer network or a connection service that works with thin file borrowers rather than walking into a bank that will reject you automatically. Then use the loan itself to build the U.S. credit history that makes your next financing experience easier, cheaper, and faster. The first loan is the hardest one. Every loan after that gets simpler.