What to Bring to Dealership for First Car Purchase: Checklist
Know exactly what to bring to dealership for first car purchase. This checklist covers ID, income proof, insurance, down payment, and key questions to ask.
By Marcus Hayes
You have done the research, picked a few models, and maybe even gotten preapproved for financing. Now comes the moment you walk into the dealership. For a first-time buyer, that visit can feel like a high-stakes exam. One missing document can stall the entire process, turn a two-hour visit into an all-day affair, or even cost you the deal. Knowing exactly what to bring to the dealership for your first car purchase removes the guesswork and lets you focus on the vehicle and the terms, not on scrambling for paperwork.
This guide covers every document, item, and question you need to have ready. Whether you are financing through a lender or using dealer financing, having the right materials on hand speeds up approval and gives you more negotiating leverage. For a broader walkthrough of the entire buying process, including how to handle trade-ins and financing conversations, see our first time buyer dealership checklist. Here, we go deep on the specific items to bring and why each one matters.
Essential Identification and Personal Documents
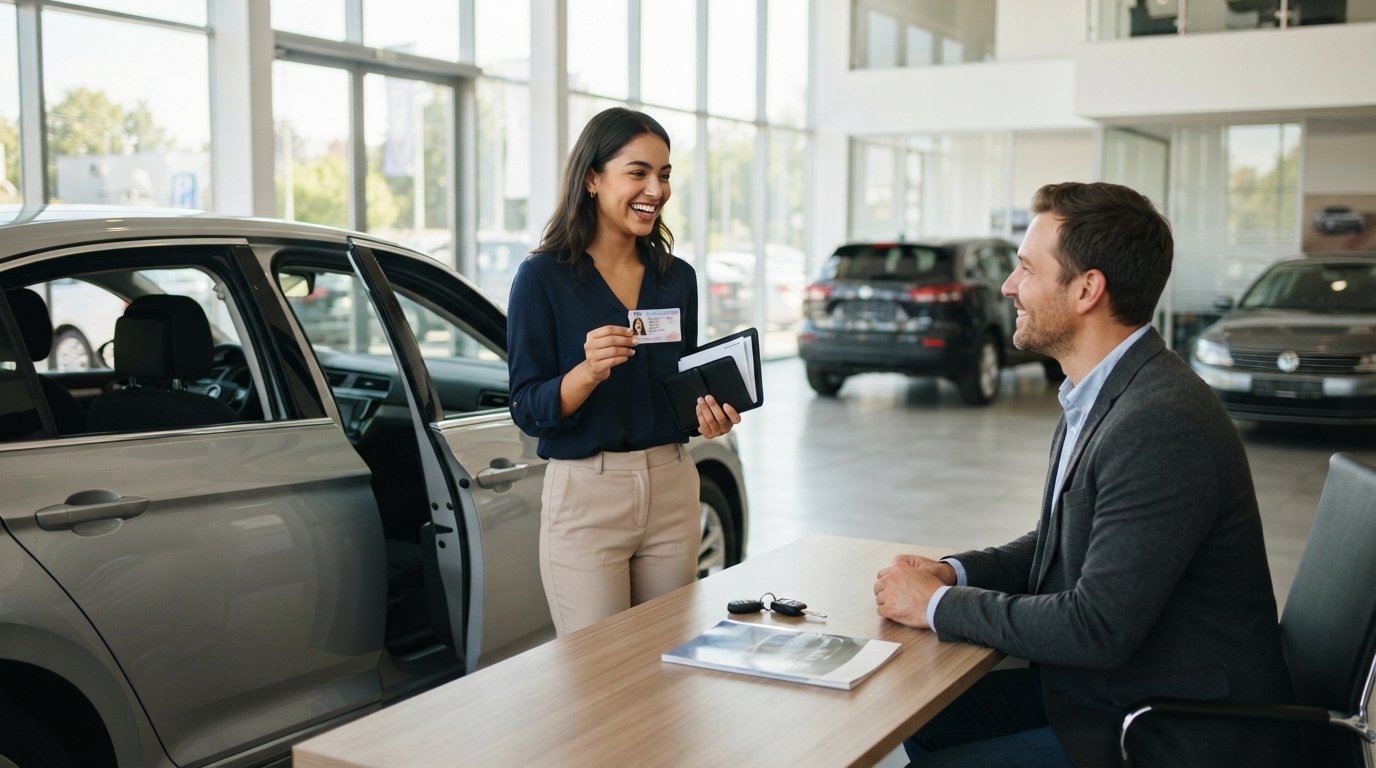
Every dealership will ask for identification before they let you test drive or discuss financing. For a first-time buyer, the standard requirement is a valid, unexpired driver's license. Some states also accept a state-issued ID, but if you plan to drive the car home, you need a license. Bring your actual physical license, not just a photo on your phone; many dealerships are required to make a copy for their records.
In addition to your license, bring your Social Security number. You do not necessarily need the physical card, but you will need to provide the number for credit checks and loan applications. If you are a first-time buyer with no credit history, the dealership may ask for additional proof of identity, such as a passport or a utility bill showing your current address. Having these on hand prevents delays if the finance office requests them.
Proof of address is another common requirement. A recent utility bill, bank statement, or lease agreement (within the last 30 to 60 days) usually works. Some dealerships accept a voter registration card. This is especially important if your driver's license address does not match your current residence. Keep in mind that if you are working with an online connection service like AutoTitleLoan to find financing, the lender may request the same documents, so having them ready in advance simplifies the process.
Proof of Income and Employment
Lenders need to know you can repay the loan. For a first car purchase, proof of income is non-negotiable if you are financing any part of the vehicle. The most recent two pay stubs are typically sufficient for salaried employees. If you are paid biweekly, bring the last two; if weekly, bring the last four. These should show your year-to-date earnings and deductions.
If you are self-employed, a gig worker, or paid in cash, you will need alternative documentation. Common options include:
- Bank statements from the last three to six months showing regular deposits
- Tax returns from the past two years (filed and signed)
- A letter from your employer on company letterhead stating your position and salary
- 1099 forms or profit-and-loss statements if you run your own business
Having these documents organized in a folder shows the finance manager that you are serious and prepared. It also reduces the chance of a lender asking for follow-up paperwork after you have already agreed on a price. If you have a gap in employment, be ready to explain it briefly and provide additional proof of income stability, such as a recent bank statement showing savings.
For buyers with bad credit or no credit history, some lenders may ask for a co-signer. If you plan to use a co-signer, bring that person's identification, proof of income, and proof of address as well. StartAutoLoan.com connects buyers with lenders who specialize in these situations, so if you are worried about approval, you can submit a secure application before you visit the dealership and know which lenders are likely to work with you.
Insurance Information and Down Payment
You cannot drive a new car off the lot without proof of insurance. Most states require at least liability coverage, and if you are financing, the lender will require comprehensive and collision coverage. Before you go to the dealership, contact your insurance agent or company and get a binder or proof of insurance for the specific vehicle you plan to buy. If you do not have an insurance provider yet, get quotes online or call a few agencies. Having an insurance card or a digital copy on your phone is usually acceptable, but a printed copy is safer.
Your down payment is another critical item. Dealerships accept various forms of payment, but not all are treated equally. Cash is accepted but often discouraged for large amounts due to security and anti-money-laundering policies. A cashier's check from your bank is the most widely accepted form of a large down payment. Personal checks may be accepted, but some dealerships require a credit check or a waiting period for clearance. Debit cards and credit cards are often accepted for smaller amounts, but many dealerships cap credit card payments at a few thousand dollars. Bring your checkbook and a debit card as backup.
If you are planning to use a manufacturer rebate or a loyalty incentive, bring any necessary proof, such as a current vehicle registration for a loyalty rebate or a military ID for military appreciation programs. These small details can save you hundreds of dollars.
Financing Documents and Preapproval
If you have already secured financing through a bank, credit union, or online lender, bring your preapproval letter. This letter states the maximum amount you are approved to borrow and the terms. Having it in hand gives you confidence and can speed up the dealership's finance process. It also signals to the salesperson that you are a serious buyer who has done their homework.
If you are using dealer financing, bring the same income and identification documents mentioned above. The finance manager will use them to submit your application to lenders. Be prepared to discuss your credit situation honestly. If you have bad credit or no credit, you may want to apply through a connection service like StartAutoLoan.com before visiting the dealership. Their platform matches you with lenders who are more likely to approve first-time buyers and those with challenging credit, and you can get approved in as little as 24 hours. This pre-qualification can give you a realistic budget and reduce pressure at the dealership.
Also bring any documents related to a trade-in if you have one. The title (if you own the car outright), the registration, and the loan payoff information (if you still owe money) are essential. The dealership will need these to appraise your trade and pay off the existing loan.
Questions to Ask and Items to Inspect
Beyond paperwork, your first visit to the dealership is your opportunity to gather information and inspect the vehicle. Bring a notebook or use your phone to take notes. Write down the answers to key questions so you can compare offers later. Important questions include:
- What is the out-the-door price, including taxes, fees, and add-ons?
- What is the interest rate and loan term being offered?
- Are there any prepayment penalties or fees for paying off the loan early?
- What warranty coverage is included, and what does it cost to extend it?
- Can I see the vehicle history report (e.g., Carfax)?
During the test drive, inspect the car thoroughly. Check the tire tread, look for scratches or dents, test all electronics (windows, radio, air conditioning, lights), and ask for a walk-around with the salesperson. If the car is used, ask for the maintenance records. Do not feel rushed; a thorough inspection can reveal issues that might affect your decision or give you negotiating room.
Finally, bring a friend or family member if possible. A second set of eyes and ears can help you catch details you might miss and provide a sanity check on the deal.
Organizing Your Documents for a Smooth Visit
The night before you go, assemble everything in one folder. A simple checklist helps:
- Driver's license and Social Security number
- Proof of income (pay stubs, tax returns, or bank statements)
- Proof of address (utility bill or lease agreement)
- Insurance card or binder
- Down payment (cashier's check or debit card)
- Preapproval letter (if applicable)
- Trade-in documents (title, registration, payoff info)
Having these items in a folder not only makes you look organized but also reduces the chance of forgetting something critical. It also allows the finance manager to work more efficiently, which can work in your favor when negotiating.
Remember that each dealership may have slightly different requirements, so it is smart to call ahead and ask what they need for a first-time buyer. A quick phone call can save you a trip.
Walking into a dealership for your first car purchase does not have to be stressful. With the right documents, a clear budget, and a list of questions, you are in control of the process. Start by gathering your identification, income proof, insurance, and down payment. If you need help finding financing that fits your credit situation, consider using StartAutoLoan.com to connect with lenders who understand first-time buyers. Being prepared is the best way to get a fair deal and drive home with confidence.