What to Bring to the Dealership: First Time Buyer Checklist
Bring the right documents, numbers, and mindset to your first dealership visit. This first time car buyer checklist helps you avoid surprises and secure fair financing.
By Eric Sullivan
Walking into a dealership for the first time as a buyer can feel like stepping onto a stage without a script. The lights are bright, the salespeople are friendly, and somewhere in the back of your mind a voice asks: did I remember everything I need? For first time car buyers, the difference between a smooth deal and a stressful one often comes down to preparation. Knowing exactly what to bring to the dealership first time car buyer checklist style removes guesswork, protects your credit, and gives you real negotiating power before you ever sit down at the finance desk.
This guide walks through the documents, numbers, and mindset you should have in hand. It also explains how each item fits into the financing process, especially if you have bad credit, no credit history, or a past bankruptcy. StartAutoLoan.com connects buyers in exactly those situations with a network of participating lenders and dealers, so the checklist below is built for real world first time buyer financing, not just ideal credit scenarios.
Why a First Time Buyer Checklist Matters Before You Arrive
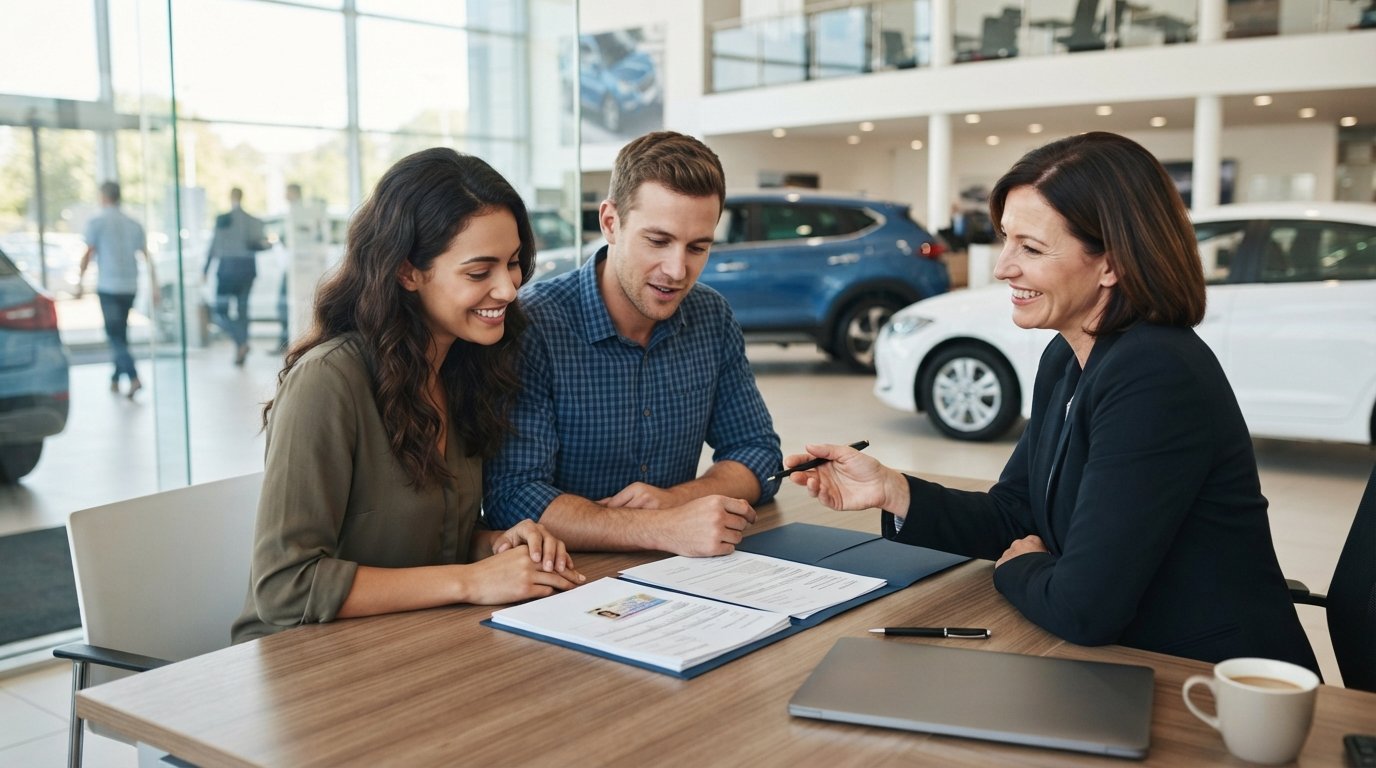
Dealerships move fast. A salesperson may ask for your driver's license within minutes, and the finance manager will want proof of income before discussing rates. If you arrive without these items, you may be asked to come back later, which gives the dealer more time to reset the conversation on their terms. Worse, missing documents can push you toward whatever financing the dealership offers on the spot, even if a better option exists elsewhere.
A prepared buyer changes the dynamic. When you walk in with a folder of documents and a clear budget, you signal that you have done your homework. That alone can improve how you are treated and how seriously your counteroffers are taken. Preparation also shortens the process: financing can move from application to approval in as little as 24 hours when your paperwork is complete, and some buyers hear from a dealer in as little as 10 minutes after submitting a request online.
Think of your checklist as two layers. The first layer is identity and financial documents the dealer and lender legally need. The second layer is your personal research: budget numbers, insurance quotes, and financing offers you have already gathered. Both layers matter, and skipping the second one is where many first time buyers lose money.
Essential Documents to Bring to the Dealership
Every dealership will ask for a core set of documents, though the exact list can vary by state and lender. Having these ready in a physical folder, plus digital copies on your phone, keeps the process moving. If you are applying through a connection service like StartAutoLoan.com, the same documents support your application with participating lenders, so you are not starting from zero at the dealership.
Here is the core paperwork most dealerships and lenders request from first time buyers:
- Valid driver's license or state ID: Required for test drives, credit checks, and the final contract.
- Proof of income: Recent pay stubs (usually the last two or three), bank statements, or tax returns if you are self employed.
- Proof of residence: A utility bill, lease agreement, or recent bank statement showing your current address.
- Proof of insurance: Many states require coverage before you drive off the lot, so bring your policy information or a binder from your insurer.
- References and contact information: Some lenders, especially those working with challenged credit, ask for personal or professional references.
Beyond the basics, there are situational documents that matter for specific buyers. If you have declared bankruptcy in the past, bring your discharge papers; lenders will want to see the case is resolved. If you have a co-signer, that person should bring their own ID, proof of income, and proof of residence, and in many cases they need to be present for signing. If you are trading in a vehicle, bring the title or lienholder information, the registration, and both sets of keys.
One more item that is easy to forget: a down payment. Dealerships accept cashier's checks, debit cards, and sometimes personal checks, but the exact method matters. Ask ahead of time what forms of payment the dealership accepts for a down payment so you are not scrambling at the finance desk. Even a modest down payment can reduce your monthly obligation and improve your approval odds with lenders who view skin in the game favorably.
Financial Numbers to Calculate Before You Go
Documents get you through the door; numbers keep you from overpaying once you are inside. Before visiting any dealership, calculate three figures: your maximum monthly payment, your total loan amount, and your down payment. These numbers should come from your actual budget, not from what a salesperson suggests you can afford.
A common guideline is to keep total vehicle costs, including the payment, insurance, fuel, and maintenance, under 15 to 20 percent of your monthly take home pay. If that feels tight, consider a less expensive vehicle or a larger down payment. Remember that the loan term matters too: stretching a loan to 72 or 84 months lowers the monthly payment but increases the total interest you pay and can leave you owing more than the car is worth.
It also helps to arrive with a preapproval or at least a rate range in hand. A preapproval from a bank, credit union, or online connection service tells you what interest rate you qualify for and how much you can borrow. With that number, you can compare dealership financing against your outside offer instead of guessing. If you have bad credit or no credit history, preapproval conversations may feel discouraging at traditional banks, which is why services that work with a broader lender network can be more productive. For buyers exploring credit union options specifically, our guide to the best credit unions for first time car buyers explains how to compare membership requirements and rates before you apply.
Bring a printed or digital copy of your budget and any preapproval letters. Having these visible during negotiation keeps the conversation anchored to facts. When a finance manager presents a monthly payment that exceeds your ceiling, you can politely redirect: your numbers say otherwise, and you are prepared to walk away if needed.
Financing Preparation for Bad Credit and First Time Buyers
First time buyers with thin or damaged credit often assume the dealership is their only option. That assumption can cost thousands over the life of a loan. The truth is that many lenders specialize in bad credit auto loans, no credit auto loans, and financing after bankruptcy. The key is to approach them prepared rather than desperate.
Before you visit the dealership, gather the documents that speak to your financial stability: proof of steady income, proof of residence, and any evidence of on time payments such as utility or phone bills. These do not replace a credit score, but they help a lender see a complete picture. If you have a co-signer with stronger credit, bringing them along (with their documents) can dramatically improve your terms.
It also pays to understand how dealership financing works. Dealers often work with multiple lenders and can submit your application to several at once, but they may also mark up the interest rate to earn a reserve. Arriving with an outside offer gives you a benchmark. If the dealership can beat it, great; if not, you have a fallback. Platforms that connect buyers with a nationwide network of lending partners can be especially useful here, because they let you request offers from multiple sources without driving from lot to lot.
Finally, do not let urgency push you into a bad deal. If the numbers do not work, you can pause, review your options, and return another day. Dealerships want to sell cars, and a prepared buyer who is willing to walk away often gets a better offer than one who signs on the spot out of exhaustion.
Insurance, Trade Ins, and Other Practical Items
Insurance is one of the most overlooked items on a first time buyer checklist. In most states, you cannot legally drive a new car off the lot without proof of coverage. Contact your insurance company before you go shopping and ask for a quote on the specific vehicles you plan to test drive. If you do not yet have a policy, get a binder or at least a written quote you can present. Some dealerships will not release the car until coverage is verified, so this step prevents a last minute delay.
If you are trading in a vehicle, bring everything related to it: the title or lien release, current registration, both sets of keys, and any service records that show you maintained it. A clean, documented trade in is easier to appraise and can strengthen your negotiating position. Be honest about any mechanical issues; undisclosed problems can unravel a deal after the fact.
Other practical items worth packing include a phone charger, a folder for paperwork, a pen, and a bottle of water. Dealership visits can take hours, and staying comfortable helps you stay sharp. If you are bringing a co-signer or a trusted advisor, coordinate schedules so they can be present for the entire negotiation and signing process.
For buyers who want to explore refinancing options later, it helps to know the landscape in advance. Educational resources such as CarLoanRefinancing.com offer guides, rate comparisons, and calculators that can help you evaluate whether refinancing makes sense down the road. Understanding that option now can reduce pressure during the initial purchase, because you know you are not locked into a bad rate forever.
How to Use Your Checklist at the Dealership
Arriving prepared is only half the battle; using your preparation well is the other half. When you sit down with a salesperson, start by stating your budget and your needs clearly. Mention that you have financing options already and that you are comparing offers. This sets a professional tone and signals that you are not an easy mark for high pressure tactics.
As you move to the finance office, keep your documents organized and ask for a full breakdown of every fee. Dealerships may charge documentation fees, preparation fees, and other add ons. You are allowed to question these charges and, in many cases, negotiate them. If something does not make sense, ask for it in writing. A reputable dealer will explain each line item without hesitation.
Before signing anything, read the contract carefully. Confirm the interest rate, the loan term, the monthly payment, and the total amount financed. Check that the vehicle identification number on the contract matches the car you are buying. If you have a preapproval from an outside lender, make sure the dealership is not quietly switching you to a different loan with worse terms.
Finally, remember that you are allowed to take your time. A first car purchase is a major financial decision, and no legitimate dealership should rush you into signing. If you feel pressured, step outside, call a trusted friend or family member, and review your numbers. Your checklist exists to protect you, so use it as a shield against impulse decisions.
With the right documents, a clear budget, and a calm approach, your first dealership visit can be a positive milestone rather than a source of stress. Prepare your folder, run your numbers, and walk in knowing you have done everything you can to secure a fair deal.