Buying a Car with a Co Buyer Who Has Bad Credit
A co buyer with bad credit can help you get approved, but both parties share full liability. Here is how to structure the deal and protect your credit.
By Ashley Carter
Adding a second person to your auto loan can feel like a lifeline when your own credit profile is holding you back. Maybe you have a thin credit file, a past bankruptcy, or a score that lenders just do not like. A co buyer might seem like the obvious fix, but the arrangement carries more nuance than most people realize. The second person is not just a signature on a form. They become a legal owner of the vehicle, they share responsibility for the debt, and their financial life becomes intertwined with yours for the life of the loan. Understanding exactly how that relationship works, how lenders evaluate both parties, and what happens when payments stop is essential before you walk into a dealership or submit an online application.
This guide breaks down the mechanics of buying a car with a co buyer who has bad credit. It covers the difference between a co buyer and a cosigner, how underwriting weighs a weak credit profile when a stronger one is present, the consequences of missed payments for both parties, and the practical steps you can take to protect both your credit and your relationship. Whether you are the buyer with challenged credit or the person being asked to co-sign, the details below will help you make a decision that does not come back to haunt you.
Co Buyer vs. Cosigner: The Difference That Changes Everything
People often use the terms co buyer and cosigner interchangeably, but they describe two very different legal arrangements. A cosigner signs the loan contract and promises to repay the debt if the primary borrower does not, but the cosigner typically does not appear on the vehicle title. A co buyer, by contrast, is listed on both the loan and the title. That means the co buyer has an ownership stake in the car, not just a financial guarantee. This distinction matters enormously when you are buying a car with a co buyer who has bad credit, because the person with the weaker profile may end up on the title even though the stronger party is carrying most of the credit risk.
When a co buyer is on the title, both parties are legal owners. Either one can generally use the vehicle, and in many states either one can sell it only with the other's consent (though rules vary). If the relationship sours, sorting out who keeps the car and who pays for it becomes a legal matter, not just a financial one. A cosigner, on the other hand, has no ownership rights and no ability to take possession of the car, but they are still on the hook for the debt. The lender can pursue a cosigner for the full balance without ever transferring title. Knowing which role you are actually filling prevents confusion later and helps both parties understand exactly what they are signing up for.
Lenders also treat the two roles differently in underwriting. A cosigner is often used to strengthen a weak application, and the lender may weigh the cosigner's credit heavily because they are the safety net. A co buyer is a joint applicant, meaning both incomes and both credit profiles are evaluated together. In practice, many dealerships and online lending platforms use the terms loosely, so always ask which role appears on the paperwork. If your name is on the title, you are a co buyer regardless of what the salesperson called it.
How Lenders Weigh a Co Buyer's Bad Credit
When you apply for a joint auto loan, the lender pulls credit reports for both applicants. Underwriting does not simply average the two scores. Instead, it looks at the weaker profile as a risk factor and the stronger profile as a mitigant. If one applicant has a 580 score and the other has a 720, the lender may approve the loan but at a rate closer to what the weaker profile would command on its own, or somewhere in between. The exact outcome depends on the lender's internal model, the loan-to-value ratio, the down payment, and the combined income.
Some lenders will not approve a joint application if either applicant has a recent bankruptcy, a repossession, or a score below a certain floor. Others specialize in subprime lending and will happily work with a co buyer who has bad credit as long as the stronger applicant compensates. The key takeaway is that adding a co buyer with poor credit does not erase that poor credit from the equation. It gives the lender a second person to pursue, which reduces risk, but it does not magically transform the loan into a prime-tier product. Expect the interest rate to reflect the blended risk, and plan your budget accordingly.
Income matters just as much as credit. A co buyer with bad credit but a stable, high income can sometimes help more than a co buyer with good credit and low income, because the lender's primary concern is whether the monthly payment will be made. Lenders typically look at debt-to-income ratio for both applicants combined. If the co buyer already carries heavy debt, adding a car payment could push the ratio into decline territory and sink the application. Before you apply, gather both parties' pay stubs, bank statements, and a list of existing debts so you can estimate how the lender will see the combined picture.
What the Second Person's Credit Report Reveals
A credit report does more than produce a score. It shows payment history, collections, public records, and recent inquiries. When a co buyer has bad credit, the report might reveal a pattern of late payments, a charged-off account, or a judgment. Lenders read these details as behavioral signals. A single medical collection from three years ago is viewed differently from a string of recent 30-day late payments on multiple accounts. If you are the stronger applicant, review the co buyer's report with them before applying so there are no surprises during underwriting. If you are the co buyer, be honest about what is on your report. Hiding a recent repossession only wastes everyone's time when the lender discovers it.
It also helps to know which credit bureau the lender uses. Some lenders pull all three, some pull one. A co buyer might have a clean file with one bureau and a problem with another. You cannot control which bureau the lender chooses, but you can pull all three reports for free and address any errors before the application goes in. Correcting a mistaken collection or a duplicated late payment can sometimes lift a score enough to change the loan terms.
What Happens If One Party Stops Paying
This is the scenario that keeps people awake at night, and it deserves straight talk. When two people sign an auto loan, both are jointly and severally liable. That legal phrase means the lender can demand the full payment from either party, not just half. If the co buyer with bad credit stops paying, the lender will come after the stronger applicant for the entire balance. If the stronger applicant stops paying, the lender will pursue the co buyer. There is no automatic 50/50 split in the eyes of the contract.
Missed payments hit both credit reports. A 30-day late payment on a joint auto loan appears on both files, dragging down both scores. If the loan goes into default and the car is repossessed, the repossession appears on both reports and the remaining balance after the sale (the deficiency) can be pursued against either party. This is why buying a car with a co buyer who has bad credit requires a candid conversation about what happens if life changes: job loss, divorce, disability, or a simple breakdown in communication. The lender does not care whose fault it is. It cares who pays.
There is also the question of the vehicle itself. If the co buyer is on the title and stops paying, the stronger applicant cannot simply sell the car to cover the loan without the co buyer's signature in many states. If the co buyer disappears or refuses to cooperate, the stronger applicant may need legal help to resolve the title. This is a worst-case scenario, but it happens often enough that you should plan for it before signing, not after.
If you are already struggling with approval and want to understand how lenders evaluate risk before you add a second signer, a guide on bad credit car approval and improving your chances can help you see the full picture. Sometimes the better move is to improve your own profile first rather than bring in a co buyer who adds complexity.
Protecting the Relationship with a Written Agreement
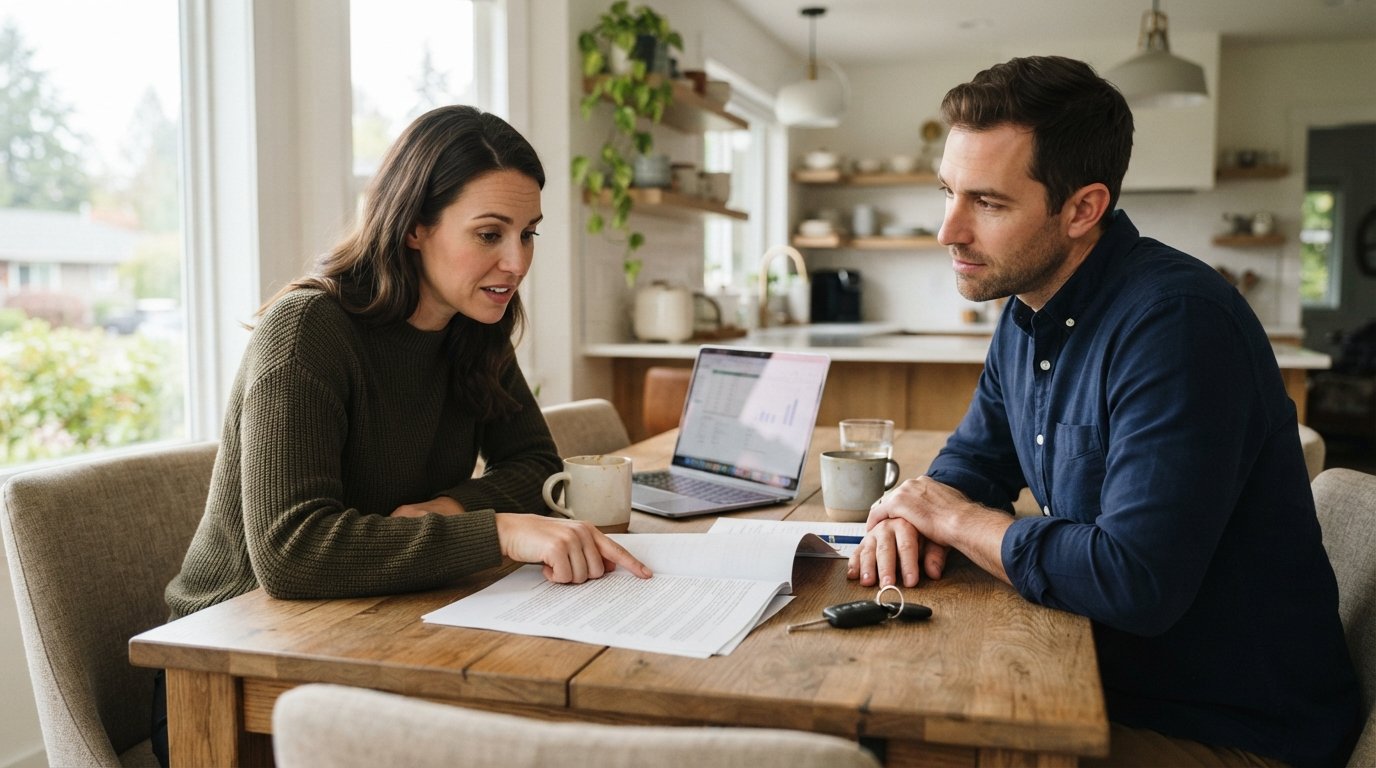
Handshake deals are the enemy of joint auto loans. Before you sign anything with the lender, sit down with the other party and write out a simple agreement that covers who pays what, who drives the car, who pays for insurance, maintenance, and repairs, and what happens if one person wants out. This agreement does not need to be drafted by a lawyer, though a notarized document carries more weight if a dispute arises. The point is to force the conversation while everyone is still friendly and optimistic.
A practical written agreement for buying a car with a co buyer who has bad credit should include the following elements. Each item should be discussed openly and written down in plain language that both parties understand.
- Payment responsibility: State exactly who pays what amount and on what date each month. If payments are split, specify the percentage or dollar amount and the method (bank transfer, joint account, etc.).
- Insurance and maintenance: Clarify who holds the policy, who pays the premium, and how repair costs are divided. Lenders require full coverage, and a lapse in insurance can trigger default.
- Exit plan: Describe what happens if one party wants to sell the car, refinance in their own name, or transfer title. Include a timeline and a process for getting the other party's signature.
- Default consequences: Acknowledge in writing that both parties are liable for the full debt and that missed payments affect both credit reports. This reduces the chance of finger-pointing later.
Beyond the written agreement, consider keeping the loan in a joint bank account that both parties fund automatically each month. This creates a paper trail and reduces the chance of a missed payment due to forgetfulness or disagreement. If one party insists on handling the payment alone, the other should still monitor the account online to confirm the payment cleared. Trust is good, but verification is better when a car loan is on the line.
Steps to Take Before You Apply
The application process itself is straightforward, but the preparation determines whether the loan helps or hurts both parties. Start by pulling both credit reports and scores so you know exactly what the lender will see. Then calculate the combined debt-to-income ratio, including the estimated car payment, insurance, and any existing debts. If the ratio is tight, consider a larger down payment or a less expensive vehicle to bring the loan amount down.
Next, decide who will be the primary applicant and who will be the co buyer. The primary applicant is usually the person whose name appears first on the loan and who will handle the day-to-day payment. If the person with bad credit is the primary, the stronger applicant should understand that they are still fully liable. Some lenders allow the stronger applicant to be primary even if they are not the main driver, which can improve the terms. Ask the lender how they structure joint applications and whether the primary/co buyer designation affects the rate.
Finally, shop around before committing. Not every lender treats joint applications the same way, and some specialize in working with buyers who have challenged credit. An online connection service can match you with lenders and dealers who are more likely to approve a joint application and who understand the dynamics of buying a car with a co buyer who has bad credit. For borrowers who have been turned away by traditional banks, platforms such as AutoTitleLoan connect consumers with financing options designed for bad credit, no credit, and past bankruptcies, which can be a useful starting point when you need to compare offers without visiting a dozen dealerships. Just remember that any connection service is not a lender, and you should review every offer carefully before signing.
When you do receive offers, compare the annual percentage rate, not just the monthly payment. A longer term lowers the payment but increases the total interest, which matters even more when the rate is elevated due to bad credit. Read the fine print for prepayment penalties and gap insurance requirements. Ask whether the lender reports to all three credit bureaus, since on-time payments on a joint loan can help both parties rebuild credit over time. That is one of the few silver linings of buying a car with a co buyer who has bad credit: consistent payments can lift both scores if the loan is managed well.
The Bottom Line on Joint Auto Loans
Buying a car with a co buyer who has bad credit is not a magic solution, but it can be a workable one when both parties go in with clear eyes. The person with the weaker profile gains access to financing they might not get alone. The person with the stronger profile takes on real risk in exchange for helping someone they care about. The loan contract binds both of them to the full debt, and the title binds them to the vehicle. Treat the arrangement like a business partnership, put the details in writing, and monitor the account together. Do that, and you can get the car you need without wrecking a credit score or a relationship.