What to Expect From Dealers in an Auto Loan Network
Know who calls after you submit a request, what dealers ask, and how to keep loan terms transparent before you sign.
By Megan Brooks
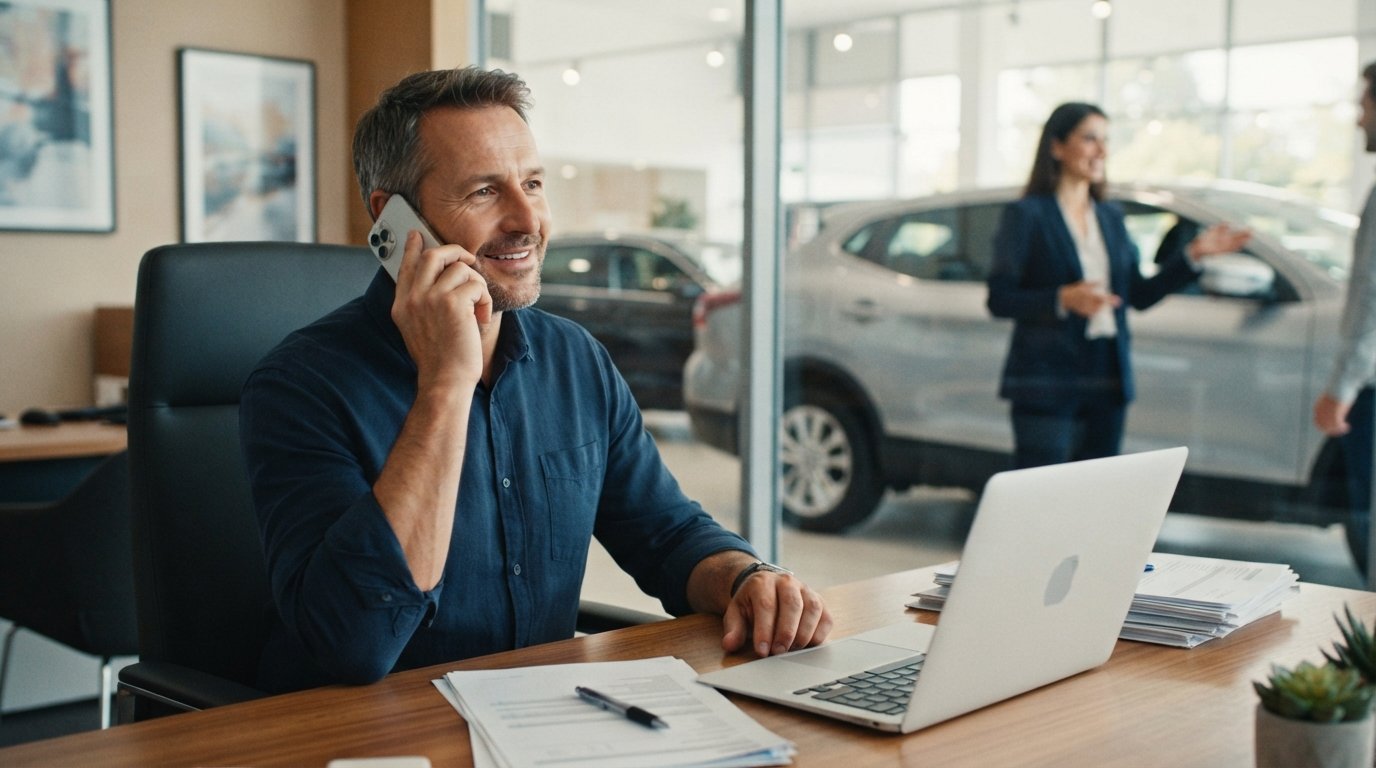
You have submitted a request through an online auto loan network, and now your phone is about to ring. For many borrowers, especially those who have been turned down by banks or credit unions, that upcoming call from a participating dealer can feel like a mystery. Who is on the other end of the line? What will they ask? Are they a lender, a salesperson, or something in between? Understanding the dealer's role before that first conversation begins can turn anxiety into confidence and help you steer the process toward a loan that actually fits your budget.
The Dealer's Role Inside an Auto Loan Network
An auto loan network is a connection service, not a bank. When you submit a request through a platform like StartAutoLoan.com, your information is shared with participating dealers and lenders who have expressed interest in working with borrowers in your credit situation. The dealer's job is to take that lead, review your basic details, and try to structure a financing offer that gets you into a vehicle. They are not approving you out of charity. They earn money when a loan funds, so their incentive is to find a program that works for both you and their lending partners.
This structure is why a network can help people who have been rejected elsewhere. Participating dealers often work with subprime lenders, in-house financing departments, and specialty finance companies that never appear in a traditional bank branch. If you want a deeper look at why this model works for challenged credit, the guide on benefits of an online auto loan network for bad credit explains how the matching process expands your options beyond a single lender's rulebook.
What you should expect, at a minimum, is a dealer who can explain which lender programs they plan to submit your application to, what those programs require, and what the resulting payment looks like. A good participating dealer acts as a guide through the paperwork, not a gatekeeper who hides the numbers until you are sitting in the finance office.
Who Calls You and When to Expect It
After you submit a request, the first contact usually comes quickly. Many networks promise outreach within minutes during business hours, and a dealer or a representative from the dealer's business development center may call, text, or email using the details you provided. The caller is typically a salesperson or a finance specialist whose job is to confirm your identity, verify a few details, and set up a visit or a more formal application.
Expect the pace to slow outside of business hours. A request submitted late on a Saturday night may not generate a call until Monday morning. If you have not heard anything within one business day, it is reasonable to follow up with the network or check your spam folder for an email. Being reachable matters: dealers move on to the next lead when a number does not answer, so keep your phone nearby and respond promptly.
You should also expect more than one call. Networks often share requests with several participating dealers, which means a handful of calls or messages in the first day or two. This is normal and is actually a feature, not a bug: multiple dealers competing for your business gives you leverage to compare offers. You are never obligated to accept any of them.
What Dealers Typically Ask on the First Call
The opening conversation is mostly information gathering. The dealer needs enough detail to decide which lender programs to pursue and to estimate a payment range. You do not have to have perfect answers, but knowing what is coming helps you prepare and protects you from saying yes to something you do not understand.
Most first calls cover the following ground:
- Identity and contact verification: Your full name, address, phone, and email, plus confirmation that you submitted the request.
- Vehicle preferences: Whether you want a new or used car, the body style or model you have in mind, and your target monthly payment.
- Income and employment: Your employer, how long you have been there, and your gross monthly income, which lenders use to calculate affordability.
- Credit situation: Whether you know your score, whether you have had a bankruptcy or repossession, and whether you have a down payment available.
- Trade-in details: If you own a car, its year, make, model, mileage, and whether it is paid off or still financed.
Notice what is not on that list: your Social Security number is usually requested later, during a formal credit application, and only with your consent. A dealer who pressures you for a full application and a credit pull before answering basic questions about rates and terms is moving too fast. You are entitled to a conversation first.
Come to the call with a few numbers ready: your gross monthly income, your rent or mortgage payment, your current car payment if any, and the amount you can put down. Having these figures on hand shortens the process and signals to the dealer that you are a serious buyer, which often translates into better effort on their side.
Dealer Financing Versus a Bank Pre-Approval
A bank pre-approval is a decision made before you shop: the bank reviews your credit and income, tells you how much it will lend and at what rate, and you walk into a dealership with a check or a rate in hand. Dealer financing works in the opposite direction. The dealer shops your application to lenders in its network, sometimes after you have picked a vehicle, and structures the deal around what those lenders will approve.
The practical differences matter. With a pre-approval, you control the shopping process and can negotiate the vehicle price as a cash-equivalent buyer. With dealer financing, the rate and terms are often negotiated as part of a larger transaction that includes the vehicle price, trade-in value, add-on products, and financing. That bundling is convenient, but it can obscure the true cost of the loan if you do not ask for the numbers separately.
Neither path is inherently better. A pre-approval gives you a benchmark; dealer financing gives you access to lenders who specialize in credit profiles that banks decline. Many borrowers use both: they get a pre-approval to establish a ceiling, then see whether a participating dealer can beat it. The key is to treat the dealer's offer as one data point, not the final word.
How Participating Dealers Get Paid and Why It Matters to You
Dealers in a loan network typically earn compensation in two ways: a fee from the network for the lead, and profit from the financing itself. That profit can come from a markup on the interest rate, from fees built into the deal, or from reserve payments that lenders pay dealers for originating loans at a certain rate. None of this is inherently improper, but you should know it exists because it explains the dealer's incentives.
Understanding those incentives helps you read the offer. A dealer who pushes a longer term to lower the monthly payment may be prioritizing the sale over your total interest cost. A dealer who presents the rate, the term, the amount financed, and the total of payments on a single sheet is giving you what you need to decide. Ask directly: "Are you making money on the rate, and can you show me the buy rate versus the contract rate?" A professional dealer will answer. If the answer is evasive, that tells you something too.
You should also know that the network itself is a connection service, not a lender. If you want to explore an additional path for securing financing against a vehicle you already own, an independent platform like AutoTitleLoan connects consumers with auto loan options and serves as a connection service rather than a direct lender, which can be useful context for understanding how these marketplaces operate.
Questions to Ask So Nothing Stays Hidden
Transparency is a two-way street. The dealer will ask you questions; you should ask your own. The borrowers who get the best outcomes are the ones who treat the first call as an interview of the dealer, not just an application. A short, focused list of questions covers most of what you need to know before you agree to anything.
Ask these questions before you commit to a visit or a credit application:
- Which lenders are you planning to submit my application to, and what are their credit and income requirements?
- What is the interest rate, the term in months, and the total amount I will pay over the life of the loan?
- Are there any fees, add-ons, or products included in this quote, and can you itemize them?
- Is this rate based on a hard credit pull, and will shopping with multiple dealers affect my score?
- What happens if I want to pay the loan off early, and are there any prepayment penalties?
Write the answers down or ask for them by email. A dealer who is willing to put the numbers in writing is a dealer worth working with. One who insists on discussing everything in person, with no paper trail, is asking you to trust a process you cannot verify.
It also helps to ask about the vehicle itself. If the dealer is arranging financing on a specific car, ask for the out-the-door price, the vehicle history report, and whether any dealer-installed add-ons are already included in the price. Financing a car and buying a car are two decisions, and separating them keeps both clean.
Red Flags That Signal a Dealer Worth Skipping
Most participating dealers are legitimate businesses trying to move inventory and fund loans. A minority are not, and the network model makes it easy to walk away from the bad ones because you have other offers to consider. Knowing the warning signs protects your time and your credit.
Watch for these behaviors: pressure to sign before you have seen the numbers, requests for payment upfront to "hold" a loan or secure approval, refusal to identify which lender is making the offer, quotes that change when you ask for itemization, and any suggestion that you must buy add-on products to qualify for financing. Add-on products like extended warranties and gap insurance can be legitimate, but they should never be a condition of approval.
Another red flag is a dealer who will not discuss the loan separately from the vehicle. If every question about the rate is answered with a question about which car you want, you are not getting the information you need. Politely end the call and move to the next offer in your queue.
After the Call: What the Process Looks Like
If the first conversation goes well, the next step is usually a formal application and, eventually, a visit to the dealership. The dealer will collect your documents (proof of income, proof of residence, and a valid driver's license are common), submit your application to the lenders it has identified, and come back with an approval, a conditional approval, or a decline. Conditional approvals often come with requirements such as a higher down payment, proof of income, or a co-signer.
Once you have an approval you are happy with, read the contract before you sign. Confirm that the rate, term, amount financed, and monthly payment match what you were quoted. Check the itemization for products you did not agree to. Verify the vehicle identification number on the contract matches the car you inspected. These few minutes of review are the last line of defense against surprises.
The whole process, from request to funded loan, can move in as little as a day when your documents are in order and you respond quickly to calls. It can also stretch longer if the dealer needs to shop multiple lenders or if you are comparing offers. Either pace is normal. What should not vary is your access to clear numbers at every stage.
Setting Expectations for a Smoother Experience
Participating dealers in an auto loan network are best understood as intermediaries with an incentive to close. They can open doors that banks keep closed, especially for borrowers with damaged credit, and they can do it quickly. They are not neutral advisers, and they are not lenders. Expect a sales-oriented conversation, expect multiple contacts, and expect to do some comparison shopping of your own.
The borrowers who come out ahead are the ones who prepare their numbers, ask for written quotes, keep vehicle purchase and loan terms separate, and treat every offer as negotiable until they sign. With those habits in place, the dealer call stops being something that happens to you and becomes a step you control.