What to Expect at Dealership Financing: First Time Buyer Guide
Understand what to expect at dealership financing as a first time buyer, from credit checks to add-ons, and learn how to protect your budget.
By Hannah Foster
Walking into a dealership as a first time buyer can feel like stepping onto a stage without a script. You know you need a car, you have a rough idea of your budget, and you have probably heard a mix of advice from friends and family. What you may not know is exactly how the financing conversation unfolds once you sit down with a salesperson or finance manager. That uncertainty is normal, but it is also avoidable. Understanding what to expect at dealership financing as a first time buyer gives you a major advantage: you can ask better questions, recognize when a deal makes sense, and avoid signing something you will regret for the next six years.
This guide walks you through the entire dealership financing experience from the moment you start browsing to the moment you drive off the lot. You will learn how dealerships evaluate first time buyers, what documents you need, how interest rates get determined, and which parts of the process you can control. You will also see how an independent connection service like StartAutoLoan.com can help you prepare before you ever step foot in a showroom, especially if you have limited credit history or have been turned down by traditional lenders.
How Dealership Financing Differs From Other Lending Channels
Dealership financing is not a single lender. It is a network of lending relationships that the dealership maintains with banks, credit unions, and specialized auto finance companies. When you apply for financing through a dealership, the finance manager submits your application to multiple lenders in what is often called a tiered lending system. Each lender reviews your credit profile, income, and the vehicle you want to buy, then returns an offer with a specific interest rate, term length, and down payment requirement.
This differs from getting a preapproved loan directly from a bank or credit union, where you negotiate with one institution and then arrive at the dealership like a cash buyer. Dealer financing can be convenient because it consolidates the car purchase and the loan into one transaction. However, that convenience comes with tradeoffs: the dealership may mark up the interest rate to earn extra profit, and you may feel pressure to accept the first offer because you are already sitting in the office.
For first time buyers, the biggest difference is leverage. If you walk in without a preapproved loan, the dealership controls the financing conversation. If you walk in with a preapproval from an outside lender, you have a baseline to compare against. You can still use dealer financing if it beats your preapproval, but you are not stuck with whatever the finance manager presents. According to a car loan pre-approval guide, securing financing before you shop can save you hundreds of dollars over the life of the loan and give you confidence during negotiations.
The First Time Buyer Conversation With the Finance Manager
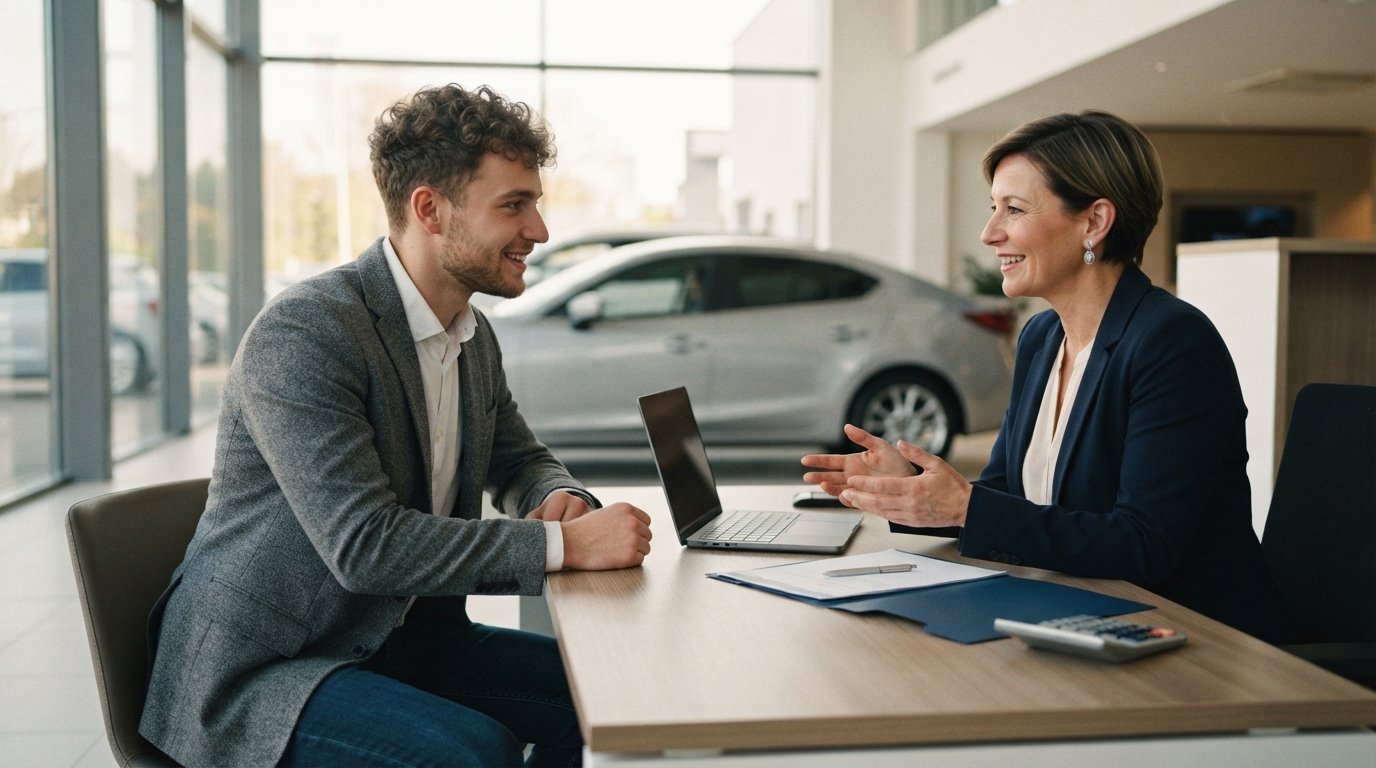
After you agree on a vehicle price, the salesperson typically walks you to the finance and insurance office, often called the F&I office. This is where the real financing discussion happens. The finance manager will ask for your driver's license, proof of income, proof of residence, and sometimes references. They will also ask about your down payment, whether you have a cosigner, and how long you want the loan term to be.
What many first time buyers do not realize is that the finance manager is not just processing paperwork. They are also a salesperson. Their job is to present financing options and additional products like extended warranties, gap insurance, and paint protection. These add-ons are not necessarily bad, but they should be evaluated separately from the loan itself. A common mistake is agreeing to a monthly payment that includes expensive add-ons without realizing how much they increase the total cost.
Here is a typical sequence you can expect in the F&I office:
- You provide personal and financial information for the credit application.
- The finance manager submits your application to multiple lenders.
- Lenders respond with offers, and the finance manager selects the best one for the dealership and for you.
- You review the terms, including interest rate, term length, monthly payment, and down payment.
- You negotiate or accept the offer, then sign the final paperwork.
Each of these steps can happen quickly, sometimes in under an hour. The speed can feel exciting, but it also means you need to slow down and read every document. Ask for a copy of the offer before you sign anything. If the finance manager pressures you to decide immediately, that is a sign to pause and review the numbers carefully.
What Lenders Look at When You Have Limited Credit
First time buyers often have thin credit files, which means they have little or no history of managing credit. Lenders respond to this in different ways. Some banks will decline an application outright if there is no credit score. Others, especially those that specialize in subprime or near-prime lending, will look at alternative factors such as income stability, employment history, and down payment size.
If you have no credit history, you are not automatically disqualified. Many dealerships work with lenders who approve first time buyers based on a combination of factors. A larger down payment reduces the lender's risk and can improve your chances. A cosigner with established credit can also make a significant difference, though it comes with risks for the cosigner if you fall behind on payments.
Bad credit is a different challenge. A past bankruptcy, repossession, or repeated late payments will lower your credit score and may limit you to subprime lenders with higher interest rates. The key is to be honest about your situation and to work with a dealership or connection service that has experience with these profiles. StartAutoLoan.com, for example, is designed for people who have been rejected by traditional lenders and connects them with a network of dealers and lenders who are more likely to say yes.
Documents and Information You Should Bring
Preparation is one of the few things you can fully control in the dealership financing process. Walking in with the right documents speeds up the application and shows the finance manager that you are serious. Missing documents can delay approval or force you to make a second trip, which can be frustrating when you are excited about a specific vehicle.
Most dealerships will ask for the following items. Keep in mind that requirements vary by lender and by state, so it is smart to call ahead and confirm what the dealership needs.
- Valid driver's license or state-issued ID
- Proof of income (recent pay stubs, bank statements, or tax returns)
- Proof of residence (utility bill, lease agreement, or mortgage statement)
- Proof of insurance for the vehicle you plan to buy
- Down payment funds (cash, cashier's check, or debit card)
- References (some lenders ask for personal or professional references)
- Cosigner information, if applicable
Having these documents organized in a folder or digital file makes the process smoother. It also gives you a chance to review your own financial picture before the finance manager does. If your income varies from month to month, bring several months of statements to show consistency. If you have a gap in employment, be ready to explain it briefly and positively.
How Interest Rates and Loan Terms Get Set
Interest rates for first time buyers are determined by a combination of credit score, loan term, down payment, vehicle age, and lender policies. A shorter loan term usually comes with a lower interest rate because the lender takes on less risk. A longer term, such as 72 or 84 months, lowers the monthly payment but increases the total interest you pay and can leave you owing more than the car is worth for a long time.
Dealerships sometimes have the ability to mark up the interest rate above the lender's buy rate. The buy rate is the rate the lender offers to the dealership, and the markup is the additional interest the dealership earns. This is legal in most states, but it is also negotiable. If you have a preapproved offer from a bank or credit union, you can use it as leverage to ask the dealership to match or beat that rate.
Another factor is the vehicle itself. New cars often qualify for lower rates because they have more predictable resale value. Used cars, especially older models with high mileage, may carry higher rates. If you are flexible about the vehicle, choosing a newer used car with lower mileage can sometimes get you a better rate than an older one.
Add-Ons, Warranties, and Pressure Tactics to Watch For
The F&I office is where many first time buyers overspend without realizing it. Extended warranties, gap insurance, tire and wheel protection, and paint sealant are all optional products. Some of them provide real value, especially gap insurance if you are putting very little money down and financing a depreciating asset. Others are overpriced and unnecessary.
The pressure to buy add-ons comes from the fact that these products are highly profitable for the dealership. The finance manager may present them as if they are required or as if declining them will jeopardize your loan approval. In reality, you can decline any add-on and still keep your financing. If you are unsure, ask for the price of each product separately and take time to compare it to what you could buy elsewhere.
One useful strategy is to separate the loan negotiation from the add-on negotiation. Agree on the vehicle price and financing terms first, then decide whether any add-ons are worth the cost. This keeps the conversation focused and prevents the monthly payment from creeping up. If the finance manager insists that a product is mandatory, ask them to show you where it is required in the loan agreement.
How to Prepare Before You Visit the Dealership
The best way to reduce stress and improve your outcome is to prepare before you walk into the dealership. Start by checking your credit score and reviewing your credit reports for errors. Disputing inaccuracies can raise your score and open up better financing options. Next, calculate a realistic monthly payment based on your income and expenses, not just the maximum the lender is willing to offer.
Then, consider getting preapproved through an independent connection service. StartAutoLoan.com allows you to submit one application and get matched with participating lenders and dealers who work with first time buyers and challenged credit profiles. This does not obligate you to accept any offer, but it gives you a clear picture of what you qualify for before you start shopping. You can also use an auto loan calculator to estimate how different rates and terms affect your payment.
Finally, decide on a down payment amount and stick to it. A down payment of at least 10 to 20 percent reduces the amount you finance, lowers your monthly payment, and can help you avoid being upside down on the loan. If you cannot afford a large down payment, consider a less expensive vehicle or wait until you have saved more.
What Happens After You Sign
Once you sign the paperwork, the dealership finalizes the sale and arranges for the loan to be funded. In some cases, the financing is approved on the spot. In others, the dealership may send you home with the car while the lender reviews the final documents. This is called a spot delivery, and it carries some risk. If the lender ultimately declines the loan, you may be asked to return the vehicle or accept different terms.
To avoid surprises, ask whether your financing is final before you leave the lot. If the dealership says it is conditional, ask what conditions remain and how long the process takes. Keep copies of every document you sign, including the buyer's order, the retail installment sales contract, and any add-on agreements. These documents are your proof of the terms you agreed to.
After the sale, set up automatic payments if possible to avoid late fees and to build a positive payment history. Making on-time payments is one of the fastest ways to improve your credit score, which means your next auto loan will likely come with better terms. If you already have a loan with a high interest rate, refinancing later can help you lower your payment once your credit improves. Resources like CarLoanRefinancing explain how refinancing works and when it makes sense to pursue it.
Frequently Asked Questions From First Time Buyers
Can I get financed with no credit history?
Yes, many lenders work with first time buyers who have no credit history. They may look at income, employment stability, down payment, and whether you have a cosigner. A larger down payment and a cosigner with good credit can significantly improve your chances.
Should I accept the first financing offer the dealership presents?
Not necessarily. The first offer is often the most profitable for the dealership, not the best for you. Compare it to any preapproved offers you have and ask the finance manager to explain how the rate was determined. You can negotiate the rate and the term.
What is a reasonable interest rate for a first time buyer?
Rates vary widely based on credit score, loan term, and vehicle type. Buyers with strong credit may see rates in the low single digits, while those with limited or damaged credit may see double-digit rates. The best way to know what is reasonable for your situation is to get multiple offers and compare them.
Do I need a cosigner to get approved?
Not always, but a cosigner can help if your credit history is thin or damaged. A cosigner with strong credit may lower your interest rate and increase your approval odds. However, the cosigner is legally responsible for the loan if you stop paying, so this decision should be made carefully.
Can I negotiate the price of add-ons?
Yes. Add-ons like extended warranties and gap insurance are often negotiable. Ask for the price of each product and compare it to what you could get elsewhere. You can also decline any add-on and still keep your financing.
Final Thoughts on Walking Into the Dealership Prepared
What to expect at dealership financing as a first time buyer comes down to preparation, transparency, and knowing your options. The finance office is not a mysterious black box. It is a sales process, and like any sales process, it rewards buyers who ask questions and compare offers. Bring your documents, know your budget, get preapproved if possible, and do not let anyone rush you into a decision.
If you have been turned down by traditional lenders or you are unsure where to start, a connection service like StartAutoLoan.com can help you explore financing options from a network of dealers and lenders who work with first time buyers and challenging credit situations. The more you understand the process before you sit down at the dealership, the more likely you are to drive away with a loan that fits your life and your budget.