What Happens After Submitting Auto Loan Request to Network
Submitting an auto loan request to a network triggers calls from dealers within minutes. Learn how to manage offers and pick the best one for your budget.
By Lauren Mitchell
You have just clicked submit on an auto loan request, and now you are waiting. Your phone might ring in minutes, or you might not hear anything for a day. That uncertainty can be stressful, especially if you have been turned down by lenders before. Understanding what happens after submitting an auto loan request to a network takes the mystery out of the process and helps you prepare for the calls, offers, and decisions ahead. This guide walks you through each stage so you can move forward with confidence, whether you have bad credit, no credit history, or are buying your first car.
The Moment You Hit Submit: What Your Request Triggers
When you submit a request through a connection service like StartAutoLoan.com, you are not applying directly to a single lender. Instead, your information enters a network of participating dealers and lenders who may compete for your business. The platform securely transmits your details, such as your name, contact information, income, and vehicle preferences, to these partners. Within seconds, the system begins matching you with financing options that fit your profile. This is not a loan approval; it is the start of a conversation with potential lenders.
The network model is designed to help people who struggle with traditional financing. If you have been rejected by banks because of poor credit or a past bankruptcy, the network includes partners who specialize in those situations. Your request acts as a signal to these lenders that you are serious about buying a car and need financing. They will review your information and decide whether to reach out with an offer. For a deeper look at how banks approach auto loans, see our guide on bank car financing and how auto loans work.
After submission, you may see a confirmation page or receive an email acknowledging your request. This is a good time to double-check that your contact details are correct. A mistyped phone number could delay or prevent dealers from reaching you. Keep your phone nearby and be ready to answer calls from unfamiliar numbers, as lenders often call quickly.
Timeline: From Submission to Dealer Contact
The speed of dealer contact can vary widely based on your credit profile, the time of day, and the number of participating partners in your area. Some people receive a call within 10 minutes, while others might wait a few hours or until the next business day. Understanding the typical timeline helps you plan your day and manage expectations.
Here is a general breakdown of what to expect:
- Within minutes: Your request is distributed to the network, and interested dealers or lenders may begin reviewing your information. You might receive an automated email or text confirming receipt.
- Within 1 to 2 hours: The first calls often come during business hours. Dealers who are eager to earn your business may reach out quickly, especially if your profile matches their lending criteria.
- Within 24 hours: Most connections happen within one business day. If you submitted your request in the evening or on a weekend, expect calls to start the next business morning.
- Up to 48 hours: In some cases, especially if your credit situation requires manual review, it may take a bit longer for lenders to respond.
If you do not hear anything within two business days, it is worth checking your spam folder or voicemail. Some lenders may leave a message. You can also follow up with the connection service to confirm that your request was received and is being processed. Remember that the network is not a lender itself; it relies on partners to initiate contact.
The timeline also depends on how specific your request is. If you are looking for a very particular vehicle or a loan amount that is outside typical ranges, it may take longer to find a match. Flexibility on the vehicle or loan terms can speed up the process.
How to Handle Multiple Calls and Offers
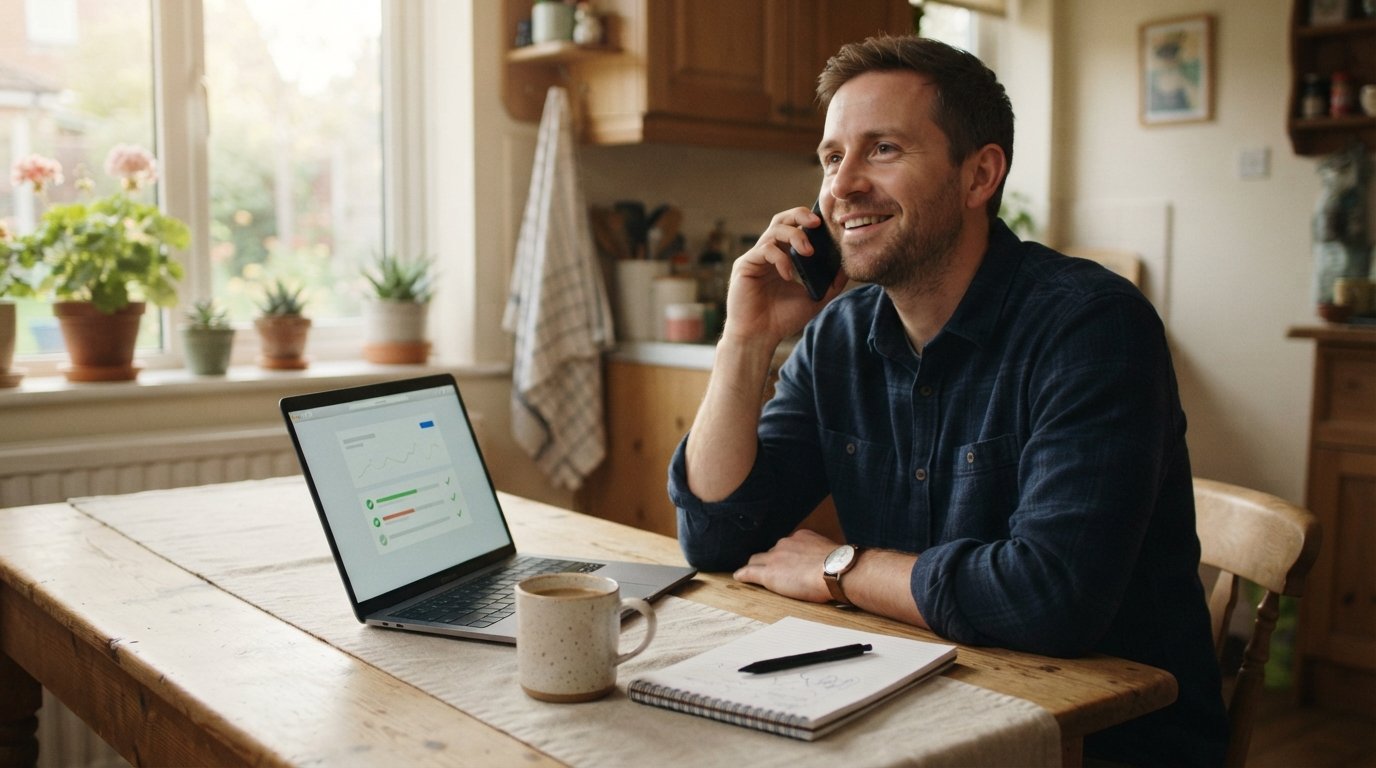
One of the biggest surprises after submitting an auto loan request to a network is the volume of calls. Because multiple dealers and lenders may be interested, your phone could ring several times in a short period. This can feel overwhelming, but it is actually a sign that the network is working. The key is to manage these calls strategically so you can compare offers without getting stressed.
First, keep a notebook or a notes app handy. Write down the name of each lender or dealer, the phone number, and the key details of their offer. This will help you keep track of who said what and avoid confusion. It is easy to mix up offers when you are talking to several people in one day.
Second, do not feel pressured to accept the first offer you receive. Dealers may use urgency tactics, such as saying the offer is only good for today. While some offers do have time limits, you are not obligated to say yes on the spot. Politely ask for the terms in writing or by email so you can review them later. A legitimate lender will be happy to provide details.
Third, be prepared to answer questions about your income, employment, and credit history. Lenders will ask for this information to verify your eligibility and determine the interest rate. Having pay stubs, proof of residence, and references ready can streamline the conversation. If you have bad credit, be honest about it; the lenders in the network already expect to work with a range of credit profiles.
Finally, consider setting up a dedicated email address or using a call-blocking app if the volume becomes excessive. You can also ask callers to communicate by email if you prefer. The goal is to gather offers without feeling harassed.
Steps to Take Once You Receive a Financing Offer
When a dealer or lender presents an offer, it is time to evaluate it carefully. An offer typically includes the loan amount, interest rate, term length, monthly payment, and any fees. Do not rush this step; a few minutes of review can save you hundreds or thousands of dollars over the life of the loan.
Follow these steps to make a smart decision:
- Verify the numbers: Check that the loan amount covers the vehicle price and any taxes or fees. Ensure the interest rate and monthly payment match what was discussed. Ask for a breakdown of all costs.
- Compare offers side by side: Use the notes you took during calls to compare interest rates, terms, and total cost. A lower monthly payment might mean a longer term and more interest paid overall. Look at the total amount you will repay, not just the monthly figure.
- Check for prepayment penalties: Some loans charge a fee if you pay off the loan early. If you plan to refinance or pay extra, avoid offers with prepayment penalties.
- Read the fine print: Look for any additional fees, such as documentation fees or dealer preparation fees. Ask about the warranty and any add-ons that might be included.
- Negotiate if possible: Do not be afraid to ask for a better rate or lower fees. Dealers want your business, and sometimes a simple request can lead to improved terms.
Once you have compared offers, choose the one that best fits your budget and needs. Before signing, make sure you understand the repayment schedule and what happens if you miss a payment. If you have any doubts, ask for clarification. A reputable lender will explain everything clearly.
If you are unsure about the process, you can also explore additional resources. For example, if you have bad credit, you might consider options through specialized platforms. One option is AutoTitleLoan, which connects consumers with auto loan financing options, though it is important to compare all offers before committing.
What Lenders and Dealers Are Looking For
To make the most of your offers, it helps to understand what lenders evaluate when they review your request. They are not just looking at your credit score; they consider your income stability, debt-to-income ratio, and the vehicle you want to buy. If you have bad credit, they may place more emphasis on your income and down payment to offset the risk.
Dealers in the network may also have specific programs for first-time buyers or people with no credit history. These programs often require proof of income and a steady job. Being prepared with documentation can speed up the approval process and show lenders that you are a responsible borrower.
Keep in mind that the network includes subprime lenders who specialize in helping people with challenged credit. They may offer higher interest rates, but they provide an opportunity to get into a car and start rebuilding your credit. Making on-time payments can improve your credit score over time, opening doors to better rates in the future.
Common Mistakes to Avoid After Submitting Your Request
Even with the best intentions, some applicants make mistakes that slow down the process or lead to unfavorable outcomes. Avoiding these pitfalls can help you secure a better deal.
- Ignoring calls: If you do not answer, lenders may move on to the next applicant. Try to answer calls or return messages promptly.
- Providing inaccurate information: Exaggerating your income or lying about your credit history can lead to rejection or legal issues. Be honest from the start.
- Accepting the first offer without comparing: You have the power to choose. Comparing multiple offers can save you money.
- Not asking about fees: Hidden fees can increase the cost of your loan. Always ask for a full breakdown.
- Forgetting to negotiate: Many terms are negotiable, especially with dealers. A little back-and-forth can improve your deal.
By staying organized and proactive, you can turn a potentially chaotic experience into a smooth path to car ownership.
How StartAutoLoan.com Fits Into the Process
StartAutoLoan.com is an independent online platform that connects consumers with auto loan financing options. It is not a direct lender, bank, or dealership. When you submit a request through StartAutoLoan.com, you are tapping into a network of participating lenders and dealers who may offer you financing. The service is designed for people who have faced rejection from traditional lenders, including those with bad credit, no credit, or past bankruptcies.
The platform offers a streamlined application tool that securely transmits your information to its network. You may be contacted by a local dealer or lender within minutes, and approval can happen in as little as 24 hours. StartAutoLoan.com emphasizes easy auto financing approval, with loans up to $50,000 and options for new, used, and refinance loans. There is no obligation to accept any offer, and the service is free to use.
If you are ready to explore your options, you can start by submitting a request through StartAutoLoan.com. The process is straightforward, and it could connect you with the financing you need to get behind the wheel.
Submitting an auto loan request to a network is the first step toward securing financing, even if you have been turned down before. By knowing what to expect, managing incoming calls, and carefully evaluating offers, you can navigate the process with confidence. Stay patient, stay organized, and remember that the right offer is out there for you.