Total Cost of Ownership Beyond Auto Loan Payment
Uncover the total cost of ownership beyond auto loan payment, from insurance and fuel to depreciation, and learn to build a budget that avoids surprises.
By Andrew Collins
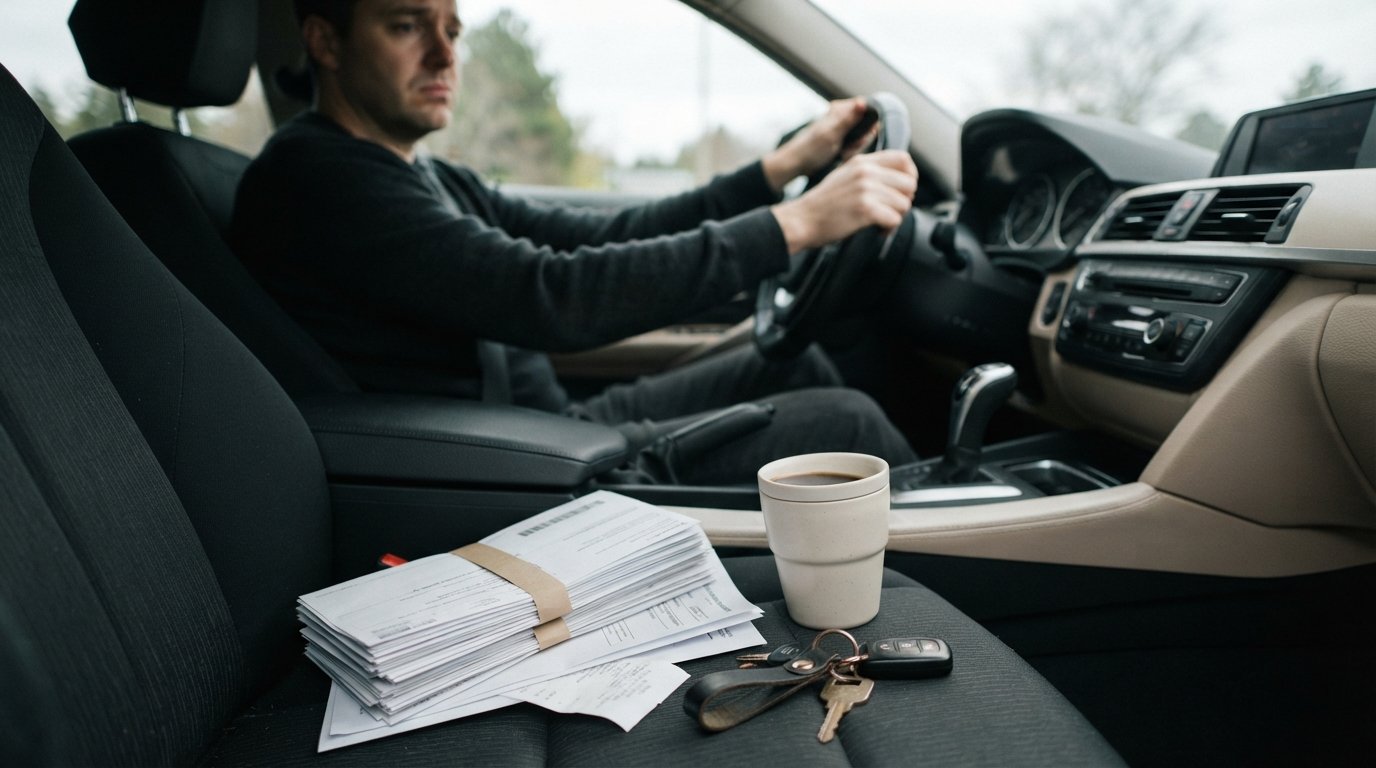
You have found the car, negotiated the price, and secured a monthly payment that fits your budget. Before you sign the paperwork, pause and ask a critical question: can you afford the car, or just the loan? The monthly auto loan payment is only one slice of a much larger financial pie. Insurance premiums, routine maintenance, fuel, taxes, and the silent wealth eroder known as depreciation all demand a share of your wallet. Ignoring these costs is a common trap that leaves drivers feeling financially stretched long after the new car smell fades. Understanding the total cost of ownership beyond auto loan payment is the key to protecting your budget and avoiding unpleasant surprises.
The Hidden Expenses That Define True Car Ownership
When you drive off the lot, you become responsible for a web of ongoing expenses that never appear on your loan statement. These costs vary based on the vehicle you choose, your driving habits, and where you live. For buyers with challenged credit who may already be managing a higher interest rate, every extra dollar counts. That is why looking at the full picture is especially important.
Insurance is often the first shock. Lenders require full coverage on financed vehicles, and premiums can swing wildly based on your driving record, age, location, and the car's safety features. A sports car will cost far more to insure than a midsize sedan. Maintenance is another category that catches people off guard. New cars need oil changes, tire rotations, and eventually brake pads and fluids. Used cars may need more immediate attention. Fuel costs depend on your commute and the vehicle's efficiency. Finally, taxes and registration fees are recurring obligations that vary by state and sometimes by county.
These hidden expenses add up quickly. A $400 monthly loan payment might actually represent only 60 percent of the car's true monthly cost. For someone rebuilding credit or buying a car for the first time, failing to account for these extras can lead to missed payments on other bills or the vehicle itself.
Breaking Down Insurance, Maintenance, Fuel, and Taxes
Each of these categories deserves its own line item in your budget. Let us examine what to expect and how to estimate them accurately.
Insurance Premiums
Full coverage insurance typically includes collision and comprehensive, which protect both you and the lender's interest in the vehicle. The cost is influenced by the car's replacement value, repair costs, and theft rates. Before buying, get quotes for the specific make and model you are considering. Even a difference of a few hundred dollars per year can shift your monthly affordability. For those with bad credit, some insurers may charge higher rates, so shopping around is essential.
Maintenance and Repairs
Routine maintenance like oil changes, tire rotations, and inspections are predictable. Repairs are not. Setting aside a maintenance fund is wise. A general rule is to budget a few cents per mile for maintenance, or roughly $50 to $100 per month for a typical used car. New cars under warranty may cost less initially but still need regular service. For first-time buyers, learning basic upkeep can prevent costly breakdowns.
Fuel Costs
Calculate your annual fuel cost by estimating your monthly mileage, dividing by the car's combined MPG, and multiplying by the current price per gallon. This number can vary significantly between a compact car and an SUV. If you commute long distances, fuel efficiency should be a top priority. Even a small improvement in MPG can save hundreds of dollars each year.
Taxes and Registration
Sales tax on the purchase price is often rolled into the loan, but annual property taxes and registration fees are out-of-pocket. Some states charge an annual excise tax based on the car's value. These fees can be several hundred dollars per year. Check with your local DMV to understand the recurring costs in your area. For a more detailed breakdown of financing options that fit your budget, consider exploring resources like AutoTitleLoan for additional guidance.
Depreciation: The Silent Budget Killer
Depreciation is the difference between what you paid for the car and what it is worth when you sell or trade it. It is not a cash outlay, but it represents real money lost over time. A new car typically loses a significant percentage of its value in the first year, then continues to decline. Some vehicles hold their value better than others, but none are immune.
To understand the impact, consider a $25,000 new car that loses 20 percent of its value in the first year. That is $5,000 gone, or more than $400 per month in the first year alone. When you factor in depreciation, the true cost of ownership beyond the auto loan payment becomes much higher. For buyers with limited budgets, a lightly used car that has already absorbed the steepest depreciation can be a smarter financial move. It allows you to avoid that initial value drop while still getting a reliable vehicle.
Resale value also matters for future planning. A car that depreciates slowly will leave you with more equity when you are ready to trade in or sell. Research the projected resale value of any model you consider. For first-time buyers or those with past credit challenges, choosing a vehicle with strong resale value can make a big difference in the long run.
Creating a Comprehensive Car Budget
Now that you know the components, it is time to build a budget that captures everything. A comprehensive car budget should include your loan payment, insurance, fuel, maintenance, taxes, and a depreciation reserve (if you plan to replace the car eventually). Here is a step-by-step framework to follow:
- Estimate your monthly loan payment. Use an auto loan calculator to determine what you will owe each month based on the amount financed, interest rate, and term.
- Get insurance quotes. Contact several insurers and provide the vehicle identification number (VIN) or at least the make, model, and year. Ask for full coverage limits that satisfy your lender.
- Calculate fuel costs. Use your estimated monthly mileage and the car's combined MPG to project fuel expenses.
- Research maintenance and repair averages. Look up typical maintenance schedules and costs for the model. Set aside a monthly amount for unexpected repairs.
- Factor in taxes and fees. Check your state's registration and property tax rules. Divide annual fees by 12 to get a monthly figure.
- Account for depreciation. If you plan to keep the car for several years, estimate the annual depreciation and set aside a monthly amount toward a future down payment.
Add these amounts together to arrive at your total monthly cost of ownership. Compare this number to your take-home pay. A common guideline is to keep total transportation costs below 15 to 20 percent of your monthly income. If the total exceeds that range, consider a less expensive vehicle or explore financing options that offer lower rates.
For those who have been rejected by traditional lenders, platforms like StartAutoLoan.com can connect you with a network of dealers and lenders who work with bad credit, no credit, or past bankruptcies. Their streamlined application can provide approval in as little as 24 hours, helping you secure financing while keeping the overall budget in mind.
Strategies to Lower Your Total Cost of Ownership
Once you understand the full cost picture, you can take steps to trim expenses. Here are several practical strategies:
- Choose a reliable, fuel-efficient model. Cars with a history of low repair costs and good gas mileage save money every month.
- Shop for insurance annually. Rates change, and loyalty does not always pay. Comparing quotes can save hundreds per year.
- Perform regular maintenance. Small issues become expensive repairs if ignored. Following the manufacturer's schedule protects your investment.
- Consider a used car with remaining warranty. Certified pre-owned vehicles often come with extended coverage and have already absorbed the steepest depreciation.
- Refinance your auto loan. If your credit has improved since you bought the car, refinancing to a lower interest rate can reduce your monthly payment and total interest paid. StartAutoLoan.com offers refinance options that may help.
These strategies not only reduce your monthly outlay but also make your overall financial picture more stable. For someone rebuilding credit, keeping total costs low can free up cash to pay down other debts or build savings.
Why This Matters for Bad Credit and First-Time Buyers
If you have faced credit challenges, you may be offered a loan with a higher interest rate. That higher rate increases your monthly payment and the total interest you pay over the life of the loan. When you add the other ownership costs, the total can become overwhelming. That is why it is crucial to look beyond the loan payment and consider the entire financial commitment.
First-time buyers often overlook costs like insurance and maintenance because they are focused on the purchase price and loan approval. Educating yourself upfront prevents future stress. Platforms like StartAutoLoan.com provide educational resources and connect you with lenders who understand your situation. They are not a direct lender, but a connection service that helps you find options.
By budgeting for the total cost of ownership beyond the auto loan payment, you set yourself up for success. You avoid the trap of being car poor, where your vehicle consumes so much of your income that other financial goals suffer. You also build a positive payment history, which can improve your credit over time.
Taking control of your car ownership costs starts with awareness. By mapping out every expense, from the loan payment to the eventual resale value, you can make informed decisions that fit your life and your wallet. Whether you are buying your first car or looking to refinance, understanding the full financial picture empowers you to drive with confidence.