Spotting Predatory Auto Loans: Red Flags and Protection
Spotting predatory auto loans red flags and protection starts with knowing the fine print. Learn the warning signs that can save you thousands.
By Ryan Walker
A car loan can feel like a lifeline when you need reliable transportation, especially after a financial setback. Yet the same urgency that pushes you toward a dealership or a quick online approval is exactly what predatory lenders count on. A predatory auto loan is not simply a loan with a high interest rate. It is a deal loaded with hidden fees, confusing terms, or pressure tactics that benefit the lender far more than the borrower. The good news is that these traps follow recognizable patterns, and once you know the patterns, you can avoid them. This guide walks you through the most common red flags, the fine print that matters, and the concrete steps you can take to protect yourself before you sign anything.
What Makes an Auto Loan Predatory
Predatory lending is less about a single number and more about a combination of terms that stack the deck against you. A loan can be perfectly legal and still be predatory in effect. The key is whether the lender or dealer has misrepresented the cost, buried obligations in paperwork, or steered you into a product you cannot realistically repay. Subprime auto financing, which serves borrowers with damaged or thin credit, is a legitimate and necessary part of the market. Predatory lending is the abusive version of that same market.
Three elements usually appear together. First, the true cost of the loan is obscured, whether through add-ons, confusing rate quotes, or payments that hide a long term. Second, the borrower is pressured to decide quickly, often the same day, without time to compare. Third, the loan is structured so that default is likely, which lets the lender repossess the vehicle and resell it while keeping payments already made. Spotting these patterns early is the difference between a manageable loan and a financial trap.
Red Flags to Watch for Before You Sign
The most reliable way to spot a predatory auto loan is to watch how the deal is presented, not just what it costs. Sales pressure, missing numbers, and vague answers are warning signs that deserve your full attention. If a dealer or lender resists giving you written figures, that resistance itself is information. Here is a list of red flags that should slow you down or send you looking elsewhere:
- Monthly payment focus instead of total cost. A salesperson who only talks about what you will pay per month may be stretching the term to hide a high rate and a huge total interest bill.
- Surprise add-ons in the contract. Gap insurance, credit life insurance, paint protection, and extended warranties can add thousands to the financed amount without improving your loan.
- No clear annual percentage rate (APR). The APR is the single number that lets you compare offers. If it is missing or quoted verbally, ask for it in writing.
- Pressure to sign today. Legitimate lenders do not need you to commit in minutes. Urgency is a tool used to prevent comparison shopping.
- Blank spaces or incomplete forms. Never sign a contract with empty fields. A blank field can be filled in later without your knowledge.
Beyond the sales floor, watch for loan terms that seem designed to fail. A term of 84 or 96 months on a used car, for example, often means you will owe more than the vehicle is worth for years. That situation, called being upside down, makes it hard to sell or trade the car and leaves you exposed if it is totaled. Similarly, a prepayment penalty that charges you for paying off the loan early keeps you locked into a high rate even when your credit improves.
Another red flag is a lender who promises approval regardless of income or asks you to inflate your income on the application. That is not a favor. It is a setup for a loan you cannot carry, and it can expose you to fraud allegations. Honest financing, including the kind of bad credit auto financing that StartAutoLoan.com connects borrowers with, starts with accurate information and realistic terms.
How to Read the Fine Print on an Auto Loan
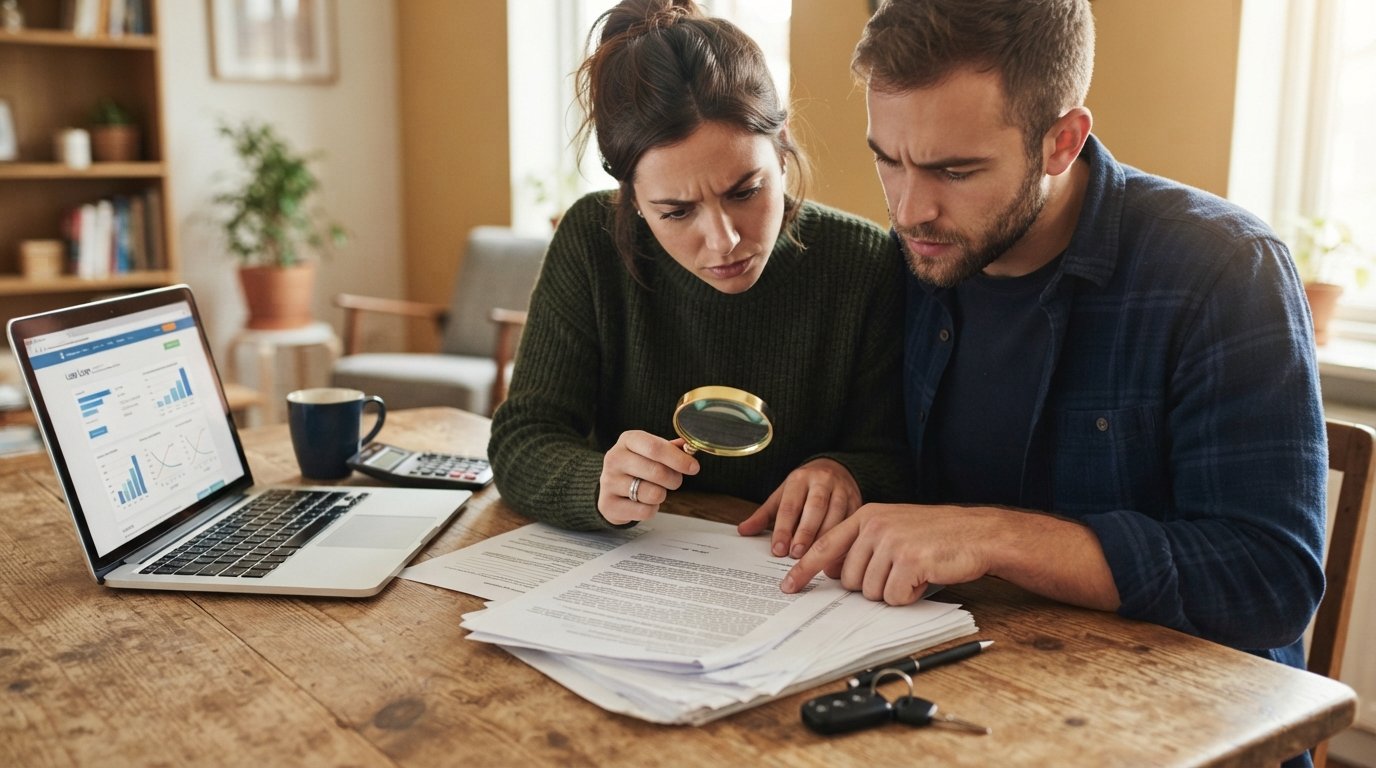
Most predatory terms hide in documents that borrowers skim. The finance agreement, the buyer's order, and the addendum are the three places to focus your attention. Ask for copies of every document before you sign, and take them to a quiet place where you can read without a salesperson hovering. If the dealer will not let you review the paperwork, that is a serious warning sign.
On the finance agreement, look for four numbers: the amount financed, the APR, the term in months, and the total of payments. Multiply the monthly payment by the number of months and compare that to the amount financed. The difference is the interest and fees you will pay. If that gap feels enormous, it probably is. Also check whether the contract includes a mandatory arbitration clause that limits your right to sue, and whether it lists any prepayment penalty.
On the buyer's order and addendum, check every line item. Dealers sometimes add accessories or services that were never discussed. You have the right to decline optional products, and doing so can lower the amount you finance significantly. A simple framework helps: separate required costs (taxes, title, registration, the vehicle price) from optional ones. If an optional item is already printed on the contract, ask for it to be removed in writing before you sign.
Interest rate markup is another hidden cost. Dealers are often allowed to add a percentage point or two to the rate a lender approves, and that markup becomes profit. You can protect yourself by getting preapproved through a credit union or an online connection service before you visit the dealership. When you have a benchmark rate in hand, you can see whether the dealer's offer is fair or inflated.
Protection Strategies That Actually Work
Protection begins before you set foot on a lot. The single most effective step is to arrange your own financing first. A preapproval from a bank, credit union, or online platform gives you a maximum loan amount, a rate, and a term you can compare against anything a dealer offers. It also shifts the conversation from "Can I get approved?" to "Does this deal beat my preapproval?" For borrowers with damaged credit, a service like StartAutoLoan.com's quote request tool can match you with participating lenders who work with subprime profiles, so you walk in with options rather than desperation.
Second, set a total budget, not just a monthly one. Lenders often approve more than you should comfortably spend. A practical rule is to keep total vehicle costs (payment, insurance, fuel, maintenance) under 15 to 20 percent of your take-home pay. If a loan only works when you stretch the term past 72 months, the car is probably too expensive for your situation.
Third, slow the process down. You are allowed to take a contract home, sleep on it, and return the next day. Reputable dealers expect it. Predatory sellers resist it. If you feel rushed, that is your cue to leave. Similarly, never sign anything you do not understand, and never let anyone fill in blanks after you have signed.
Fourth, understand the difference between a connection service and a direct lender. Platforms like StartAutoLoan.com are not banks or dealerships. They connect you with a network of participating lenders and dealers who compete for your business. That competition is your friend, because it gives you multiple offers to compare. You are never obligated to accept any offer, and you can walk away at any point before signing.
For borrowers comparing specific lenders, it also helps to research how major institutions structure their programs. Our guide on Navy Federal auto finance rates and loan options explains how credit union financing can offer lower rates and member-friendly terms, which gives you a useful baseline when you evaluate dealer offers.
Steps to Take If You Suspect a Predatory Loan
If you have already signed a loan that feels predatory, you are not without options. The first step is to gather every document: the contract, the buyer's order, payment records, and any correspondence with the lender or dealer. Read the contract carefully for terms about cancellation, refinancing, and prepayment. Many states give borrowers a short window to cancel certain contracts, so timing matters.
Next, contact the lender in writing and dispute any charges or terms you believe were misrepresented. Keep copies of everything. If the dealer added products you did not agree to, you may be able to have them removed or the contract rescinded. If the loan is simply too expensive, refinancing is often the fastest escape. Refinancing replaces your current loan with a new one at a lower rate or better term, ideally after you have made several on-time payments and improved your credit.
You can also file complaints with your state attorney general's office, the Consumer Financial Protection Bureau, and your state's motor vehicle dealer board. These agencies track patterns of abuse and can intervene in serious cases. For borrowers who want to explore refinancing options, platforms like CarLoanRefinancing.com offer educational guides and rate comparisons that help vehicle owners evaluate whether a refinance makes sense. Combining that research with your own budget and a written payoff quote from your current lender gives you a clear picture of what a better loan would look like.
Finally, remember that a bad loan is not a moral failure. Predatory lenders design their products to be confusing. The correction is information and action, not shame. Whether you refinance, negotiate, or simply warn others, you are taking back control of your financial future.
Building a Safer Auto Financing Path
The best protection against predatory auto loans is preparation. Know your credit score before you shop. Get preapproved. Compare at least three offers, including one from a credit union and one from an online connection service. Read every document, and never let urgency override your judgment. These habits turn a stressful process into a manageable one, and they put you in a position to negotiate rather than react.
It also helps to work with platforms that are transparent about what they do. StartAutoLoan.com is a connection service, not a lender, and it does not charge you to submit a request. Its role is to match you with participating lenders and dealers who specialize in a range of credit situations, including bad credit, no credit, and past bankruptcy. That model gives you access to multiple offers without the pressure of a single dealership. If you have been rejected elsewhere, that does not mean you are out of options. It means you need a different path, and the right financing partner can help you find it.
Predatory lending thrives on misinformation and haste. By learning the red flags, reading the fine print, and using preapproval and comparison shopping as your first line of defense, you can secure a loan that fits your budget and your life. Take your time, ask hard questions, and treat every offer as negotiable. Your future self, the one making that payment every month, will thank you.