Questions to Ask Before Signing Auto Loan Agreement
Arm yourself with essential questions to ask before signing auto loan agreement. Learn how to spot hidden fees and secure better terms today.
By Stephanie Collins
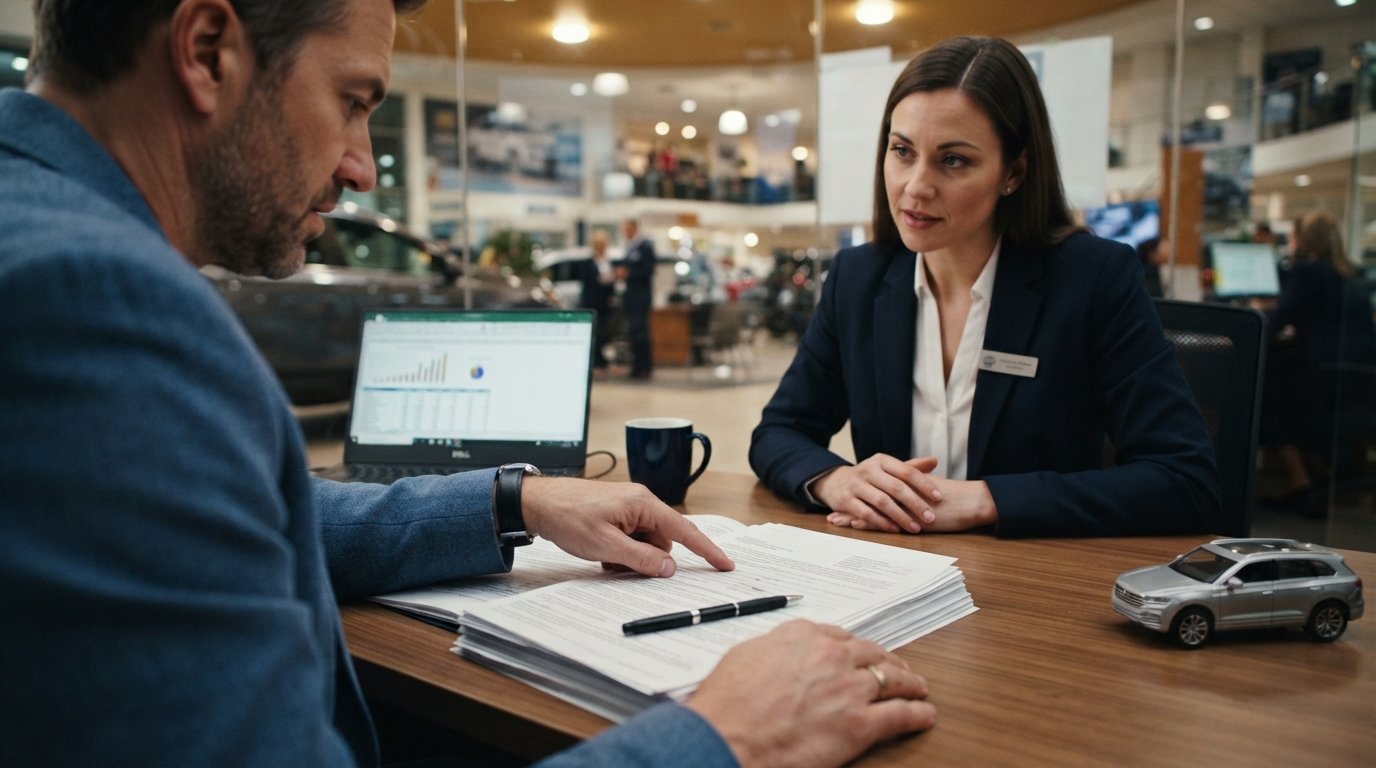
You have found the car, negotiated the price, and now the finance manager slides a stack of papers across the desk. The excitement of a new vehicle can quickly turn into anxiety when you face a complex auto loan agreement filled with jargon and numbers. Signing on the dotted line is a legally binding commitment that will affect your budget for years to come. Whether you have perfect credit or you are seeking bad credit auto financing, understanding every detail of the contract is non-negotiable. Before you pick up that pen, you need to take control of the conversation by asking specific, probing questions.
Understanding the Financial Anatomy of Your Loan
The most critical aspect of any auto loan is the cost. However, the "cost" is not just the price of the car. It is a combination of the interest rate, the loan term, and any additional fees rolled into the financing. Many buyers focus solely on the monthly payment, which is a common trap. Dealers can manipulate the monthly payment by extending the loan term, meaning you pay less per month but significantly more over the life of the loan. You must ask for the full picture.
Start by asking, "What is the Annual Percentage Rate (APR)?" The APR is different from the interest rate because it includes the interest plus specific fees required to get the loan. This gives you the true cost of borrowing. If the finance manager hesitates or tries to redirect you to the monthly payment, insist on the APR. It is your right to know the exact percentage you are being charged. Additionally, ask if the rate is fixed or variable. A fixed rate stays the same, while a variable rate can fluctuate, potentially increasing your payments if market rates rise.
Another essential question is, "What is the total amount financed?" This figure includes the price of the vehicle, taxes, title fees, registration, and any add-ons like extended warranties or gap insurance that have been rolled into the loan. You need to verify that this number matches your expectations. If it is higher than you anticipated, ask for a line-by-line breakdown of every charge. Do not accept vague explanations. Every dollar must be accounted for.
The Impact of Loan Term and Monthly Payments
Loan terms have stretched in recent years, with some lenders offering 84-month or even 96-month loans. While a longer term lowers your monthly payment, it comes with significant risks. You will pay much more in interest over the life of the loan, and you are more likely to be "upside down" (owing more than the car is worth) for a longer period. Ask the finance manager, "What is the total interest I will pay over the life of this loan?" Seeing that total number can be a wake-up call. A $25,000 loan at 8% interest for 60 months costs significantly less in interest than the same loan stretched over 72 or 84 months.
You should also ask about the specific monthly payment breakdown. Does the quoted payment include everything, or are there hidden costs? Ask, "Is there a prepayment penalty?" A prepayment penalty is a fee charged if you pay off the loan early. You want a loan with no prepayment penalty so you can save money by paying it off faster or refinancing later without being penalized. If the lender says there is a penalty, you should consider it a red flag and look for financing elsewhere.
If you are working with a dealer, ask if they are marking up the interest rate. Dealers often secure a rate from a bank and then increase it slightly to earn a commission, known as a dealer reserve. Asking, "Is this the buy rate or the contract rate?" can reveal if there is room for negotiation. Being informed about these practices empowers you to negotiate a better deal.
Add-Ons, Warranties, and Insurance Requirements
The finance office is where many customers feel pressured to buy extras. These add-ons can add thousands to your loan balance. You must ask, "Are any of these add-ons mandatory to get the loan?" In most cases, only proof of comprehensive and collision insurance is required. Items like extended warranties, paint protection, and VIN etching are optional. If you do not want them, you have the right to decline them. Do not let a finance manager tell you that a warranty is required for approval if it is not.
Regarding insurance, ask, "What are the specific insurance requirements for this loan?" Lenders typically require you to carry full coverage, but they may also require a maximum deductible. If you fail to maintain the required insurance, the lender may purchase "force-placed" insurance for you, which is extremely expensive and gets added to your loan balance. Verify these requirements with your insurance agent before signing to ensure you are compliant and to get an accurate quote.
If you are considering gap insurance, ask how much it costs through the lender versus your car insurance provider. Gap insurance covers the difference between what you owe and what the car is worth if it is totaled or stolen. While it is a valuable product, it is often much cheaper through your insurance company than through the dealership. Asking this question can save you hundreds of dollars.
Critical Questions to Ask Before You Sign
To ensure you are making a sound financial decision, you need a checklist of questions that cover all aspects of the agreement. This list helps you uncover hidden fees, understand the terms, and protect your financial future. Use these questions to guide your review of the contract:
- What is the exact APR and total finance charge? This tells you the true cost of the loan.
- Are there any prepayment penalties? You want the freedom to pay off the loan early without fees.
- What is the total amount financed, and what does it include? Ensure taxes, fees, and add-ons are correct.
- Are any add-ons (warranty, gap, etc.) optional? Confirm you are not being forced to buy extras.
- What happens if I miss a payment? Understand the grace period and late fees.
Asking these questions not only clarifies the terms but also signals to the lender that you are a savvy consumer. If you are looking for a lender who is willing to work with your situation, whether you have bad credit or no credit history, you might need to explore different avenues. For those who have been turned down by traditional banks, understanding how to navigate the process is key. You can find valuable insights on these options at CarLoanRefinancing, which offers resources on how to optimize your auto loan and potentially lower your monthly payments.
The Importance of Reading the Fine Print
Never sign a contract you have not read from top to bottom. This seems obvious, but in the high-pressure environment of a dealership, it is easy to skim. Ask for a copy of the contract to take home overnight if you need to. A reputable dealer will allow this. If they refuse, it is a major red flag. Look for blank spaces in the contract. Never sign a contract with blank fields; a dishonest dealer could fill them in later. Draw a line through any empty space before signing.
Check the vehicle identification number (VIN) on the contract against the car you are buying. Errors happen, and you want to make sure you are financing the correct vehicle. Verify the mileage and the year, make, and model. If the contract says "used" but you are buying a demo model with 3,000 miles, the financing terms might differ.
Finally, understand the "cooling off" period, if one exists in your state. Some states allow you to cancel the contract within a few days, but many do not. Do not assume you can change your mind after signing. Once the ink is dry, you are legally obligated to the terms. Therefore, the time to ask questions is before you sign, not after.
Navigating Financing Options with StartAutoLoan
If you are feeling overwhelmed by the process or if you have been rejected by traditional lenders, StartAutoLoan.com is designed to help. As a connection service, we match you with a network of lenders and dealers who specialize in various credit situations. We understand that life happens, and bad credit does not have to be a permanent barrier to getting a reliable vehicle.
Our platform allows you to submit a secure application and get connected with financing options quickly. We serve as a bridge, not a lender, meaning we do not set the terms but rather connect you with partners who can. Whether you are a first-time buyer or looking to refinance an existing high-interest loan, having the right questions ready is crucial. By understanding the loan agreement and asking the right questions, you can drive off the lot with confidence, knowing you have secured the best possible deal for your financial situation.