Pre-Application Checklist for First-Time Car Loan
A pre-application checklist for first-time car loan helps you check credit, budget, and documents so you can avoid rejections and secure better terms.
By Lauren Mitchell
You have probably heard that buying your first car is exciting. It is, but it also comes with a stack of paperwork, a credit check, and a few decisions that can affect your finances for years. The difference between a smooth approval and a frustrating rejection often comes down to what you do before you ever fill out an application. That is why a pre-application checklist for first-time car loan matters so much. It forces you to slow down, get organized, and walk into the process with realistic numbers and clean documents. Whether you have no credit history at all or you are recovering from a past financial setback, the steps below will help you avoid surprises and improve your chances of getting approved on terms you can afford.
Start With Your Credit Report, Not the Car Lot
Before you start browsing listings or visiting dealerships, pull your credit reports from all three major bureaus. You are entitled to one free report per year from each bureau through AnnualCreditReport.com. Review each report line by line and look for errors such as accounts that are not yours, duplicate collections, or payments reported late when you paid on time. Disputing mistakes can take weeks, so start early. Even a small error can drag your score down and cost you a better interest rate.
If you have no credit history, do not panic. Many first-time buyers are in the same position. What matters is that you understand where you stand before a lender runs a hard inquiry. A hard inquiry without preparation can lead to a denial that stays on your record and makes the next application harder. Knowing your score range also helps you set expectations. If your score is below 600, focus on lenders and programs that specialize in bad credit or no credit auto loans rather than applying at a traditional bank that will likely reject you.
Once you have your reports, write down your scores and note any negative items that are accurate. You cannot erase accurate derogatory marks, but you can prepare an explanation. Lenders sometimes consider context, especially for medical collections or a single past late payment. The key is to know your story before someone asks.
Build a Realistic Budget and Save for a Down Payment
Your car payment is only one piece of the puzzle. A realistic budget includes insurance, fuel, maintenance, registration, and taxes. First-time buyers often focus on the monthly loan payment and forget that insurance for a new driver can be expensive. Get quotes before you shop so you know what you are walking into. A good rule of thumb is to keep your total monthly vehicle costs under 15 to 20 percent of your take-home pay. If that feels tight, consider a less expensive car or a larger down payment.
A down payment does more than reduce the amount you finance. It also signals to lenders that you have skin in the game, which can improve your approval odds and lower your interest rate. Aim for at least 10 percent down, and 20 percent if you can manage it. If you are buying used, a larger down payment helps offset the fact that used cars can depreciate quickly and may have higher mileage. Start saving now, even in small amounts, so you have a cushion when you find the right vehicle.
Here is a simple framework to organize your budget before you apply:
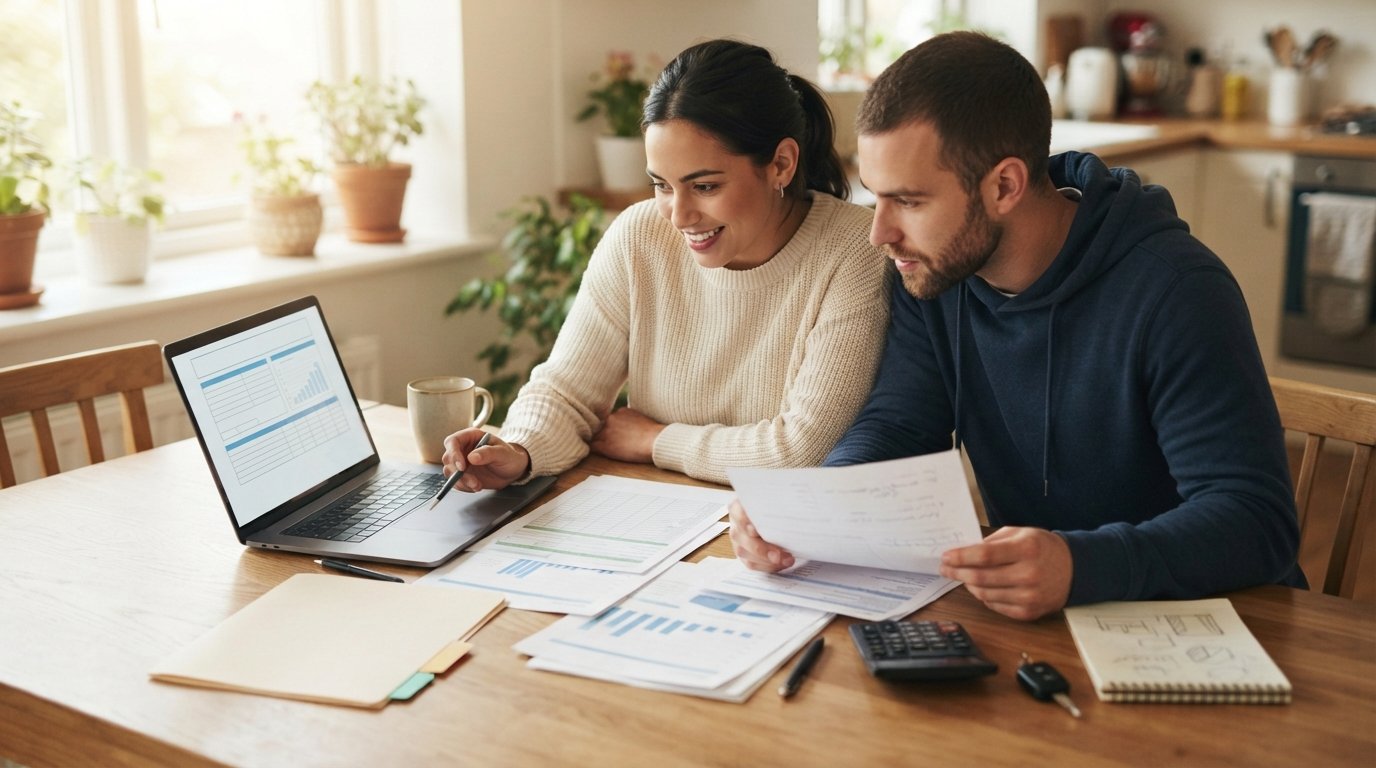
- Calculate your monthly take-home income after taxes and deductions.
- List fixed expenses such as rent, utilities, food, and existing debt payments.
- Set a maximum monthly car payment that leaves room for savings and emergencies.
- Add estimated insurance, fuel, and maintenance costs to that payment.
- Decide on a down payment target and a timeline for saving it.
Once you have those numbers, you can shop with confidence. You will know which vehicles fit your budget and which ones are likely to stretch you too thin. This step alone can save you from a loan that feels affordable at signing but becomes a burden six months later.
Gather Your Income and Identity Documents
Lenders want proof that you can repay the loan and that you are who you say you are. Before you apply, collect the documents most lenders request. Having them ready speeds up the process and shows you are serious. For most first-time buyers, the list includes a government-issued photo ID, recent pay stubs from the last 30 to 60 days, bank statements from the last two to three months, and proof of residence such as a utility bill or lease agreement. If you are self-employed, you may need tax returns or profit and loss statements. If you receive disability, Social Security, or child support, have documentation of that income as well.
Organize these documents in a folder, physical or digital. When a lender asks for them, you can respond quickly instead of scrambling. This is especially important if you are working with a connection service that matches you with multiple lenders. A complete file helps your application move faster and reduces the chance of a lender withdrawing an offer because paperwork dragged on. Keep copies for your records and never send original documents through email unless the lender has a secure portal.
If you have a co-borrower or co-signer, gather their documents too. A co-signer with good credit can help you qualify for a better rate, but it also means that person shares responsibility for the loan. Have an honest conversation about that before you apply. The pre-application checklist for first-time car loan should include a clear agreement about who pays what and what happens if something goes wrong.
Know What You Can Afford Before You Shop
It is easy to fall in love with a car that costs more than you planned. That is why you should set a price range before you visit a dealership or browse online listings. Use your budget to determine the maximum purchase price, not just the monthly payment. A longer loan term can lower the monthly payment but increase the total interest you pay. It can also leave you owing more than the car is worth, which is called being upside down. For a first-time buyer, a shorter term with a slightly higher payment is often the safer choice.
Also consider the total cost of ownership, not just the sticker price. A cheaper car with high insurance premiums or poor fuel economy may cost more over time than a slightly more expensive car that is cheaper to insure and maintain. Research reliability ratings and repair costs for the models you are considering. If you are buying used, get a vehicle history report and have a mechanic inspect the car before you commit. These steps protect you from inheriting someone else's problems.
If you are unsure where to start, our guide on the best credit unions for first-time car buyers can help you compare lending options and understand what to look for in a lender. Credit unions sometimes offer more favorable terms for members, especially those with limited credit history. Comparing options before you apply is part of a smart pre-application strategy.
Understand How the Application and Approval Process Works
Many first-time buyers assume they should walk into a dealership and let the finance manager handle everything. That can work, but it often means you have less control over which lenders see your application and what terms you are offered. A better approach is to get preapproved or prequalified before you shop. Preapproval gives you a clear idea of your budget and shows sellers you are a serious buyer. It also gives you leverage when negotiating.
A connection service like AutoTitleLoan can match you with lenders and dealers who work with first-time buyers, bad credit, and no credit situations. Instead of applying to multiple lenders one by one, you can submit one request and let the service route it to participating partners. This saves time and reduces the number of hard inquiries on your credit report. Just remember that a connection service is not a lender. It connects you with options, and you still need to review each offer carefully.
When you receive offers, compare the annual percentage rate (APR), not just the monthly payment. The APR includes interest and fees, so it gives you a clearer picture of the true cost of the loan. Check the loan term, the down payment requirement, and any prepayment penalties. If an offer seems too good to be true, read the fine print. A reputable lender will explain the terms clearly and give you time to review them.
Review Your Insurance Options Early
You cannot drive a car without insurance, and lenders require it. Before you apply for a loan, get quotes for the vehicles you are considering. Insurance costs vary widely based on the car's make and model, your age, your driving record, and where you live. A sports car will cost more to insure than a sedan with safety features. If you are a first-time driver, you may qualify for discounts by completing a defensive driving course or by staying on a parent's policy if that is an option.
Knowing your insurance costs helps you set a realistic budget and avoid surprises at the dealership. Some lenders require specific coverage limits, such as comprehensive and collision coverage. If you choose a cheaper liability-only policy, you may not meet the lender's requirements. Check with your insurance agent before you finalize your loan to make sure you have the right coverage in place.
Prepare for the Credit Inquiry and Terms
When you apply for a car loan, the lender will run a hard credit inquiry. This can temporarily lower your score by a few points, but the impact is usually small and short-lived. If you apply to multiple lenders within a short window, most scoring models treat those inquiries as a single event, so you are not penalized for shopping around. However, you should avoid applying for credit cards or other loans during this time, as that can complicate your approval.
Once you receive an offer, read the terms carefully. Look for the interest rate, the loan term, the monthly payment, and any fees. Ask about the total cost of the loan over its life. If you have a co-signer, make sure they understand the terms too. A co-signer is legally responsible for the loan if you cannot pay, so this is not a casual favor. The pre-application checklist for first-time car loan should include a conversation about expectations and responsibilities.
If you are denied, do not give up. Ask the lender why and what you can do to improve your application. Sometimes a larger down payment or a co-signer can turn a denial into an approval. Other times, you may need to work on your credit for a few months before applying again. A denial is not the end of the road. It is information you can use to strengthen your next application.
Final Steps Before You Submit Your Application
You have checked your credit, built a budget, saved for a down payment, gathered your documents, and researched insurance. Now it is time to put it all together. Before you submit your application, do a final review. Make sure your documents are current and legible. Confirm that your income information matches your bank statements. Double-check your budget to ensure the monthly payment fits comfortably. And have a clear idea of the maximum price you are willing to pay.
It also helps to write down your goals. Are you looking for the lowest possible rate, or is a lower monthly payment more important? Do you plan to keep the car for many years, or do you want the flexibility to upgrade sooner? Your answers will guide which offers you accept. There is no single right answer, but being clear about your priorities makes the decision easier.
Finally, give yourself permission to walk away. If an offer does not feel right, you are not obligated to accept it. A reputable lender or dealer will respect your decision. The goal is to find a loan that helps you get the car you need without creating financial stress. With a solid pre-application checklist for first-time car loan, you can approach the process with confidence and drive away knowing you made an informed choice.