Minimum Income Required for a Bad Credit Auto Loan
See typical income thresholds for bad credit auto loans and learn how lenders weigh stability and debt-to-income to approve you.
By Nicole Thompson
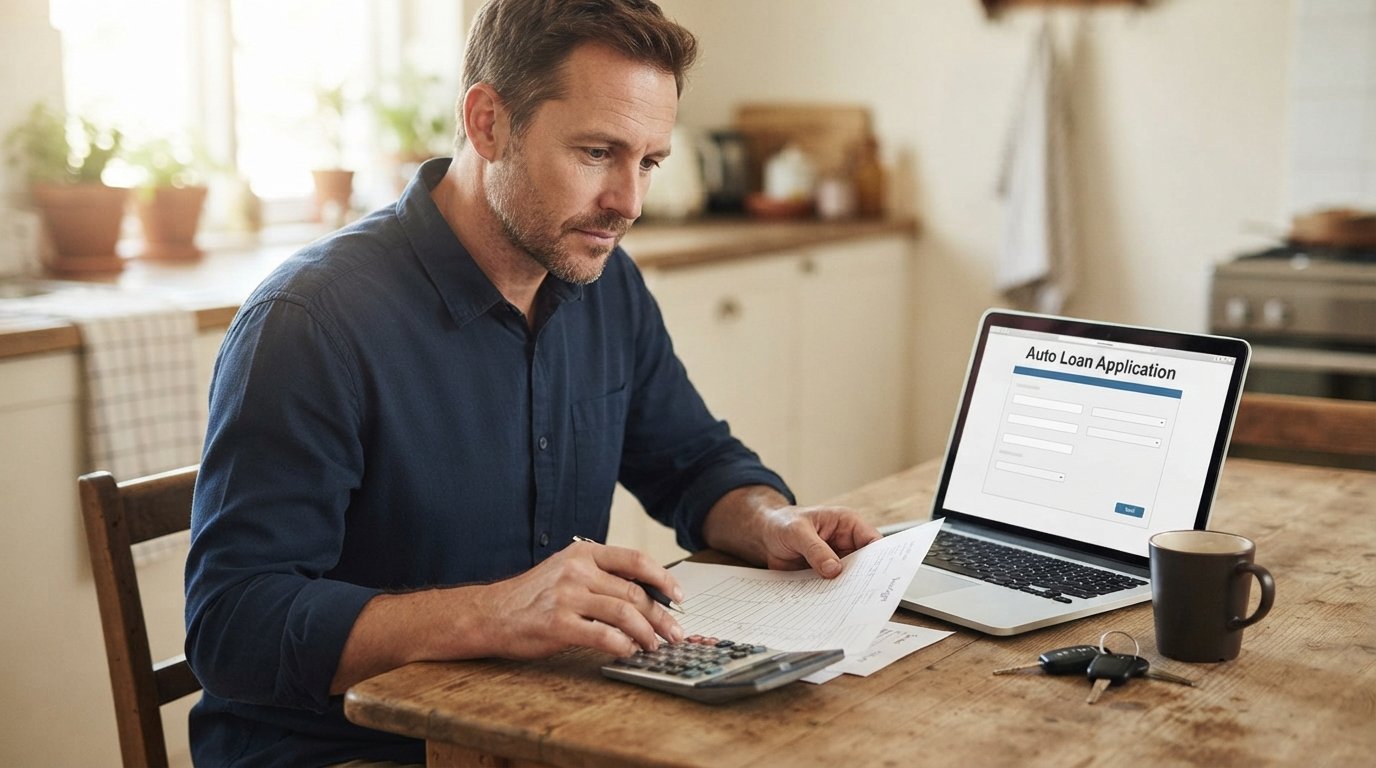
If you have bad credit and you need a car, the question that keeps you up at night is simple: how much do I need to earn to get approved? You have probably seen ads promising approval at any income level, and you have probably also been turned down by a lender who never explained why. The truth is that there is no single magic number, but there are clear patterns in how lenders evaluate income for bad credit auto loans. Understanding those patterns can save you weeks of frustration and help you walk into a dealership or apply online with realistic expectations.
At StartAutoLoan.com, we connect borrowers with bad credit, no credit, and past bankruptcies to a network of lenders and dealers who specialize in these situations. That gives us a front row seat to what actually gets approved. In this guide, we break down the minimum income required for a bad credit auto loan, how lenders weigh income against your proposed payment, why stability often beats a bigger paycheck, and how to present variable or multiple income sources in the best possible light.
Typical Minimum Gross Income Thresholds Lenders Use
Most lenders that work with bad credit borrowers do not publish a hard minimum income number, but industry practice gives us reliable ranges. For a standard used car loan, many subprime lenders look for a minimum gross monthly income of around $1,500 to $2,000. Some will go lower, sometimes as low as $1,200 per month, but those programs usually come with higher interest rates, larger down payment requirements, or both. On the higher end, lenders financing newer or more expensive vehicles may want to see $2,500 or more per month.
These figures refer to gross income, meaning your pay before taxes and deductions. Lenders generally care about gross because it is easier to verify through pay stubs and because it gives a consistent baseline across applicants. If you are paid hourly, lenders will often annualize your income based on your hourly rate and expected hours. If you are salaried, they will use your base salary, though overtime and bonuses may count if they are documented and consistent.
It helps to think in terms of a range rather than a single threshold. A borrower earning $1,800 per month with a small car payment request might qualify easily, while a borrower earning $3,000 per month with a large payment request could be declined. The minimum income is not a fixed gate; it is one variable in a larger calculation. That calculation is where the next section comes in.
How Income Is Weighed Against the Proposed Payment
Lenders do not evaluate income in isolation. They compare your income to your debts, including the new car payment you are asking them to approve. The most common tool for this is the debt-to-income ratio, or DTI. Your DTI is your total monthly debt payments divided by your gross monthly income. For bad credit auto loans, many lenders prefer a DTI below 45 to 50 percent, though some subprime programs allow higher ratios if other factors are strong.
Here is a simple example. Suppose your gross monthly income is $2,500. You have a $300 rent payment, a $150 minimum credit card payment, and a $200 personal loan payment. That is $650 in existing debt. If you want a car loan with a $400 monthly payment, your total monthly debt becomes $1,050. Divide $1,050 by $2,500 and you get a DTI of 42 percent. That is within the range many lenders accept. If your income were $2,000 instead, the same debts would produce a DTI of 52.5 percent, which could push you into a higher risk tier or result in a denial.
This is why the minimum income required for a bad credit auto loan depends heavily on the size of the loan you want. A borrower seeking a $10,000 loan for a used car has a much lower income hurdle than a borrower seeking a $35,000 loan for a new truck. Lenders also consider the loan-to-value ratio, which compares the loan amount to the vehicle value. A smaller loan relative to the car value reduces the lender's risk and can make a lower income acceptable.
To improve your odds, consider these strategies before you apply:
- Choose a less expensive vehicle to lower your proposed payment and DTI.
- Make a larger down payment to reduce the loan amount and monthly payment.
- Pay down small debts before applying to improve your DTI.
- Avoid opening new credit accounts in the months before your application.
Each of these steps directly affects how lenders view your income relative to the loan. A borrower with $2,000 monthly income and a $250 car payment looks very different from one with the same income and a $500 payment. The minimum income is not just about how much you earn; it is about how much you earn compared to what you are asking to borrow.
Why Stability Can Matter More Than the Amount
You might assume that a higher income always wins. In bad credit lending, that is not always true. Lenders are managing risk, and one of the biggest risks is that a borrower loses their job or their income source disappears. A borrower earning $3,000 per month from a job they started two months ago may be seen as riskier than a borrower earning $1,800 per month who has been with the same employer for three years.
Employment history is a major factor in subprime auto loan approvals. Many lenders want to see at least six months to a year with the same employer, or at least in the same line of work. If you are self-employed, they may want to see two years of tax returns. If you are retired, they will look at Social Security, pension, and investment income. If you receive disability payments, those can count as stable income if documented properly.
Stability also applies to your housing situation. Lenders often check how long you have lived at your current address. A long tenure at one address signals stability, while frequent moves can raise questions. This does not mean you cannot get approved if you have moved recently, but it does mean you should be prepared to explain your situation and provide documentation.
Here is the takeaway: if you have a choice between a higher-paying job you just started and a lower-paying job you have held for years, the lower-paying job may actually help you more in a bad credit auto loan application. Lenders want to see that your income is reliable enough to make payments month after month. A steady $1,800 per month is often more attractive than an uncertain $3,000 per month.
How to Present Variable or Multiple Income Sources
Not everyone earns a predictable salary. If you are paid hourly with fluctuating hours, work multiple part-time jobs, drive for a rideshare company, or earn commissions and tips, you may worry that lenders will not count your income. The good news is that many lenders will consider variable and multiple income sources, but you need to document them carefully.
For hourly workers with fluctuating hours, lenders typically average your income over a period of months, often three to six months. They may look at your year-to-date earnings and divide by the number of months worked. If your hours vary seasonally, be prepared to explain the pattern. For multiple jobs, you can combine income from all sources as long as each is documented. This means pay stubs, bank statements showing direct deposits, or letters from employers.
Self-employment income requires more documentation. Lenders usually want to see tax returns for the past two years, along with recent bank statements and possibly a profit and loss statement. If your self-employment income has been growing, that can work in your favor, but you need to show the trend clearly. For gig workers, platforms like Uber, Lyft, DoorDash, and Instacart provide earnings statements that can serve as proof of income. Some lenders are more comfortable with gig income than others, so it helps to work with a connection service that understands these income types.
Here is a practical framework for presenting variable income:
- Gather at least three months of income documentation, including pay stubs, bank statements, and any 1099 forms.
- Create a simple summary sheet showing your average monthly gross income from all sources.
- Write a brief explanation of any fluctuations, such as seasonal work or a recent job change.
- Be consistent: make sure the income you list on your application matches your documentation.
Lenders appreciate organization. A borrower who arrives with clear documentation and a straightforward explanation is easier to approve than one who leaves the lender guessing. If you are working with a dealer or a connection service, ask them what documentation they recommend for your specific income situation. For more guidance on navigating approval without a cosigner, see our guide on auto loans with bad credit and no cosigner.
Other Factors That Influence Income Requirements
Income is only one piece of the approval puzzle. Lenders also look at your credit history, your down payment, the age and mileage of the vehicle, and your overall financial profile. A larger down payment can offset a lower income because it reduces the amount the lender is risking. A newer vehicle with lower mileage may qualify for better terms, which can lower your payment and make your income go further.
Your credit score also matters, even in subprime lending. Borrowers with scores in the low 500s may face higher income requirements or larger down payment requirements than those in the 600s. If your credit is very poor, you may need to demonstrate more stability in other areas, such as a long employment history or a solid rental history. Some lenders also consider alternative data, such as utility payment history, when evaluating thin credit files.
It is also worth noting that different lenders have different appetites. A bank might decline you while a credit union or a specialized subprime lender approves you with the same income. This is why applying through a connection service can be helpful: it gives you access to multiple lenders who each evaluate your profile differently. At AutoTitleLoan, for example, borrowers can explore financing options even after traditional lenders have said no. The more options you have, the better your chances of finding a lender whose income requirements match your situation.
Steps to Take If Your Income Is Below the Typical Minimum
If your income falls below the ranges we discussed, do not give up. There are still paths to approval. The first step is to consider a cosigner. A cosigner with good credit and stable income can significantly strengthen your application and may allow you to qualify with a lower income. However, a cosigner takes on real financial risk, so this decision should be made carefully and with clear communication.
Another option is to increase your down payment. A larger down payment reduces the loan amount and the monthly payment, which lowers the income needed to qualify. If you can save even a few hundred dollars more, it can make a difference. You can also look at less expensive vehicles. A reliable used car with a lower price tag may be easier to finance than a newer model, even if it has higher mileage.
Finally, consider waiting and improving your financial profile. Paying down debts, staying at your job for a few more months, and saving for a down payment can all improve your chances. If you need a car sooner, a connection service can help you find lenders who work with lower incomes and are willing to take a chance on borrowers with bad credit. The key is to be honest about your income and to provide clear documentation. Lenders are more willing to work with borrowers who are transparent and organized.
Understanding the minimum income required for a bad credit auto loan is about more than hitting a number. It is about showing lenders that your income is stable, documented, and sufficient relative to the payment you are requesting. By focusing on stability, keeping your DTI in check, and presenting your income clearly, you can improve your odds of approval even with imperfect credit. And if you are ready to explore your options, StartAutoLoan.com can connect you with lenders and dealers who specialize in bad credit auto financing, giving you a real path forward.