How to Buy a Car With a Co-Signer: Step by Step
Follow these steps to buy a car with a co-signer, from preparing documents to protecting the co-signer's credit and refinancing later.
By Marcus Hayes
You have found the car you want. You have negotiated a price you can live with. Then the finance manager runs your credit and delivers the news: your application was declined, or the interest rate offered is far higher than you expected. For millions of buyers with thin credit files, past bankruptcies, or a few missed payments in the rearview mirror, this moment feels like a dead end. It is not. A co-signer can turn a rejection into an approval, often within the same afternoon, and it can save you thousands of dollars in interest over the life of the loan. The catch is that adding a co-signer is not a casual favor. It is a legal contract that ties another person's credit and finances to your car payment for years. Understanding exactly how the process works, from the first conversation with your co-signer to the moment the loan is paid off, protects both of you. This guide walks through how to buy a car with a co-signer step by step, including the documents you will need, the conversations you should have before you ever walk into a dealership, and the mistakes that trap well-meaning families in financial strain.
What a Co-Signer Actually Does on a Car Loan
A co-signer is a second person who agrees to be equally responsible for your auto loan. The lender evaluates both credit profiles together, which means your co-signer's strong credit history, lower debt-to-income ratio, and steady payment record can compensate for gaps in your own file. The co-signer does not need to be on the title in most states, though some lenders and dealers require it, and the co-signer does not drive the car. What the co-signer does is promise to pay the loan if you stop paying. That promise appears on their credit report as a new installment account, affects their debt-to-income ratio when they apply for their own loans, and remains in place until the loan is refinanced, paid off, or the lender agrees to release them.
This is why the decision matters so much. A co-signed auto loan can help a first-time buyer establish credit and secure a rate that is several percentage points lower than a subprime offer. It can also damage the co-signer's credit if payments arrive late, and it can strain relationships if the arrangement is not clearly discussed upfront. Before you ask anyone to sign, be honest about your budget, your job stability, and your plan for making every payment on time. If you are still building your credit profile, resources like the first-time car buyer auto loan guide can help you understand what lenders look for and how to strengthen your application before you add a co-signer to the mix.
Step 1: Confirm That a Co-Signer Is the Right Move
Not every declined application needs a co-signer. Sometimes the problem is the loan amount, the age of the vehicle, or the specific lender's underwriting rules. Before you recruit a family member, review your situation carefully. A co-signer is most useful when your credit score is low, your credit history is short, or your income alone does not satisfy the lender's debt-to-income requirements. It is less useful when the issue is a vehicle that is too old for standard financing or a loan request that exceeds typical approval limits.
You should also consider alternatives. A larger down payment reduces the amount financed and can push an approval through without a second signature. Choosing a less expensive vehicle, or one that is a few years newer with lower mileage, can also change the lender's decision. If you have been rejected by multiple traditional lenders, a connection service that works with a network of lenders specializing in challenged credit may be able to find an approval without involving a co-signer at all. StartAutoLoan.com, for example, is an independent platform that matches borrowers with participating dealers and lenders, including options for bad credit, no credit, and past bankruptcies. It is not a direct lender, and there is no obligation to accept any offer, but it can show you what is available before you ask someone to co-sign.
If you do decide a co-signer is necessary, make the decision with clear eyes. The ideal co-signer has a credit score in the mid-700s or higher, a stable income, low existing debt, and a long-standing relationship with you built on trust. They should also understand the full scope of what they are signing.
Step 2: Have the Hard Conversation Before You Shop
The worst way to ask for a co-signer is in the dealership finance office with a salesperson waiting. The best way is at a kitchen table, weeks before you plan to buy, with documents and a repayment plan in hand. Your co-signer deserves to know the loan amount, the expected interest rate, the monthly payment, the loan term, and what happens if you miss a payment. They also deserve to know why your own credit is not sufficient and what you are doing to improve it.
Come prepared with a written summary. Include your monthly income, your rent or mortgage payment, your other debts, and the amount you can comfortably pay toward a car each month. Show that you have budgeted for insurance, fuel, maintenance, and registration, not just the loan payment. If you have a steady job and a savings cushion, say so. If your income is variable, explain how you will handle lean months. Transparency now prevents resentment later.
You should also discuss boundaries. Will the co-signer have access to the loan account to monitor payments? Will you send them a screenshot of each payment confirmation? What happens if you lose your job? What is the plan for refinancing the loan into your name alone once your credit improves? These questions feel uncomfortable, but they are far less uncomfortable than a repossession or a damaged relationship.
Step 3: Gather the Documents Both of You Will Need
Auto lenders require documentation from every borrower on the application, including co-signers. Missing paperwork is the most common reason an approval stalls, so collect everything before you visit a dealership or submit an online application. The exact list varies by lender, but most will ask for the following:
- Government-issued photo ID for both the primary borrower and the co-signer
- Proof of income, such as recent pay stubs, W-2s, or bank statements showing direct deposits
- Proof of residence, such as a utility bill, lease agreement, or mortgage statement
- Social Security numbers and dates of birth for both parties
- Insurance information, including the policy number and coverage limits, once a vehicle is selected
If you are self-employed, expect to provide additional documentation such as tax returns or profit-and-loss statements. If you have a past bankruptcy, have your discharge paperwork ready. Lenders that work with challenged credit often want to see that the bankruptcy is behind you and that you have re-established some positive credit since then.
Keep digital copies of everything in a secure folder so you can upload them quickly. If you are applying through an online connection service, you will typically fill out one form and have your information shared with participating dealers or lenders. That process moves faster when your documents are already organized.
Step 4: Shop for the Loan and the Car Together
Many buyers make the mistake of choosing a car first and then scrambling for financing. When a co-signer is involved, the smarter sequence is to understand your financing options before you fall in love with a specific vehicle. Different lenders have different rules about vehicle age, mileage, loan-to-value ratios, and maximum terms. A lender that approves a three-year-old sedan with 40,000 miles may decline a ten-year-old truck with 120,000 miles, even with a strong co-signer.
Start by getting preapproved. A preapproval tells you the maximum amount you can borrow, the rate you qualify for, and the term the lender is willing to offer. It also gives you negotiating power at the dealership because you are effectively a cash buyer up to that limit. When you apply, include your co-signer on the application from the beginning. Adding a co-signer later can trigger a second credit pull and delay the process.
Compare offers from multiple sources. Credit unions often offer competitive rates for co-signed loans, especially if the co-signer is an existing member. Banks, online lenders, and dealer-arranged financing are also options. Pay attention to the annual percentage rate, not just the monthly payment, because a longer term can lower the payment while increasing the total interest you pay. If you are unsure what rate you should expect, a loan calculator can help you see how different terms affect the total cost.
Step 5: Submit the Application and Review the Offers
Once you have selected a vehicle and a lender, you will complete a full credit application. Both you and your co-signer will need to consent to a credit check. The lender will verify income, employment, and residence, and may ask for additional documentation. This stage usually moves quickly, often within a day or two, but it can take longer if the lender needs to clarify something.
When the offers come back, read them carefully. You are looking for the interest rate, the term length, the monthly payment, and any fees. You should also confirm whether the loan includes gap insurance, extended warranties, or other add-ons that increase the amount financed. Some of these products are useful, but they should be evaluated on their own merits, not bundled into the deal without discussion.
If the offer is not what you expected, you can negotiate. Ask the lender or dealer if a larger down payment would reduce the rate. Ask whether a shorter term is available at a lower rate. If the co-signer has a strong credit profile, make sure the lender is actually using it to your advantage. Occasionally, a dealership will submit an application to a lender that does not consider co-signer credit fully, resulting in a higher rate than necessary. Do not be afraid to walk away and try another lender.
Step 6: Sign the Paperwork and Protect the Co-Signer
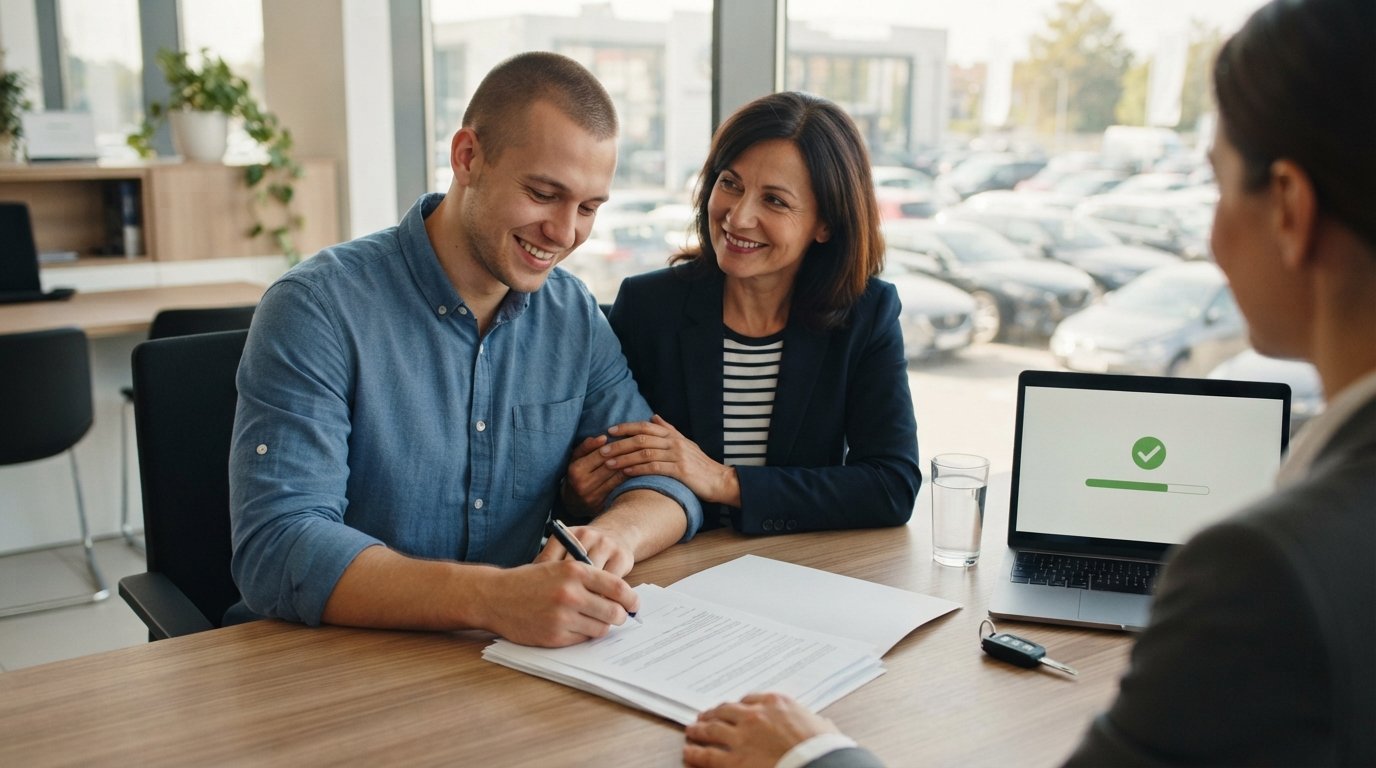
The signing appointment is the final step, but it is not a formality. Both you and your co-signer should read every document before signing. Pay attention to the retail installment sales contract, the truth-in-lending disclosure, and any optional product agreements. Confirm that the vehicle identification number on the contract matches the car you are buying, and that the loan amount, rate, and term match what you agreed to.
After the loan is funded, the real work begins. Set up automatic payments from an account you control, and make sure the first payment is scheduled well before the due date. Late payments are the single biggest risk to your co-signer's credit and your relationship. If you are ever unable to make a payment, tell your co-signer immediately, before the lender reports it as late. Most lenders offer a grace period, but it is short and not guaranteed.
You should also plan for the eventual release of your co-signer. Refinancing the loan into your name alone is the cleanest way to do this. It usually requires that your credit score and income have improved enough to qualify on your own, and that the vehicle is worth enough to satisfy the lender's loan-to-value requirements. Start monitoring your credit and building a payment history as soon as the loan begins, so you can refinance within a year or two. If you financed through a connection service, you may be able to return to that platform to explore refinance options when the time comes.
Common Mistakes That Sink Co-Signed Car Deals
The most common mistake is choosing the wrong co-signer. A co-signer with a credit score only slightly higher than yours may not improve the approval odds enough to justify the risk. A co-signer with a high score but a high debt-to-income ratio may actually hurt the application. The best co-signer has good credit, stable income, and low existing obligations.
Another mistake is failing to disclose the co-signer's involvement to your insurance company. Some insurers require that all household members, including co-signers, be listed on the policy, even if they do not drive the car. If you are unsure how co-signing affects your insurance requirements, resources such as NewAutoInsurance provide consumer guidance on coverage options and how to compare policies, which can help you avoid gaps in protection after the purchase.
A third mistake is treating the co-signer as a silent partner. The co-signer has a legal right to know the status of the loan, and many lenders will send them statements or payment reminders. Keeping them informed is not just courteous; it protects both of you. If the relationship sours or communication breaks down, the lender will still expect payment from both parties.
Finally, avoid the temptation to stretch for a more expensive car simply because the co-signer's credit got you approved. A larger loan means a larger monthly payment, a longer repayment period, and more risk for everyone involved. Buy within your budget, make every payment on time, and treat the co-signer's trust as the valuable asset it is.
Buying a car with a co-signer is a team effort, and it works best when both people understand the rules, the risks, and the plan. Do the preparation before you shop, communicate honestly, and stay disciplined after the keys are in your hand. With the right co-signer and a clear strategy, you can get approved, build your credit, and eventually take over the loan on your own.