How to Budget for Car Insurance, Maintenance and Fuel
A practical guide to how to budget for car insurance, maintenance, and fuel so you can avoid surprise bills and keep your total car costs under control.
By Rachel Adams
Owning a car is one of the most useful and liberating purchases you can make, but the sticker price is only the start. Insurance premiums, routine maintenance, and fuel costs quietly drain hundreds of dollars from your bank account every month, and many drivers only notice the damage after an unexpected repair bill or a premium hike lands in their inbox. Learning how to budget for car insurance, maintenance, and fuel is the difference between cruising through the month with confidence and scrambling to cover costs you never saw coming.
This guide walks through a practical, numbers-based approach to planning for every recurring and irregular cost that comes with vehicle ownership. You will learn how to estimate your true monthly driving expenses, build a budget that survives real life, and find savings in places most drivers overlook. Whether you are financing a new car or keeping an older one on the road, these strategies apply to almost every situation.
Why Car Ownership Costs More Than You Think
The average American household spends well over ten thousand dollars a year on transportation, and a large chunk of that comes from costs that have nothing to do with the car payment itself. Insurance, fuel, and maintenance are what financial planners call the silent budget killers: they are predictable in the long run but irregular in the short term, which makes them easy to ignore until they become urgent.
The problem is not that these costs are enormous on any given day. It is that they arrive on different schedules. Insurance bills might come every six months, fuel costs hit every week, and a brake job can strike without warning. When you manage each expense reactively, you never build momentum, and one bad month can undo months of careful spending.
Budgeting solves this by turning irregular costs into a steady, predictable monthly number. Instead of hoping you have enough cash when the bills arrive, you set aside a fixed amount every payday. That single shift in mindset is what separates drivers who feel in control from those who feel like their car owns them.
Start With Your Real Numbers
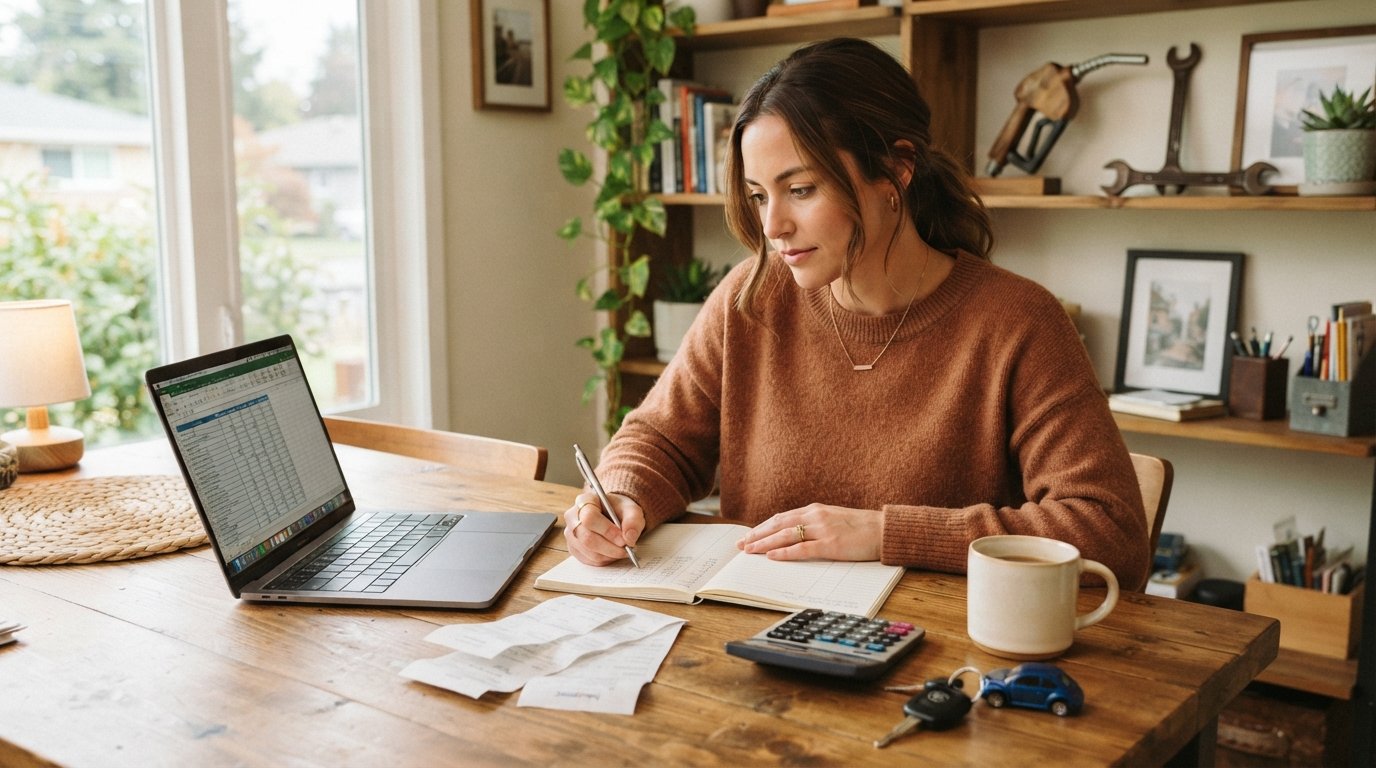
You cannot budget what you have not measured. Before you set a single dollar amount, spend one month tracking every expense related to your vehicle. Keep receipts, check your bank statements, and note the dates. Most people are surprised by how much they spend on fuel alone once they see it in writing.
Once you have a month of data, categorize your costs into three buckets: fixed, variable, and irregular. Fixed costs are the same every period, like a monthly insurance premium. Variable costs fluctuate, like fuel and tolls. Irregular costs arrive unpredictably, like tires, batteries, and major repairs. Each bucket needs a different budgeting strategy.
For a quick estimate, use these national averages as a starting point and adjust for your situation:
- Full coverage insurance: roughly $1,500 to $2,500 per year for a typical driver
- Fuel: about $150 to $250 per month for a mid-size car driven 12,000 miles a year
- Routine maintenance: around $500 to $900 per year for oil changes, filters, and inspections
- Wear items (tires, brakes, battery): about $600 to $1,200 every few years, or $200 to $400 annually when averaged
Add those numbers together and you are looking at roughly $4,000 to $6,000 per year, or $330 to $500 per month, before you even count the car payment. That is the figure your budget needs to absorb. If it feels high, do not panic: the next sections show how to bring each category down without sacrificing safety or coverage.
Budgeting for Car Insurance
Insurance is the most negotiable of the three big costs, yet most drivers set it and forget it. Premiums are based on factors you can influence, including your deductible, coverage limits, driving record, and even your credit-based insurance score in most states. Small adjustments can save hundreds of dollars a year.
Start by deciding how much risk you can realistically absorb. A higher deductible lowers your premium but means more out-of-pocket cost if you file a claim. A lower deductible costs more each month but protects you from a sudden large bill. Neither choice is universally right; it depends on how much cash you keep in your emergency fund.
Next, shop your policy every twelve months. Insurers quietly raise rates at renewal, and loyalty rarely pays. Getting three to five quotes takes an hour and often saves ten to twenty percent. Ask about every discount you qualify for, including safe driver, multi-car, multi-policy, low mileage, and good student discounts.
To turn insurance into a budget line item, divide your annual premium by twelve and set that amount aside monthly. If you pay in full instead of monthly, you often avoid installment fees, which can save five to ten percent. A dedicated savings account for insurance makes this painless and keeps the money out of reach until the bill arrives.
Budgeting for Maintenance and Repairs
Maintenance is the cost drivers underestimate most. A transmission replacement can cost several thousand dollars, and even routine service adds up quickly. The key is to treat maintenance as a subscription rather than an emergency. You know your car will need oil changes, tires, and eventually repairs, so plan for them the same way you plan for rent.
A simple approach is to set aside a fixed amount every month based on your car's age and mileage. Newer vehicles under warranty need less, while older high-mileage cars need more. A common rule of thumb is $50 per month for a newer car and $100 or more per month for a vehicle over eight years old or past 100,000 miles.
Staying ahead of scheduled maintenance also saves money. Skipping an oil change can lead to engine damage; ignoring worn brake pads can destroy rotors. Following the manufacturer's maintenance schedule in your owner's manual is the cheapest insurance policy you can buy. Keep a simple log of every service so you know what is coming next.
When a repair does arrive, get at least two quotes and ask whether aftermarket parts are available. Independent shops often charge significantly less than dealerships for identical work. If you are financing a car and worried about keeping up with payments alongside repairs, exploring options to refinance your auto loan could free up monthly cash for maintenance and other ownership costs.
Budgeting for Fuel
Fuel is the most visible recurring cost, which makes it the easiest to budget but also the easiest to overspend on. Your monthly fuel bill depends on three things: how far you drive, how efficient your car is, and what you pay per gallon. You can influence all three.
Start by calculating your actual miles per gallon. Fill your tank, reset your trip odometer, and drive normally until your next fill-up. Divide the miles driven by the gallons you added. That number, combined with your average miles driven per month and the current price per gallon, gives you a reliable fuel estimate.
Once you know your baseline, look for ways to reduce it. Combining errands, carpooling, and avoiding aggressive acceleration can improve fuel economy by ten to twenty percent. Keeping tires properly inflated and removing unnecessary weight from the trunk helps too. Apps that track gas prices in your area can save a few cents per gallon, which adds up over a year.
For budgeting purposes, set aside your estimated monthly fuel cost plus a small buffer for price spikes. Gas prices can swing dramatically in a short period, so a ten to fifteen percent cushion prevents a surprise at the pump from wrecking your monthly plan.
Building a Complete Monthly Car Budget
Now it is time to bring everything together into a single monthly figure. Add your car payment, insurance set-aside, maintenance set-aside, and fuel estimate. The total is your true cost of ownership, and it should be a line item in your household budget just like housing or groceries.
Here is a simple step-by-step method to build the budget:
- List every vehicle-related expense from the past twelve months and divide each by twelve.
- Add your monthly loan payment, if you have one.
- Add your monthly insurance set-aside.
- Add your monthly maintenance and repair set-aside.
- Add your estimated monthly fuel cost plus a ten percent buffer.
- Compare the total to your take-home pay and adjust if it exceeds fifteen percent of your income.
If the total feels unmanageable, look for the biggest lever. Refinancing a high-interest auto loan can reduce your payment substantially, especially if your credit has improved since you bought the car. Shopping insurance, downsizing to a more efficient vehicle, or moving closer to work are other options worth considering.
Automating the savings portion is the single most effective habit you can build. Set up an automatic transfer to a dedicated car account on payday. When the insurance bill or repair invoice arrives, the money is already there, and you never feel the pinch.
Handling Surprises Without Breaking Your Budget
Even the best budget cannot predict everything. A hailstorm, a deer on the highway, or a failed alternator can throw your plan off course. That is why an emergency fund specifically for your car matters. Aim for at least one thousand dollars, and ideally enough to cover your insurance deductible plus one major repair.
If you cannot fund that cushion immediately, build it gradually. Add twenty or thirty dollars to your monthly car budget until the fund reaches your target. Once it is full, redirect that money toward paying down your auto loan faster or saving for your next vehicle.
Review your budget every six months or whenever something changes: a new job, a move, a rate change, or a new driver in the household. Small adjustments keep the plan realistic and prevent the slow drift that turns a good budget into an abandoned one.
If you are still shopping for a vehicle or struggling to get approved, a service like how to get a $0 down car loan can help you understand financing options that leave room in your budget for insurance, fuel, and maintenance. Keeping those ownership costs in view from the start prevents the common mistake of buying more car than you can afford to operate.
Budgeting for car insurance, maintenance, and fuel is not about restriction. It is about replacing uncertainty with a plan. When you know what your car really costs, you can make confident decisions, avoid debt, and keep your vehicle running safely for years. Start with one month of tracking, build your categories, automate your savings, and adjust as life changes. Your future self, and your bank account, will thank you.