How to Budget for a Car Payment and Insurance Together
Build one combined vehicle budget before you shop: how to budget for a car payment and insurance together so a surprise premium never breaks your monthly plan.
By Rachel Adams
A car payment and an insurance premium are two separate bills, but they draw from the same monthly income, and that is where most budgets fall apart. Plenty of buyers calculate a loan payment they can afford in isolation, sign the paperwork, and then discover that the insurance quote, the fuel costs, and the first set of new tires push their total vehicle spending past what their paycheck can carry. The result is a monthly squeeze that follows them for years. The fix is to build one combined vehicle budget before you shop, not after, so the payment and the premium are planned as a single number rather than two surprises.
This guide walks through a practical method for how to budget for a car payment and insurance together, including the percentage-of-income guideline that keeps total ownership costs sustainable, realistic ways to estimate premiums before you have a VIN, the often-ignored costs that belong in the same budget, and the stress test that shows whether your plan survives an income interruption. The approach works whether you have strong credit, thin credit, or a past bankruptcy, and it works whether you are buying from a dealer lot or arranging financing through a connection service like StartAutoLoan.com.
Start With One Number, Not Two
The most common budgeting mistake is treating the loan and the insurance as unrelated line items. A buyer approves a $410 payment mentally, then gets a $240 insurance quote and decides to "figure it out later." Later never comes with a plan attached. The cleaner method is to decide on a single all-in vehicle figure first, then work backward to see which combination of car, loan term, and coverage fits inside it.
A widely used starting point is to keep total vehicle costs at or below 15 to 20 percent of your take-home pay. That range covers the loan payment, insurance, fuel, maintenance, registration, and tires. If your take-home pay is $4,200 per month, 15 percent is $630 and 20 percent is $840. Everything the car costs you in a typical month has to fit inside that band. Buyers with tight budgets, variable income, or high housing costs should aim for the lower end, while buyers with stable income and low debt can stretch toward 20 percent.
Here is how that total breaks down in practice for a $4,200 monthly take-home paycheck:
- Loan payment: $300 to $380, which supports roughly a $16,000 to $20,000 loan at a mid-range rate over 60 months.
- Insurance: $120 to $180 for full coverage on a modest sedan with a clean record.
- Fuel: $100 to $140 depending on commute length and fuel economy.
- Maintenance and tires: $60 to $100 set aside monthly, even if nothing breaks this month.
- Registration and fees: $20 to $40 per month when the annual bill is divided by twelve.
Notice what happens when the loan payment creeps up. Every extra $50 on the payment has to come out of another line, and insurance and fuel are not flexible once the car is chosen. That is why the combined budget has to be set before you fall in love with a specific vehicle. If you are rebuilding credit and worried about approval, our guide on taking over car payments with no credit check explains why assuming someone else's loan rarely solves the underlying budget problem.
Estimate Insurance Before You Choose the Car
Insurance is the line item buyers most often guess wrong, and it varies more than people expect. Two cars with similar sticker prices can carry premiums that differ by $80 or more per month once you factor in repair costs, theft rates, safety ratings, and how expensive the vehicle is to replace. Getting a real quote takes about ten minutes and prevents the classic scenario where the payment fits but the premium does not.
The most reliable approach is to request quotes on the specific year, make, and model you are considering, ideally with a VIN if you have narrowed it down to one vehicle. Give the insurer your actual driving record and coverage preferences, not the optimistic version. Full coverage is usually required on financed vehicles, so price that, not the state minimum. If you are comparing two or three candidates, quote all of them; the difference often decides which car you should buy.
When you cannot get an exact quote yet, use these factors to estimate the direction and size of the premium:
- Vehicle type: Sports cars, large trucks, and luxury models carry higher premiums than compact sedans and small SUVs, often by 30 to 60 percent.
- Repair and theft risk: Vehicles with expensive parts, high theft rates, or poor crash ratings cost more to insure.
- Credit profile: In most states, insurers use credit-based insurance scores, and a lower score can raise premiums substantially, sometimes by hundreds of dollars per year.
- Coverage level: Raising deductibles from $500 to $1,000 lowers the premium, but only choose a deductible you could actually pay after an accident.
- Driver history: Tickets and at-fault accidents raise rates for years, so a clean record is worth protecting.
Credit deserves special attention for this audience. If your credit is damaged or thin, insurance quotes will often come back higher than you expect, which means the combined budget has to absorb both a higher loan rate and a higher premium. That double hit is exactly why the 15 to 20 percent rule matters: it forces you to leave room for both. Buyers who have been turned down elsewhere can explore bad credit auto loan options through StartAutoLoan.com's connection service, but the budget math stays the same regardless of where the loan comes from.
Add the Costs That Do Not Send a Bill Every Month
Fuel is the cost everyone remembers and maintenance is the cost everyone forgets. A car budget that covers only the loan and insurance is not a budget; it is two bills with a false sense of security attached. The monthly vehicle figure should include every recurring and predictable cost of keeping the car on the road.
Fuel is straightforward to estimate: divide your monthly miles by the car's real-world fuel economy, then multiply by the current price per gallon. If you drive 1,000 miles per month and the car returns 30 mpg at $3.50 per gallon, fuel runs about $117. Maintenance is less precise but still predictable in aggregate. Oil changes, brake pads, fluid services, and inspections average out to a real monthly cost even though they arrive in lumps. Tires are the biggest lump of all: a set of four can run $600 to $1,200 installed and last three to five years, which works out to $15 to $35 per month if you save for them instead of borrowing for them.
Registration, title fees, and state inspections are annual or biennial expenses that belong in the monthly plan as one-twelfth of the bill. Some states also levy personal property taxes on vehicles, which can be several hundred dollars per year on a newer car. Add these to the combined figure before you commit, because they arrive whether or not the loan payment feels comfortable that month.
A simple way to operationalize this is a sinking fund: open a separate savings account and transfer a fixed amount each payday for maintenance, tires, and registration. When the bill arrives, the money is already there. This turns irregular costs into a predictable monthly line and keeps a transmission repair from turning into a credit card balance.
Why a Longer Loan Term Is a Budget Trap
When the combined budget feels tight, the dealership's favorite solution is to stretch the loan term. Moving from 60 to 84 months can drop the payment by $80 to $100 per month on a typical loan, which often makes the difference between fitting and not fitting. The payment looks better, but the total cost gets worse in three ways.
First, longer terms usually carry higher interest rates, and the extra interest is charged on the balance for years longer. Second, depreciation outpaces the loan: after three years on an 84-month loan, many buyers owe more than the car is worth, which traps them if they need to sell or trade. Third, the longer you pay, the longer you must carry full coverage insurance on a vehicle that is losing value, so the insurance line stays high even as the car ages. A lower payment bought with a longer term is not a budget improvement; it is a budget deferral with interest attached.
A better response to a tight budget is to adjust the vehicle, not the term. Choosing a slightly older or less expensive car lowers the payment, the insurance premium, and often the registration cost at the same time. Raising the down payment shrinks the loan and can eliminate the need for a longer term entirely. If you are set on a particular car and the numbers only work at 84 months, the honest conclusion is that the car does not fit the budget yet.
Stress-Test the Budget Before You Sign
A budget that works only in a perfect month is not a plan. Before committing, test the combined vehicle figure against three scenarios that happen to real people: a reduction in income, an unexpected repair, and a jump in insurance costs. Each test takes a few minutes and reveals whether the plan has any cushion.
The income interruption test is the most important. Ask what happens if your take-home pay drops by 20 percent for three months, whether from a job change, reduced hours, or a medical event. If the combined vehicle cost would consume more than about a quarter of the reduced income, the budget is too tight. The repair test asks whether you could cover a $1,000 repair without borrowing; if not, the sinking fund needs to be funded before you buy, not after. The insurance test asks what happens if your premium rises 20 percent at renewal, which is common after a claim or a credit change.
There is also a practical protection worth knowing about: many lenders offer payment relief programs or deferment options for temporary hardship, but they are easier to use when you ask early. If you are already exploring alternative financing paths, platforms that connect borrowers with lenders, such as AutoTitleLoan.com, can be one place to compare options, though the stress test above is what actually protects you. The point is to know your fallback before you need it.
Put the Budget on Paper and Follow It
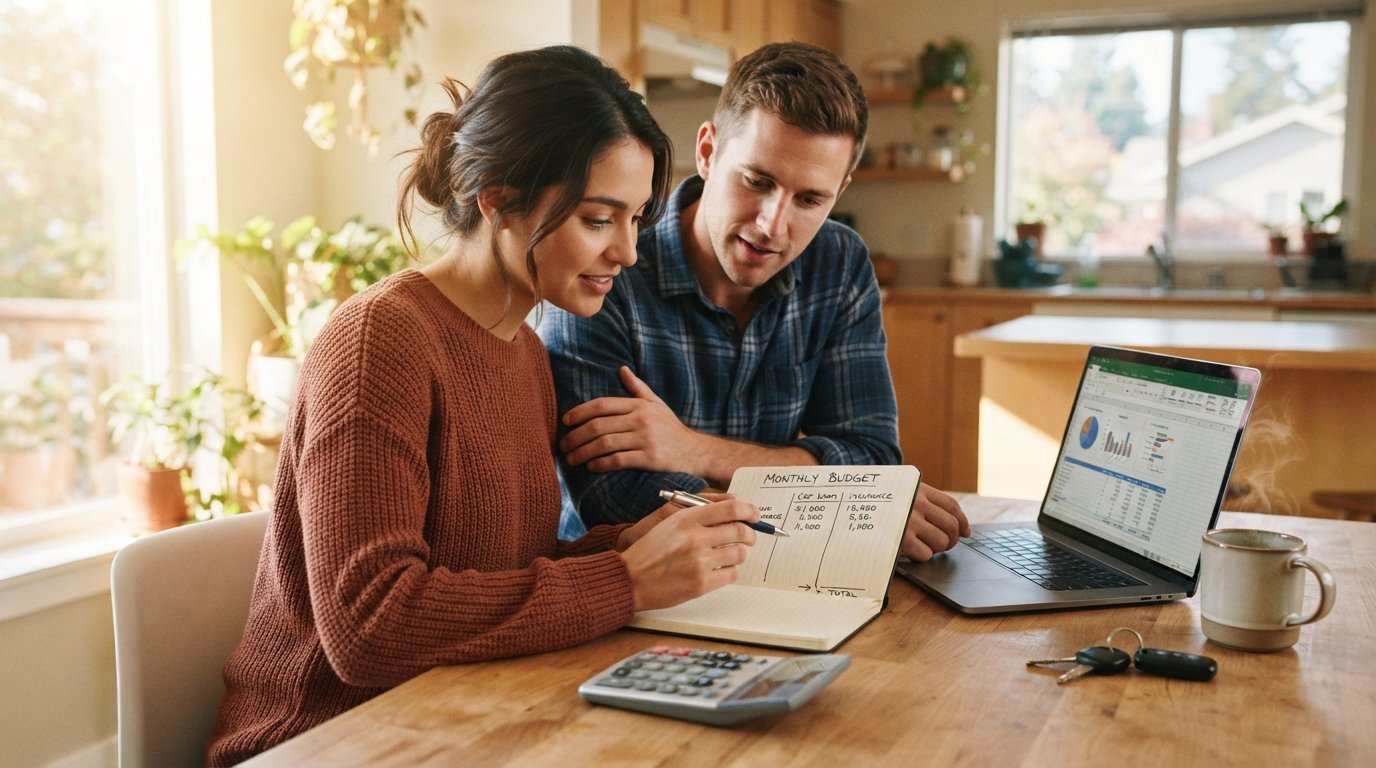
Once the numbers are set, write them down in one place: the target all-in monthly figure, the loan payment, the insurance premium, the fuel estimate, the maintenance sinking fund, and the registration set-aside. Compare the total against the 15 to 20 percent guideline and against your actual take-home pay. If the total exceeds 20 percent, adjust the vehicle or the down payment before you shop, not after you have a dealer in front of you.
When you are ready to apply, having the budget already done makes the financing conversation much easier. You know your ceiling, you know which cars fit it, and you can walk away from any offer that pushes the combined cost past it. StartAutoLoan.com's streamlined application connects you with participating lenders and dealers who work with a range of credit profiles, and arriving with a clear combined budget means you can evaluate every offer against a number you trust instead of a payment that sounds manageable in the moment.
The buyers who stay comfortable after signing are not the ones who negotiated the hardest; they are the ones who planned for the payment and the premium together, left room for fuel and tires, and tested the plan against a bad month before it arrived. Do that math first, and the car becomes a tool you own rather than a bill that owns you.