How Dealers Arrange Bad Credit Auto Financing
Dealers arrange bad credit auto financing by matching your profile to subprime lenders, structuring the deal, and negotiating terms. Here is how the process works.
By Brittany Walker
Walking into a dealership with bad credit can feel like walking into a test you already failed. You expect the rejection, the awkward silence, or the sky-high interest rate that makes the car you need feel impossibly out of reach. Yet every day, dealerships across the country arrange financing for buyers with credit scores in the 500s, recent bankruptcies, repossessions, and even no credit history at all. The process is not magic, and it is not charity. It is a structured, relationship-driven system that dealers use to match high-risk borrowers with lenders willing to take a calculated chance. Understanding exactly how that system works puts you in a much stronger position to negotiate, prepare, and avoid the traps that cost bad credit buyers thousands of dollars over the life of a loan.
What Bad Credit Auto Financing Really Means
Bad credit auto financing is not a single product. It is an umbrella term for any loan approval granted to a borrower whose credit profile falls outside the standard underwriting guidelines most banks use. Traditional lenders rely heavily on credit scores, income stability, and past repayment history. When those factors are weak, the loan gets declined by the bank but not necessarily by the dealership. Dealers know that a significant portion of the buying public has damaged credit, and they have built entire business channels around serving those customers profitably.
This financing is often called subprime lending, and it operates on a different risk model. Instead of rejecting a borrower outright, subprime lenders charge higher interest rates to compensate for the increased chance of default. They may also require larger down payments, shorter loan terms, or proof of stable income. The dealer's job is to find the lender whose specific guidelines match your specific situation, a process that involves far more than simply running your credit and handing you a number.
For consumers, the key takeaway is that bad credit does not mean no financing. It means financing on different terms. The dealer's ability to arrange that financing depends on relationships, technology, and an understanding of which lenders specialize in which credit profiles. If you have been turned down elsewhere, a dealer with the right lender network may still be able to get you approved.
The Dealer's Role: Matchmaker, Not Lender
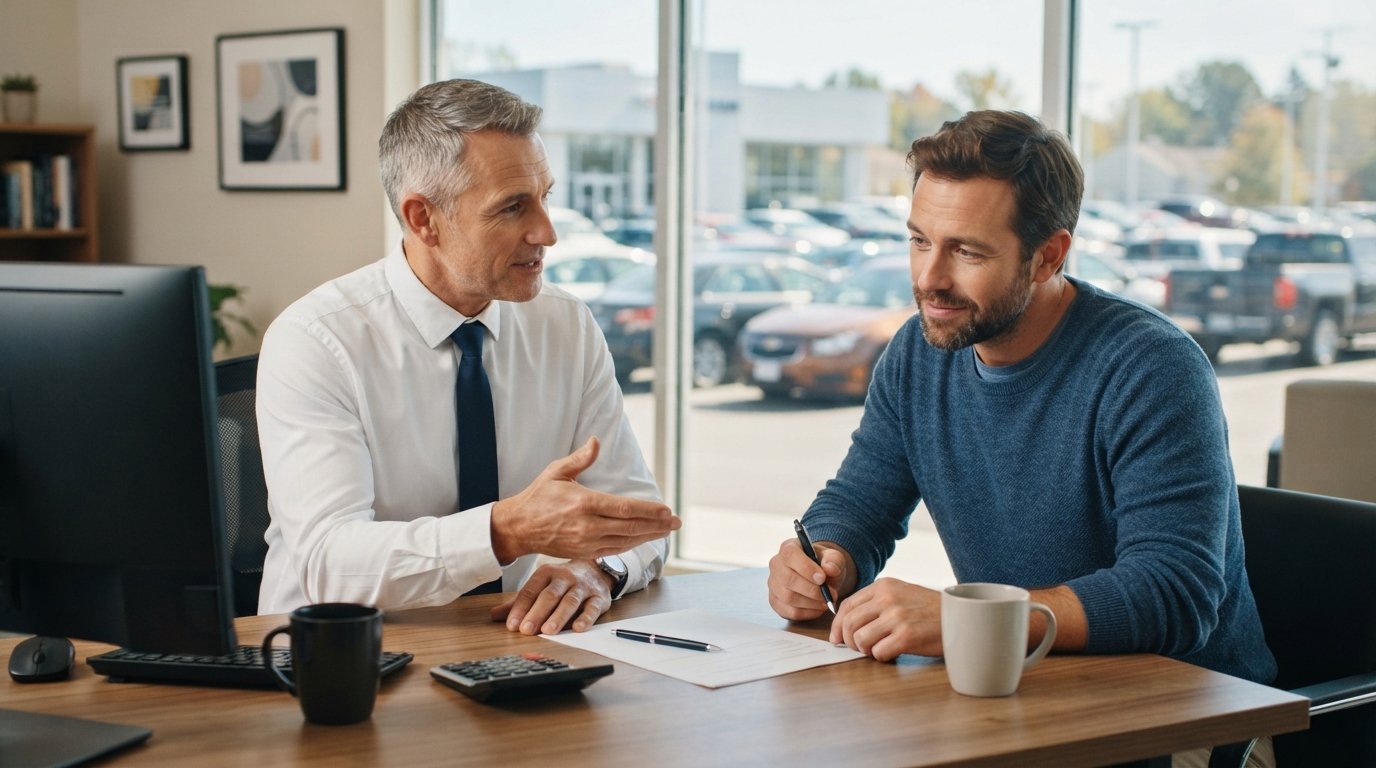
One of the most common misconceptions about dealership financing is that the dealer is lending you the money. In almost every case, the dealer is not the lender. The dealer is a middleman, sometimes called an intermediary or a finance facilitator, that connects you with a bank, credit union, or specialty finance company. The dealership's finance department, often led by a finance manager or a team of finance managers, is responsible for submitting your application to multiple lenders and negotiating the best possible terms.
This distinction matters because it explains why the dealer's relationships are so valuable. A dealership that has been in business for years has established lines of communication with dozens of lenders, including national banks, regional credit unions, captive finance companies owned by automakers, and subprime specialists. Each of these lenders has its own credit score cutoffs, income requirements, debt-to-income limits, and documentation standards. The finance manager's expertise lies in knowing which lender is most likely to approve a borrower with your exact profile, and how to present that application in the most favorable light.
According to industry data, franchised dealerships arrange financing for the vast majority of their customers, and a significant percentage of those loans fall into the subprime or non-prime category. This is not a niche service. It is a core part of the dealership business model. Dealers make money on the sale of the vehicle, but they also earn a fee from the lender for originating the loan, known as a dealer reserve or participation fee. That financial incentive is one reason dealers work hard to get approvals, though it is also a reason to stay alert for terms that benefit the dealer more than the buyer.
The Step-by-Step Process Dealers Use
When you apply for financing at a dealership, your application enters a workflow that is more systematic than most buyers realize. The finance manager does not simply guess which lender to call. There is a defined sequence of steps that begins the moment you hand over your driver's license and Social Security number, and understanding this sequence can help you anticipate what happens next and where you have leverage.
The first step is the credit pull. The dealership will access your credit report and score from one or more of the major bureaus. If you have bad credit, the report will also reveal the specific reasons: late payments, collections, charge-offs, bankruptcy, or repossession. The finance manager uses this information to classify your credit tier, which determines which lenders are even worth contacting. Some dealerships also use proprietary scoring models that combine your credit data with other factors like income and down payment to predict how likely you are to default.
Once your credit tier is identified, the finance manager moves to the second step: lender selection. This is where relationships come into play. The finance manager reviews the dealership's lender list and identifies the ones that accept your credit tier. In many cases, the dealership will submit your application to several lenders at once, a practice known as a shotgun or multi-lender submission. This allows the dealer to compare offers and present you with the best available terms. The lenders respond with approval, conditional approval, or decline, often within minutes to a few hours.
The third step is structuring the deal. Even when a lender approves you, the approval comes with conditions. The lender may specify a maximum loan amount, a minimum down payment, a maximum interest rate, or a required debt-to-income ratio. The finance manager then works with you and the sales team to structure a deal that satisfies the lender's conditions. This might mean adjusting the vehicle price, increasing your down payment, adding a co-signer, or selecting a different vehicle that fits the lender's collateral guidelines.
The fourth step is documentation and verification. Subprime lenders typically require more paperwork than prime lenders. You may need to provide proof of income, proof of residence, proof of insurance, and references. The finance manager collects these documents and submits them to the lender for final approval. If everything checks out, the lender funds the loan, and you drive away with the vehicle.
The final step is the funding and delivery process. The dealership receives the loan funds from the lender, minus any dealer reserve, and the vehicle is officially sold. You begin making payments to the lender, not the dealership, though the dealership may service the loan initially or set up automatic payments for you. This entire process can take anywhere from a few hours to a few days, depending on the lender and the complexity of your situation.
For a deeper look at what to expect when you pursue guaranteed approval options, our guide on guaranteed auto financing explains the promises and pitfalls in detail.
The Lender Network Behind the Scenes
The lenders that dealerships work with for bad credit financing fall into several categories, each with its own risk appetite and terms. Understanding these categories helps you anticipate the kind of offer you might receive and how to evaluate it.
- Captive finance companies: These are the financing arms of automakers, such as Ford Motor Credit, GM Financial, or Toyota Financial Services. They often have special programs for subprime borrowers, especially when the goal is to sell new or certified pre-owned vehicles. Their rates may be higher than prime rates but lower than what independent subprime lenders charge.
- Subprime specialty lenders: These companies focus exclusively on high-risk borrowers. They may operate nationally or regionally and often have relationships with thousands of dealerships. Their rates are typically the highest, but they are also the most willing to approve borrowers with severe credit issues, including recent bankruptcies.
- Credit unions: Many credit unions offer bad credit auto loans, though their guidelines vary widely. Some are more flexible than banks, especially for members with a history of on-time payments on other accounts. Credit unions often cap interest rates, which can protect borrowers from the most predatory offers.
- Online lenders and fintech companies: A growing number of online lenders specialize in subprime auto financing. They may partner with dealerships or work directly with consumers. Their application processes are often faster, but their rates and fees can be less transparent.
The dealer's finance manager knows which lenders are most likely to approve a given borrower, but that does not mean the dealer always chooses the best loan for you. Dealers may have preferred lenders that pay higher reserves, which creates a conflict of interest. As a borrower, you have the right to ask which lenders are being considered and to request a copy of the offers. In some states, dealers are required to disclose the markup on the interest rate, known as the dealer reserve, though this disclosure is not universal.
If you want to explore refinancing options after you have purchased a vehicle, platforms like CarLoanRefinancing.com offer educational resources and rate comparisons that can help you evaluate whether a better deal is available.
How Dealers Present Your Application to Lenders
The way a dealer presents your application can significantly influence whether you get approved and on what terms. Finance managers are trained to package applications in a way that highlights your strengths and mitigates your weaknesses. This is not necessarily dishonest, but it is a form of advocacy that you should understand.
One common technique is to emphasize compensating factors. If your credit score is low but you have a stable job with a long tenure, the finance manager will highlight that. If you have a large down payment, that reduces the lender's risk and may offset a recent late payment. If you have a co-signer with good credit, the finance manager will include that information prominently. Lenders evaluate the whole picture, not just the score, and the dealer's job is to make that picture as attractive as possible.
Another technique is to match the loan structure to the lender's preferences. Some lenders prefer shorter terms, while others are comfortable with longer terms if the vehicle is newer. Some lenders require a certain loan-to-value ratio, meaning the loan amount cannot exceed a certain percentage of the vehicle's value. The finance manager will adjust the deal structure, such as increasing the down payment or selecting a less expensive vehicle, to meet those requirements.
Dealers also use technology to streamline the submission process. Most dealerships use a dealer management system that connects directly to lender portals. This allows the finance manager to submit applications electronically and receive responses in real time. Some systems even allow for automated decisioning, where the lender's algorithm approves or declines the loan without human intervention. This speed can be an advantage for borrowers who need a quick answer, but it also means that the application must be accurate and complete from the start.
What Lenders Look For Beyond Your Credit Score
Bad credit lenders do not rely on your credit score alone. They consider a range of factors that collectively predict whether you will repay the loan. Understanding these factors can help you strengthen your application before you ever step into a dealership.
Income stability is one of the most important factors. Lenders want to see that you have a steady job with a consistent income history. A recent job change is not necessarily disqualifying, but a pattern of short-term employment or gaps in employment can raise red flags. Proof of income, such as pay stubs or bank statements, is almost always required for subprime loans.
Debt-to-income ratio is another key metric. This is the percentage of your gross monthly income that goes toward debt payments. Lenders typically prefer a DTI below 45 percent, though subprime lenders may allow higher ratios if other factors are strong. If your DTI is too high, the lender may require a larger down payment or a co-signer to reduce risk.
Down payment is a powerful compensating factor. A larger down payment reduces the amount financed and gives the lender more equity cushion if the vehicle needs to be repossessed. For bad credit borrowers, a down payment of 10 to 20 percent is often required, though some lenders will accept less if the credit profile is not severely damaged.
Payment history on other accounts, such as rent, utilities, or phone bills, can also be considered. Some lenders use alternative credit data to assess borrowers who have thin or damaged credit files. If you have a history of paying rent on time but your credit score is low due to medical collections, for example, that positive rental history may work in your favor.
Finally, the vehicle itself matters. Lenders have collateral guidelines that specify the maximum age and mileage of a vehicle they will finance. They also consider the loan-to-value ratio, which compares the loan amount to the vehicle's market value. A vehicle that is too old or has too many miles may be ineligible for financing, regardless of your credit.
Negotiating and Protecting Yourself
Once the dealer presents you with a financing offer, you are not obligated to accept it. This is a critical point that many bad credit buyers overlook. You have the right to negotiate the terms, ask questions, and even walk away if the deal does not work for you. The dealer wants to sell the car, and the finance manager wants to earn the reserve, so there is often room to negotiate, especially on the interest rate and add-on products.
Start by asking for a full breakdown of the deal. This includes the vehicle price, the trade-in value, the down payment, the loan amount, the interest rate, the term length, and the monthly payment. Ask which lender is offering the loan and what the dealer reserve is, if applicable. Some states require dealers to disclose this information, but even if they do not, you can ask. A transparent dealer will provide the details; a evasive one is a warning sign.
Be cautious of add-on products such as extended warranties, gap insurance, and paint protection. These products are often marked up significantly and can add thousands of dollars to your loan. While some add-ons, like gap insurance, can be valuable for subprime borrowers who owe more than the car is worth, you should understand the cost and whether it is required. In many cases, you can purchase similar coverage elsewhere for less.
If the interest rate seems excessively high, ask the finance manager to explain why. In some cases, the dealer may be able to find a better offer from a different lender. In other cases, the rate may be justified by your credit profile. Either way, you deserve an explanation. If you feel pressured or rushed, take a step back. A legitimate dealership will give you time to review the paperwork and ask questions.
It is also wise to get pre-approved for a loan before you go to the dealership. A pre-approval from a bank, credit union, or online lender gives you a benchmark against which to compare the dealer's offer. It also gives you negotiating power, because you can tell the dealer that you already have financing and will only use their financing if they can beat it. For borrowers with bad credit, pre-approval may be more difficult, but it is not impossible. StartAutoLoan.com, for example, connects borrowers with lenders who specialize in bad credit and no credit situations, providing a starting point for comparison.
Common Mistakes to Avoid
Bad credit auto financing is a process that can go smoothly or badly, depending on how prepared you are. Avoiding a few common mistakes can save you money and frustration.
One mistake is focusing only on the monthly payment. A low monthly payment can be achieved by extending the loan term, sometimes to 72 or 84 months. While this reduces your immediate cash outlay, it also means you pay more interest over the life of the loan and may end up owing more than the car is worth for a longer period. Always look at the total cost of the loan, not just the monthly payment.
Another mistake is accepting the first offer without comparing. Dealers are not required to give you the best rate they can find; they are required to give you a rate you agree to. If you do not compare offers, you may end up paying more than necessary. Even if you have bad credit, there may be multiple lenders willing to work with you, and their rates can vary significantly.
A third mistake is failing to review the contract carefully. Auto loan contracts are long and full of fine print, but they contain critical information about your rights and obligations. Look for the annual percentage rate, the finance charge, the total amount financed, and any prepayment penalties. If you do not understand something, ask for an explanation before you sign. Once you sign, you are legally bound to the terms.
Finally, avoid the temptation to lie on your application. Inflating your income or hiding debts may seem like a way to get approved, but it is fraud. Lenders verify information, and if they discover discrepancies, they can revoke the loan or demand immediate repayment. It is always better to be honest and work with a dealer who specializes in bad credit financing.
Getting approved for a car loan with bad credit is a challenge, but it is not an impossible one. Dealers arrange this financing every day by leveraging lender relationships, understanding underwriting guidelines, and structuring deals that work for both the borrower and the lender. As a consumer, your best strategy is to educate yourself, prepare your documentation, and approach the process with a clear understanding of what you want and what you can afford. With the right preparation, you can turn a bad credit situation into a successful car buying experience.