How a Recent Job Change Affects Auto Loan Approval
A recent job change does not automatically block auto loan approval. Learn how lenders view short tenure and what documents can strengthen your application.
By Eric Sullivan
You just accepted a better-paying position, and now you are ready to buy a car. But as you fill out the financing application, a nagging question surfaces: will the lender see your two-week-old job and slam the brakes on your approval? It is a common worry, and for good reason. Employment stability is one of the pillars underwriters lean on when they decide how risky a loan will be. The good news is that a recent job change does not automatically disqualify you. In many cases, it barely moves the needle, and in some situations, it can even help. The key is understanding what lenders actually look at, which documents you can use to prove income continuity, and how to present your situation in the best possible light.
Why Employment Length Matters to Auto Loan Underwriters
Lenders are not trying to make your life difficult when they ask how long you have been at your current job. They are trying to answer a simple question: will this borrower keep earning enough to make payments for the next 48 to 72 months? Job tenure is a proxy for stability. A borrower who has been with the same employer for five years is statistically less likely to experience an income interruption than someone who started last week. That does not make the new hire a bad risk, but it does mean the lender will look for other signals to fill in the gaps.
Most auto lenders have some internal guideline for employment length. Some want to see at least six months at the current job. Others prefer one or two years. But these are rarely hard rules. Underwriters are trained to look at the whole picture, and a short tenure at a new job can be offset by a long history in the same field, a higher salary, a healthy down payment, or a strong co-borrower. The real question is not how long you have been in your current seat, but whether your income is predictable and likely to continue.
It also helps to understand that employment length is just one factor in a broader risk model. Lenders weigh your credit score, debt-to-income ratio, loan-to-value ratio, and payment history alongside your job tenure. If your credit is solid and your debt load is manageable, a recent job change may be treated as a minor footnote rather than a red flag. On the other hand, if your credit is thin or blemished, the lender will lean more heavily on employment stability, which is why it pays to know where you stand before you apply.
When a Same-Field Job Change Is Viewed Favorably
A job change within the same industry or profession is often viewed much more favorably than a switch to an entirely new line of work. If you moved from one accounting firm to another, or from one hospital to another as a nurse, the underwriter can see a clear career trajectory. Your skills are in demand, your income is likely to be similar or higher, and the risk of a prolonged job search is lower because you have a track record in that field. In these cases, many lenders will treat your employment history as continuous even if your tenure at the new employer is short.
What underwriters dislike is a pattern of instability: three jobs in two years, gaps in employment, or a move into a completely different industry with no clear explanation. A single, well-timed job change that comes with a promotion or a pay raise is usually seen as a positive. It suggests you are moving up, not drifting. If you can show that your new role pays more than your old one, that is a strong point in your favor. Lenders like borrowers whose income is trending upward because it makes the monthly payment feel more secure.
It is also worth noting that some lenders are more flexible than others. Credit unions and community banks often have manual underwriting processes that allow a loan officer to consider your full story. Online lenders and captive finance companies may rely more on automated scoring, which can be less forgiving of short tenure. If you have recently changed jobs and want the best shot at approval, it helps to work with a connection service that can match you with lenders who are comfortable with your profile. StartAutoLoan.com, for example, connects borrowers with a network of participating lenders and dealers who specialize in situations like bad credit, no credit, and recent employment changes. You can explore auto loan options through AutoTitleLoan as well, which serves a similar audience of borrowers who need flexible financing solutions.
Documents That Show Income Continuity
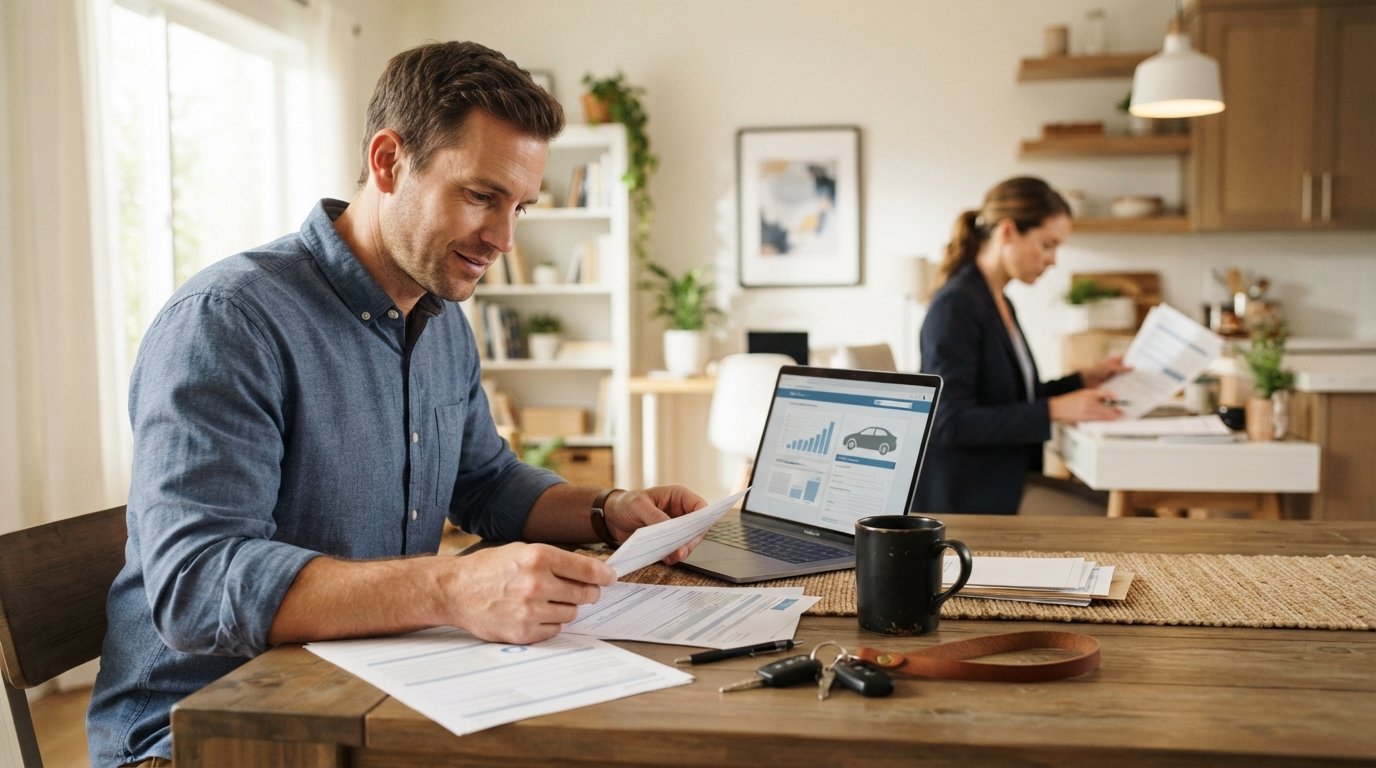
When your employment tenure is short, documentation becomes your best friend. Lenders want to see that your income is stable and sufficient, and the right paperwork can bridge the gap between a new job and a long history. The first document to gather is your offer letter or employment contract. This shows your start date, your salary, and your job title. If your offer letter states an annual salary, that is often enough for an underwriter to calculate your monthly income, even if you have not received a full paycheck yet.
Next, collect your most recent pay stubs. Even one or two pay stubs from the new job can help, but you should also include pay stubs from your previous job to show continuity. If you have been in the same field for years, the combination of old and new pay stubs tells a story of steady earnings. You can also provide W-2 forms from the past two years, which show your annual income history. For borrowers who are paid hourly or whose hours fluctuate, a written verification of employment from the new employer can be useful. Some lenders will call your employer directly to confirm your status and income.
Here is a quick checklist of documents that can strengthen your application after a recent job change:
- Offer letter or signed employment contract showing your start date and salary
- Recent pay stubs from the new job (at least one, ideally two)
- Pay stubs or W-2s from your previous job to demonstrate income continuity
- Two years of tax returns if you are self-employed or have variable income
- A written verification of employment from your new employer if requested
Having these documents ready before you apply can speed up the process and reduce the chance of a lender asking for more information later. It also signals to the underwriter that you are organized and serious about the loan, which never hurts.
How a Co-Borrower Offsets Short Tenure
If your employment history is too short to satisfy the lender on its own, adding a co-borrower can be an effective way to strengthen your application. A co-borrower is someone who applies for the loan with you and shares legal responsibility for the debt. Their income, credit history, and employment stability are considered alongside yours. If the co-borrower has a long tenure at their job and a solid credit score, the lender may be willing to overlook your short time at your new position.
This strategy works best when the co-borrower has a strong financial profile. A spouse, a parent, or a close relative with steady income and good credit can make the difference between approval and denial. Keep in mind that the co-borrower is equally responsible for the loan, so this is not a decision to take lightly. If you miss a payment, it affects both of your credit scores. It is also important to be upfront with the co-borrower about the terms of the loan and your plan for making payments.
Another option is to apply with a larger down payment. A substantial down payment reduces the lender's risk because it lowers the loan-to-value ratio. If you can put down 20 percent or more, the lender may be more forgiving of a recent job change. Similarly, choosing a less expensive vehicle or a shorter loan term can make your application more attractive. The goal is to reduce the number of risk factors the underwriter has to weigh, so that your short tenure does not become the deciding factor.
Strategies for Getting Approved After a Job Change
Beyond documentation and co-borrowers, there are several practical steps you can take to improve your chances of auto loan approval after a recent job change. The first is to wait if you can. If you have the luxury of time, waiting until you have three to six months at the new job can make the approval process much smoother. During that time, focus on paying down existing debts and saving for a larger down payment. A lower debt-to-income ratio and more cash on hand will make you a stronger candidate.
If you cannot wait, be proactive about explaining your situation. A brief letter of explanation can go a long way. In it, you can describe why you changed jobs, how it benefits your career, and why your income is stable. Keep it factual and concise. Underwriters are human, and a clear explanation can help them see your application in context. You should also consider applying with lenders who are known to be more flexible. Credit unions, community banks, and online connection services that work with borrowers who have imperfect credit are often more willing to look beyond a short employment history.
It is also wise to check your credit report before you apply. Errors on your report can drag down your score and make a short job tenure seem like a bigger problem than it is. Dispute any inaccuracies and make sure your report reflects your current situation. A higher credit score can offset concerns about employment length. If your score needs work, focus on making on-time payments and reducing your credit utilization in the months before you apply. For a deeper look at how lenders evaluate applications when credit is a challenge, our guide on guaranteed auto loan approval explains what borrowers should know about approval odds and lender expectations.
What to Expect During the Approval Process
Once you submit your application, the lender will verify your employment and income. This usually involves a phone call to your employer or a request for additional documents. If you started your job very recently, the lender may ask for your first pay stub before finalizing the approval. This is normal. It does not mean you are being rejected; it simply means the lender wants to confirm that your income has started. Be responsive and provide documents promptly. Delays in providing information can slow down the process and sometimes lead to an application being withdrawn.
It is also helpful to understand that approval is not the same as finalizing the loan. You may be approved subject to verification of employment, income, and other conditions. Read the fine print and make sure you understand what is required. If you are working with a dealer, they may handle some of the verification for you. If you are working with an online lender or a connection service, you may need to upload documents through a secure portal. Either way, keep copies of everything you submit and follow up if you do not hear back within a few days.
Finally, remember that a recent job change is a temporary issue. Once you have a few months of history at your new job, your employment stability will no longer be a concern. In the meantime, focus on what you can control: your credit score, your down payment, your debt-to-income ratio, and the quality of your documentation. Lenders are in the business of saying yes when they can, and a well-prepared application can go a long way toward getting you behind the wheel.
If you are ready to explore your options, StartAutoLoan.com can connect you with lenders and dealers who understand borrowers with recent job changes, bad credit, or no credit history. The application is quick, and you can get matched with financing options in as little as a few minutes.