Fix Credit Report Errors Before Auto Loan Application
Fixing credit report errors before your auto loan application can lower your rate and improve approval odds. Learn how to dispute mistakes and get financed.
By Jessica Hayes
You have picked out the car, you can picture yourself driving it, and now you are ready to apply for an auto loan. But before you submit that application, there is one crucial step that could mean the difference between a smooth approval and a frustrating rejection: fixing errors on your credit report. Credit report mistakes are far more common than most people realize, and they can drag down your credit score, inflate your interest rate, or even cause a lender to deny your application outright. The good news is that you have the right to dispute these errors, and doing so before you apply can save you thousands of dollars over the life of your loan.
At StartAutoLoan.com, we work with borrowers every day who have been turned down by traditional lenders because of credit issues, including errors that were never their fault. Our platform connects you with a nationwide network of participating lenders and dealers who specialize in helping people with bad credit, no credit, or past bankruptcies get behind the wheel. But even if you plan to use a connection service like ours, cleaning up your credit report first is a smart move that can improve your chances and your terms. In this guide, we will walk you through exactly how to fix credit report errors before auto loan application, step by step.
Why Your Credit Report Matters for an Auto Loan
When you apply for an auto loan, lenders pull your credit report and credit score to evaluate how risky it would be to lend you money. Your credit score is a three-digit number that summarizes your credit history, and it is calculated based on information in your credit reports from the three major bureaus: Equifax, Experian, and TransUnion. If your reports contain errors, your score may be lower than it should be, which can lead to higher interest rates, larger down payment requirements, or outright denial.
Even a small error, such as a late payment that was reported incorrectly or a collection account that belongs to someone else, can have a meaningful impact. For example, a single 30-day late payment can drop a good credit score by 50 to 100 points. A collection account can be even more damaging. When you are already dealing with bad credit or a thin credit file, you cannot afford to have inaccurate negative information dragging you down. Fixing errors before you apply gives you the best shot at the most favorable loan terms available to you.
Beyond the score itself, lenders also look at the details in your report. They want to see that you have handled credit responsibly and that there are no surprises. If they spot an unpaid collection or a charge-off that you did not know about, they may question your reliability. By reviewing your reports and disputing errors ahead of time, you present a cleaner, more accurate picture of your financial history.
Common Credit Report Errors That Hurt Auto Loan Applications
Credit reporting errors come in many forms, and some are more damaging than others. According to studies, as many as one in five consumers have an error on at least one of their credit reports. These mistakes can stem from data entry errors, identity theft, mixed files (where your information gets merged with someone else's), or creditors reporting outdated information. Here are the most common errors that can sabotage your auto loan application:
- Incorrect late payments: A payment marked as late when you actually paid on time, or a late payment that is older than seven years and should have been removed.
- Accounts that are not yours: Collection accounts, credit cards, or loans that belong to another person with a similar name or Social Security number.
- Duplicate debts: The same debt listed multiple times, which can make it look like you owe more than you do.
- Wrong balances or credit limits: An account showing a higher balance than you actually owe, or a credit limit that is lower than it should be, which can skew your credit utilization ratio.
- Outdated negative information: Bankruptcies older than 10 years, collections older than seven years, or other negative items that have passed the reporting time limit.
Any of these errors can lower your credit score and raise red flags for auto lenders. If you spot one, it is essential to dispute it with the credit bureau and the creditor that reported it. The dispute process is free and you can do it yourself, though it does require some patience and paperwork.
How to Get Your Credit Reports and Spot Errors
The first step in fixing credit report errors is to get copies of your reports from all three major credit bureaus. By law, you are entitled to a free copy of your credit report from each bureau every 12 months through AnnualCreditReport.com. You can also request reports directly from Equifax, Experian, and TransUnion. During the COVID-19 pandemic, the bureaus began offering free weekly reports, and that practice has continued, so you can check your reports more frequently.
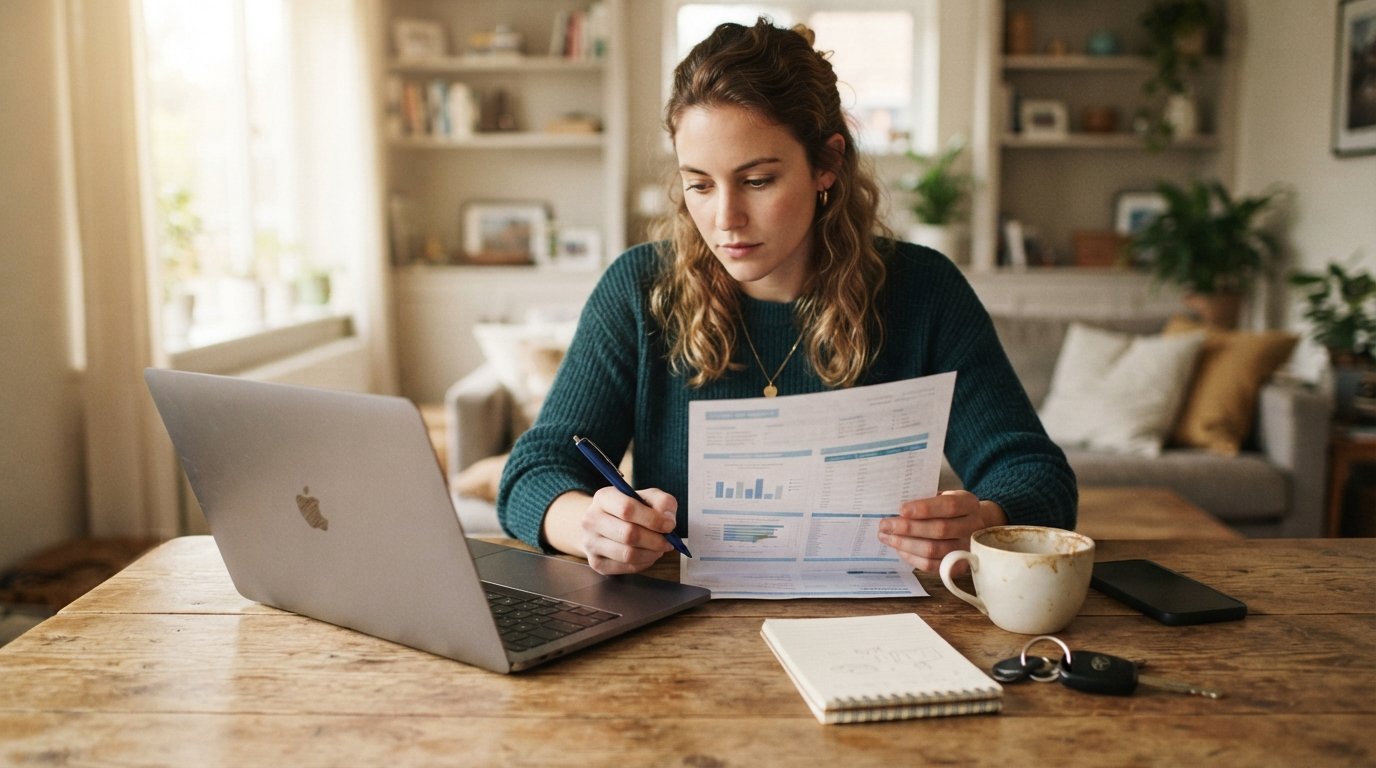
Once you have your reports, review them carefully. Look at every account, every balance, every payment history entry, and every personal information detail. Check for the errors we listed above. It also helps to compare the reports from all three bureaus side by side, because an error might appear on only one or two of them. Make a list of every item you believe is inaccurate, along with an explanation of why it is wrong and any supporting documentation you have, such as bank statements, payment receipts, or correspondence with the creditor.
If you find errors, do not panic. You have the right to dispute them, and the credit bureaus are required to investigate and correct inaccurate information. The process typically takes about 30 days, though it can take longer if you provide additional information. Start this process at least two to three months before you plan to apply for an auto loan, so you have time to see results.
Step-by-Step: How to Dispute Credit Report Errors
Disputing errors is a straightforward process, but it does require attention to detail. Follow these steps to give yourself the best chance of a successful outcome.
- Gather your evidence: Collect documents that prove the error, such as canceled checks, billing statements, or a police report if you were a victim of identity theft.
- Write a dispute letter: Send a letter to each credit bureau that shows the error. Include your full name, address, date of birth, and the specific items you are disputing. Explain why each item is incorrect and attach copies of your evidence. You can also file disputes online through the bureau websites, which can be faster.
- Contact the creditor directly: In addition to disputing with the bureaus, send a dispute letter to the creditor or lender that reported the inaccurate information. They are also responsible for correcting errors.
- Keep records: Make copies of everything you send and note the dates. Send letters via certified mail with return receipt requested so you have proof of delivery.
- Follow up: The bureaus must investigate and respond within 30 days. If the error is verified as inaccurate, they must correct it or remove it. If they do not, you can file a complaint with the Consumer Financial Protection Bureau or consider legal action.
While you wait for the disputes to be resolved, avoid applying for new credit or making any major financial changes. Each hard inquiry from a new credit application can temporarily lower your score, and you want your reports to be as stable as possible during the dispute process.
What If You Have Bad Credit and Cannot Wait?
If you have bad credit and need a car loan soon, you might not have time to wait for disputes to be resolved. That is where StartAutoLoan.com can help. We specialize in connecting borrowers with bad credit, no credit, or past bankruptcies to lenders and dealers who are willing to work with them. Our network includes partners who look beyond just your credit score and consider your overall financial situation. You can submit a secure online application in minutes, and we will match you with a participating dealer or lender who may offer approval in as little as 24 hours.
Even if you plan to use our service, fixing credit report errors before applying is still a smart move. A cleaner report can mean a lower interest rate and better loan terms, which can save you money every month. If you are not sure where to start, our guide on how to get an auto loan with bad credit walks you through the entire process, from checking your credit to working with subprime lenders.
It is also worth noting that some lenders in our network specialize in working with borrowers who have credit challenges, and they may be more forgiving of past errors. However, they will still review your credit report, so any inaccuracies you can correct beforehand will only help your case.
How Long Does It Take to Fix Credit Report Errors?
The time it takes to fix credit report errors depends on the complexity of the dispute and how quickly the bureaus and creditors respond. In general, you can expect the following timeline:
- Initial review: 1-2 weeks to gather your reports and identify errors.
- Dispute filing: 1-2 days to prepare and send dispute letters or file online.
- Bureau investigation: Up to 30 days (sometimes 45 days if you provide additional information during the investigation).
- Creditor response: May take an additional 2-4 weeks for the creditor to update their records and notify the bureaus.
- Report update: Once the bureau completes its investigation, it has 5 business days to notify you of the results and update your report if changes are made.
In total, the process can take anywhere from 30 to 60 days, or longer if the dispute is complicated or requires multiple rounds. That is why it is best to start early, ideally two to three months before you need financing. If you are on a tight timeline, you can still apply for a loan while disputes are pending, but be aware that the lender will see the disputed items on your report.
Tips to Improve Your Credit Before Applying for an Auto Loan
Fixing errors is just one piece of the puzzle. Even if your report is accurate, there are other steps you can take to strengthen your credit profile and improve your chances of approval. Here are some practical tips:
- Pay down existing debts: Lowering your credit card balances can reduce your credit utilization ratio, which is a major factor in your credit score.
- Avoid new credit inquiries: Do not apply for new credit cards or loans in the months leading up to your auto loan application, as each application can ding your score.
- Keep old accounts open: The length of your credit history matters, so avoid closing old credit card accounts even if you do not use them much.
- Make all payments on time: Payment history is the single biggest factor in your credit score. Set up automatic payments or reminders to ensure you never miss a due date.
- Consider a secured credit card or credit-builder loan: If you have no credit or bad credit, these tools can help you establish a positive payment history.
For a deeper dive into rebuilding your credit, our article on car loan refinancing offers additional strategies and resources that can help you improve your financial standing over time.
When to Apply for an Auto Loan After Fixing Errors
Once you have disputed errors and received confirmation that they have been corrected, you should wait for your credit reports and scores to update before applying for an auto loan. This typically happens within 30 days after the dispute is resolved, but it can take longer. You can check your credit score for free through many services, or you can purchase a score from the bureaus. Once you see the improvement, you are ready to apply.
If you are working with StartAutoLoan.com, you can submit your application online at any time. We will connect you with lenders and dealers who understand your situation and can work with you to find financing that fits your budget. Remember, there is no obligation to accept any offer, and our service is completely free to use.
Fixing credit report errors before your auto loan application is one of the most effective ways to improve your chances of approval and secure better terms. It takes some effort, but the payoff can be significant: a lower interest rate, a smaller down payment, and more peace of mind. Start by getting your free credit reports, disputing any inaccuracies, and then let StartAutoLoan.com help you find the financing you need.