Extended Warranty New vs Used Car Loan Pros Cons
Weigh the extended warranty new vs used car loan pros cons. See how rolling coverage into financing affects your monthly payment and total interest.
By Rachel Adams
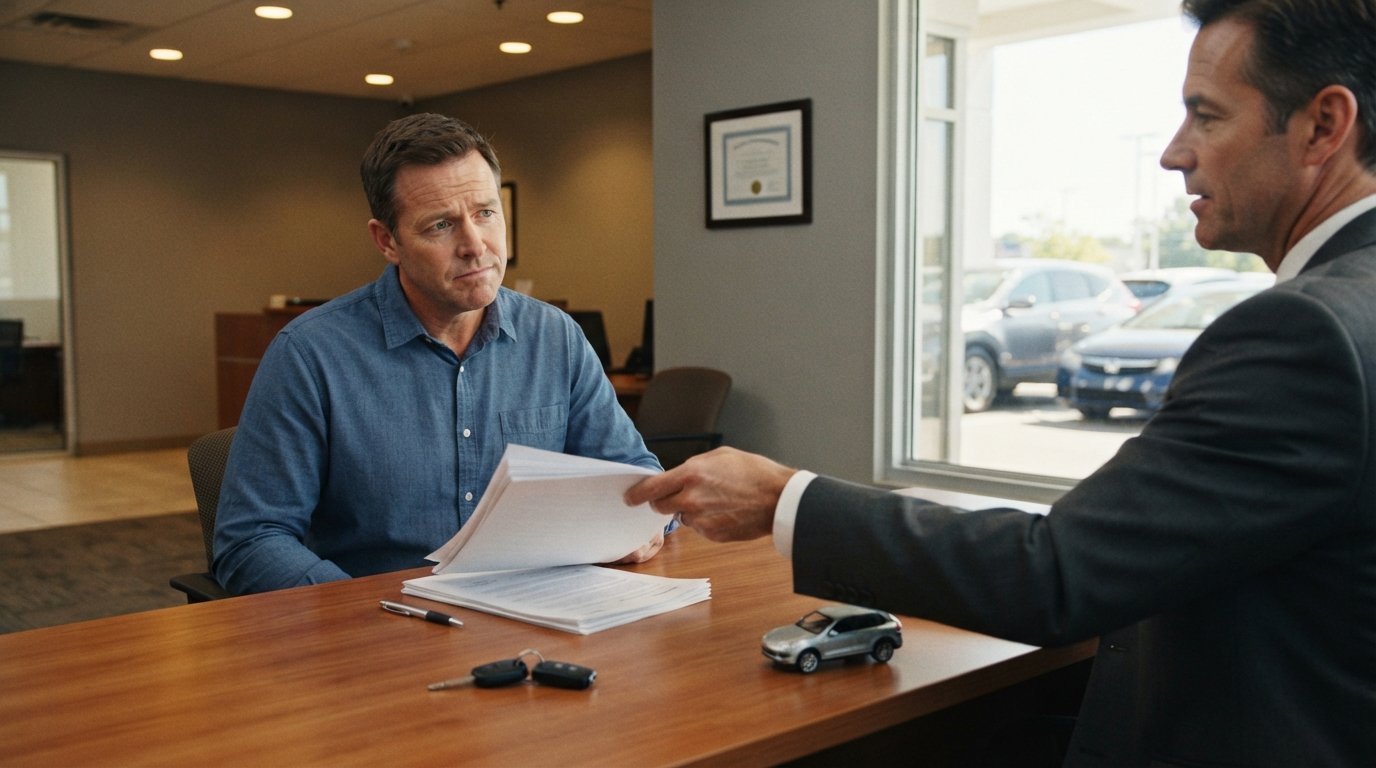
You are sitting in the dealership finance office, and the manager slides a thick contract across the desk. They are offering you an extended warranty, and they want to roll the cost into your auto loan. The monthly payment increase sounds small, maybe just twenty dollars more per month. But is it worth it? This is a common scenario for both new and used car buyers, but the math changes dramatically depending on the vehicle's age and your credit situation. Understanding the extended warranty new vs used car loan pros cons is critical before you sign on the dotted line, especially if you are already dealing with tight approval requirements.
The Core Difference: New vs Used Extended Warranties
Before diving into the financing aspect, it is important to understand that extended warranties are not a one-size-fits-all product. The coverage you get for a brand-new vehicle is fundamentally different from what you can purchase for a used car with 60,000 miles on the odometer. When you buy new, you are essentially extending the factory bumper-to-bumper coverage. These plans are often backed by the manufacturer, meaning repairs are done at certified dealerships with genuine parts, and claims are rarely denied.
When you buy used, you are typically purchasing a vehicle service contract (VSC) from a third-party provider. These contracts are more varied and often have stricter limitations. A used car might have pre-existing conditions that are not covered, or the provider might cap the total payout at the purchase price of the vehicle. This distinction is vital because the pros of a new car warranty (comprehensive peace of mind) often outweigh the cons of a used car warranty (limited coverage and higher deductibles). However, the cost of a new car warranty is significantly higher, which brings us to the financing dilemma.
If you are struggling to get approved for a loan, whether due to bad credit or a lack of credit history, adding an expensive warranty can push your debt-to-income ratio over the edge. Lenders look at the total amount financed. If the warranty pushes the loan amount beyond what the vehicle is worth (loan-to-value ratio), the lender might reject the deal entirely. This is a major con to consider. For those in this situation, securing the loan first is the priority. You can learn more about navigating these specific challenges in our guide on used car loans for bad credit borrowers, which explains how to balance approval needs with add-on costs.
Financing the Warranty: The Pros and Cons
The decision to finance an extended warranty is separate from the decision to buy one. You can often pay for a warranty upfront with cash, or you can roll it into your monthly payment. Financing the warranty is popular because it avoids a large out-of-pocket expense at the dealership. This is especially appealing for first-time buyers or those on a tight budget who need to preserve cash for other expenses like taxes, tags, and insurance.
However, financing a warranty means you are paying interest on it. Over a 60-month or 72-month loan term, a $2,000 warranty could end up costing you significantly more. Furthermore, if your car is totaled or stolen, the warranty is usually canceled, and the refund goes to the lender, not to you. You might end up paying for coverage you can no longer use. On the flip side, if you are buying a used car with a high interest rate, financing a warranty might be the only way to afford protection against a major mechanical failure.
Here is a breakdown of the key financial pros and cons of rolling an extended warranty into your car loan:
- Pro: Immediate protection with no upfront cash required, preserving your savings for emergencies.
- Pro: Convenience of a single monthly payment that covers both the vehicle and the protection plan.
- Con: You pay interest on the warranty cost, which can add hundreds of dollars to the total price.
- Con: If the car is totaled early in the loan term, you lose the coverage and the money paid toward it.
- Con: Negative equity grows faster because the warranty depreciates immediately along with the car.
It is also worth noting that some lenders cap how much warranty cost they will finance. They might only allow you to finance up to 10% or 15% of the vehicle's sales price for add-ons. If you exceed this, you must pay the difference in cash. If you are looking for ways to optimize your current loan terms to accommodate these costs, exploring car loan refinancing options can provide insights into how changing your term or rate might free up room in your budget for protection plans.
When an Extended Warranty Makes Sense
An extended warranty is not inherently bad; it is simply a financial product that transfers risk. For some buyers, it makes perfect sense. If you are buying a complex used luxury vehicle or a model known for expensive repairs, a warranty can be a financial lifesaver. For example, a used BMW or a high-tech electric vehicle might have repair costs that run into the thousands. In these cases, the peace of mind is worth the premium and the interest.
Additionally, if you plan to keep the car for a long time and drive more than the average number of miles, a warranty can pay for itself. Factory warranties typically expire at 36,000 or 50,000 miles. If you drive 20,000 miles a year, you will exhaust that coverage quickly. An extended warranty bridges the gap between the end of the factory coverage and the end of your loan term.
However, if you are buying a reliable, simple used car like a Honda Civic or Toyota Corolla, the odds of a major failure are lower. In this scenario, the cons often outweigh the pros. You might be better off taking the money you would have spent on the warranty and putting it into a savings account for repairs. This is a common strategy for savvy buyers who understand that the average repair cost for a reliable car is often less than the cost of the warranty plus interest.
How Credit Profile Impacts Your Decision
Your credit score plays a massive role in the extended warranty new vs used car loan pros cons equation. If you have excellent credit, you likely qualify for a low interest rate. Financing a warranty at 3% APR is relatively cheap, making the pro of convenience more attractive. However, if you have bad credit, your interest rate might be 15% or higher. Financing a warranty at that rate is expensive. You could end up paying $2,500 for a $1,500 warranty.
For borrowers with challenged credit, the priority should be establishing a reliable loan with affordable payments. Adding a warranty increases the payment and the risk of default. If you default, you lose the car and the warranty. It is often wiser to decline the warranty at the dealership, get the loan approved, and then purchase a warranty later from a third-party provider if you still feel it is necessary. Many third-party providers allow you to pay monthly without interest, or you can buy a plan later as long as the car passes an inspection.
StartAutoLoan.com specializes in helping consumers find financing options even when traditional lenders say no. Whether you are looking for a new car loan or need financing for a used vehicle, the platform connects you with a network of lenders and dealers who work with diverse credit profiles. This allows you to focus on getting the vehicle you need without the pressure of high-cost add-ons derailing your approval.
Making the Final Decision
The decision to buy and finance an extended warranty should be based on math, not emotion. The finance manager will use fear to sell you the warranty, telling you stories of transmission failures and engine blowouts. Your job is to assess the actual risk. Look up the reliability ratings for the specific make and model you are buying. Check the cost of common repairs. If the potential repair cost is manageable and the car is reliable, skip the warranty.
If you decide to buy, negotiate the price of the warranty just like you negotiate the price of the car. The markup on extended warranties is high, and dealers often have room to move. If you are financing, ask for a quote on the warranty with and without the financing. Compare the total cost of the loan with the warranty included versus paying for the warranty separately. Sometimes, a credit union or online lender offers a better rate on the warranty portion than the dealership.
Ultimately, the best warranty is a well-maintained vehicle and a solid financial cushion. If you can afford the car and have savings for repairs, you might not need the warranty at all. But if you need the protection for peace of mind and can afford the extra monthly cost without straining your budget, financing it can be a convenient way to protect your investment. Just be sure to read the fine print, understand what is excluded, and ensure the loan terms are fair.