Dealership Role in Securing Bad Credit Auto Loans
Dealerships connect bad credit buyers with subprime lenders and often secure approval in hours. Learn how their finance offices work and how to protect yourself.
By Ryan Walker
Walking into a dealership with bad credit can feel like walking a tightrope. You need a reliable vehicle, but past credit missteps may have closed doors at traditional banks. Here is the truth many shoppers never hear: the dealership itself can be one of your strongest allies in getting approved. Dealers work with specialized lenders every day, and they know exactly which financing sources say yes to imperfect credit. Understanding the dealership role in securing bad credit auto loans changes the entire game, turning a stressful hunt into a manageable process with a real path to approval.
How Dealerships Connect Borrowers With Subprime Lenders
Most franchise and independent dealerships maintain relationships with a network of lenders that specialize in subprime financing. These are banks, credit unions, and finance companies that deliberately work with borrowers who have scores below 620, past bankruptcies, repossessions, or no credit history at all. When you apply at a dealership, the finance manager does not just check one bank. They typically submit your application to multiple lenders in what is called a shotgun or multi-lender submission. This increases your odds dramatically because different lenders have different risk tolerances and approval criteria.
For example, one lender might approve borrowers with a 540 score as long as they have steady income and a down payment, while another might overlook a recent bankruptcy if the borrower has re-established two lines of credit. The dealership finance office knows these quirks because they work with these lenders daily. That insider knowledge is a core part of the dealership role in securing bad credit auto loans, and it is something you cannot easily replicate by applying to banks on your own.
What the Finance Manager Actually Does Behind the Scenes
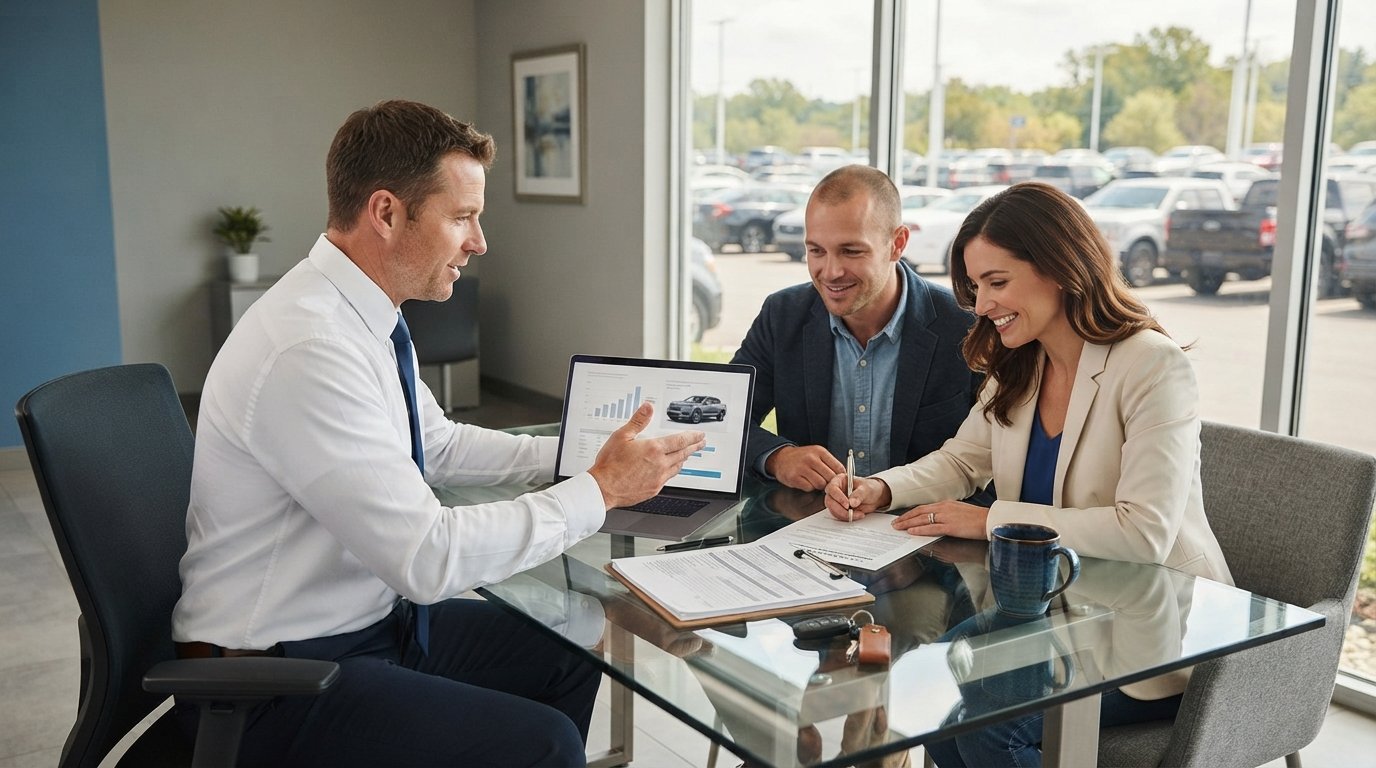
The finance manager, sometimes called the F&I manager, is the person who structures your deal. They review your credit report, income documentation, and the vehicle you want, then match you with lenders most likely to approve. They also negotiate terms on your behalf, though it is important to remember they work for the dealership, not for you. Still, their goal is to get the deal funded, which means they have a strong incentive to find an approval.
Here is a simplified look at the steps a finance manager typically follows when working with a bad credit buyer:
- Pull your credit report and review your score, derogatory marks, and any recent improvements.
- Collect proof of income, residence, and insurance, plus a down payment if required.
- Submit your application to multiple subprime lenders through a dealer portal.
- Compare approval offers and select the one with the best combination of rate, term, and monthly payment.
- Present the offer to you, explain the terms, and finalize paperwork if you accept.
Each of these steps happens quickly, often within an hour or two. That speed matters because it reduces the chance of another dealer pulling your credit or you making a rushed decision elsewhere. The dealership role in securing bad credit auto loans is largely about efficiency and access, two things that are hard to find when applying alone.
Why Dealership Financing Often Beats Going It Alone
If you have bad credit, applying directly to a bank or credit union can feel like hitting a brick wall. Many traditional lenders have strict score cutoffs, and a single application may result in a denial with no explanation. Dealerships, by contrast, have established relationships with lenders that expect imperfect credit. They also know which lenders report to the credit bureaus, which can help you rebuild your score with on-time payments.
Another advantage is convenience. Instead of filling out five separate applications, you fill out one at the dealership and let the finance office do the legwork. You also get to test drive and choose a vehicle on the same day, which is a huge benefit if you need transportation immediately. For a deeper look at how to prepare before you ever step on the lot, our guide on auto loan pre approval for bad credit walks through the documents and steps that can speed up the process.
That said, dealership financing is not automatically the cheapest option. Some dealers mark up interest rates to increase their profit, a practice called rate markup. You can protect yourself by asking for the buy rate (the lender's actual approved rate) and comparing it to what you are offered. Knowledge is your best defense, and understanding the dealership role in securing bad credit auto loans helps you spot when a deal is fair versus when it is padded.
How to Vet a Dealership Before You Trust Them With Your Credit
Not every dealership treats bad credit borrowers fairly. Some use high-pressure tactics, push add-ons you do not need, or fail to disclose the full cost of financing. Before you hand over your driver's license and Social Security number, do a little homework. Check online reviews, ask about their lender network, and confirm they work with subprime lenders. A reputable dealer will be transparent about the process and will not pressure you into signing before you understand every line of the contract.
It also helps to get pre-approved elsewhere first, even if you plan to use dealer financing. A pre-approval from an online connection service or a credit union gives you a baseline rate and shows the dealer you have options. At StartAutoLoan.com, you can submit a secure application and get matched with participating dealers and lenders who specialize in bad credit situations, often with approval in as little as 24 hours. That kind of leverage can keep a dealership honest and may even motivate them to offer better terms.
Negotiating Terms When Your Credit Is Less Than Perfect
Negotiation with bad credit works differently than it does for prime borrowers. You may not have much room to haggle on the interest rate, but you can still influence the overall deal. The down payment, vehicle price, and loan term are all areas where you have some control. A larger down payment reduces the lender's risk, which can sometimes lower your rate or increase your approval amount. Choosing a less expensive vehicle also improves your chances because the loan-to-value ratio is more favorable.
Here are a few practical strategies to use during the negotiation:
- Ask the finance manager to show you all lender offers, not just the one they prefer.
- Request a shorter loan term if you can afford the higher monthly payment; it reduces total interest.
- Decline add-ons like extended warranties or paint protection if they are not required by the lender.
- Confirm there is no prepayment penalty so you can refinance later without a fee.
- Get every promise in writing before you sign anything.
These steps keep you in control and prevent the dealership from dictating terms that do not serve your long-term financial health. Remember, the dealership role in securing bad credit auto loans is about access, but you are still the one who has to live with the loan. If a deal feels wrong, walk away. Another lender or another dealership may offer something better.
Refinancing Later: A Smart Exit Strategy
Many borrowers with bad credit accept a high interest rate just to get into a vehicle. That is a reasonable short-term move if you need transportation now. But it should not be a permanent situation. After 12 to 18 months of on-time payments, your credit score may improve enough to qualify for a refinance at a lower rate. Refinancing replaces your current loan with a new one, ideally with better terms. You can explore options through platforms like CarLoanRefinancing.com, which provides educational guides and connects vehicle owners with lenders who may offer reduced rates or adjusted terms.
The key is to make all your payments on time and avoid taking on new debt in the meantime. Keep your credit utilization low and monitor your score for free. When you are ready, shop around for refinance offers just as you would for a purchase loan. The dealership role in securing bad credit auto loans gets you on the road, but refinancing is how you take control of the road ahead.
Common Mistakes to Avoid at the Dealership
Even with a helpful finance manager, you can derail your own approval by making avoidable mistakes. One of the biggest is applying at multiple dealerships within a short period without understanding how credit inquiries work. While auto loan inquiries within a 14-day window typically count as one for scoring purposes, some lenders still view multiple applications as a risk signal. Let the first dealership try to secure financing before you move on to the next.
Another mistake is overestimating your income or underreporting expenses. Lenders verify income, and discrepancies can lead to a denial or even accusations of fraud. Be honest and bring documentation. Also, do not assume you need a cosigner to get approved. Many subprime lenders approve borrowers on their own, especially if they have a stable job history and a decent down payment. Finally, never sign a contract you do not fully understand. Ask questions, take your time, and read the fine print. The dealership role in securing bad credit auto loans is a partnership, but you are the one who must protect your interests.
The Bottom Line on Dealership Financing for Bad Credit
Dealerships are not magic wands, but they do open doors that are often closed to individual applicants. Their access to subprime lenders, their ability to submit multiple applications at once, and their experience structuring deals for imperfect credit make them a valuable resource. If you have been rejected elsewhere, a dealership that specializes in bad credit financing may be your best shot at getting approved. Just go in prepared, know your numbers, and keep an eye on the total cost of the loan.
StartAutoLoan.com is a connection service that helps you get matched with participating dealers and lenders who work with bad credit, no credit, and bankruptcy. You can apply online in minutes and potentially receive a response the same day. Whether you are buying your first car or getting back on your feet after a financial setback, understanding the dealership role in securing bad credit auto loans puts you in a stronger position to drive away with a fair deal.