Cosigner for Auto Loan with Bad Credit: How It Helps
A cosigner for an auto loan with bad credit can lower your rate and improve approval odds. See how it works and what to weigh before asking someone to sign.
By Jessica Hayes
Finding a car loan with bad credit often feels like hitting a brick wall. Lenders see a low score, past bankruptcies, or no credit history, and the approval doors close fast. But there is a workaround many borrowers overlook: adding a cosigner. A cosigner for an auto loan with bad credit can change how lenders see your application, sometimes turning a rejection into an approval with a lower rate. This guide explains exactly how that happens, what a cosigner really does, and whether it is the right move for your situation.
What a Cosigner Actually Does on an Auto Loan
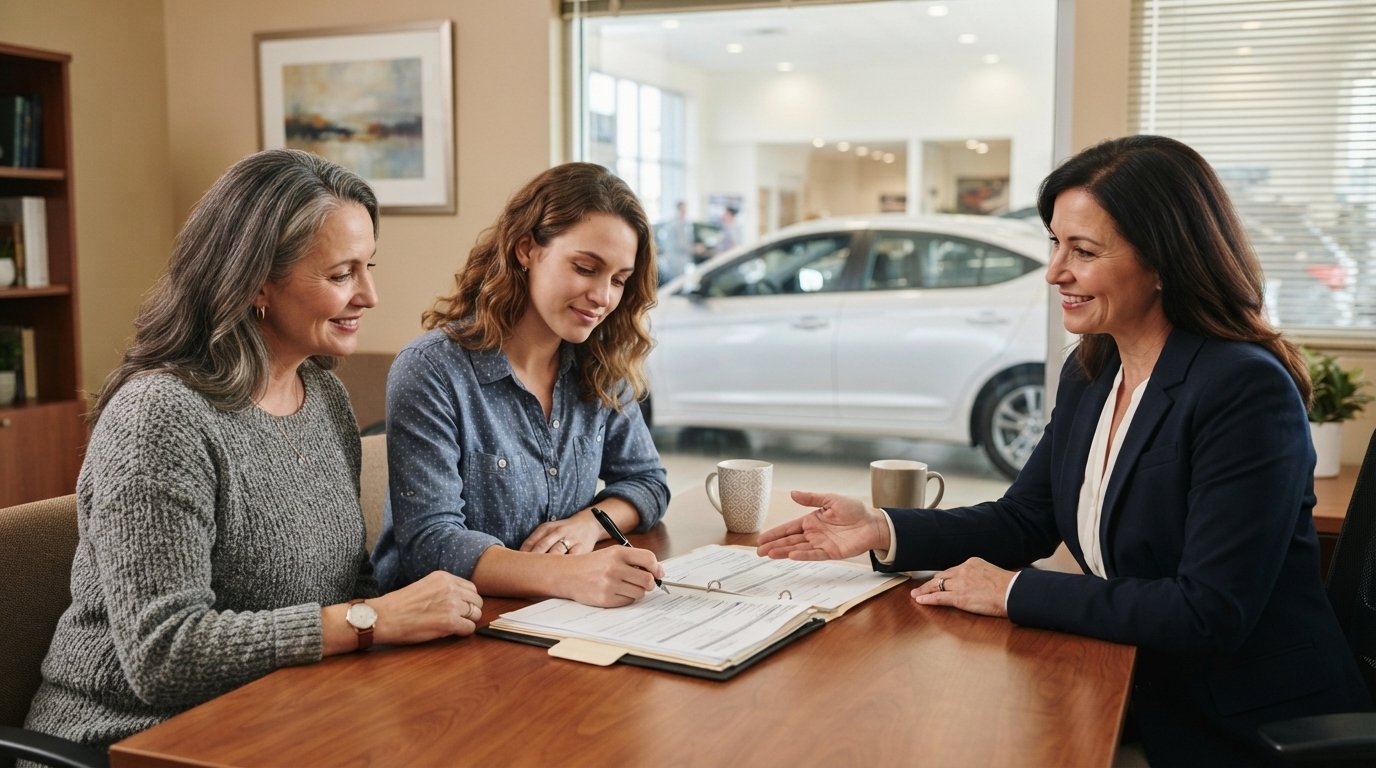
A cosigner is someone who agrees to share legal responsibility for your auto loan. They are not just a reference or a character witness. They sign the same contract you do. If you stop paying, the lender can pursue the cosigner for the full remaining balance, and the missed payments will appear on the cosigner's credit report as well as yours.
When you apply for a loan on your own, the lender looks at your credit score, income, debt-to-income ratio, and payment history. With bad credit, those factors often fall short of the lender's minimum standards. Adding a cosigner brings a second set of financial credentials into the picture. The lender now evaluates the combined strength of both applicants. If the cosigner has good credit, steady income, and a clean repayment history, the lender's risk drops significantly.
The cosigner does not need to be a spouse or relative, though most borrowers choose a parent, sibling, or close friend. The key is that the cosigner trusts you to make every payment on time, because their own credit is on the line for the life of the loan.
How a Cosigner Helps When Your Credit Is Bad
The core benefit of a cosigner is simple: it shifts the lender's risk assessment. Your bad credit might suggest you are likely to default, but the cosigner's good credit suggests someone reliable is standing behind the loan. Lenders respond to that reduced risk in three concrete ways.
First, approval becomes more likely. Many lenders have hard credit score cutoffs. If your score falls below that line, your application is rejected automatically, regardless of your income or down payment. A cosigner with a qualifying score can push the application past that cutoff. Second, your interest rate drops. Lenders price loans based on risk. A lower-risk borrower gets a lower annual percentage rate (APR). A cosigner with strong credit can help you qualify for rates that are several percentage points lower than what you would get alone. Third, the loan terms improve. You may qualify for a longer repayment period, a higher loan amount, or a lower down payment requirement.
Consider a practical example. Suppose you want to finance a $20,000 used car. On your own, with a 580 credit score, a lender might offer a 15 percent APR over 60 months. That means a monthly payment of roughly $475 and total interest of about $8,500. With a cosigner who has a 750 score, the same loan might come with a 6 percent APR. Your monthly payment drops to about $387, and total interest falls to roughly $3,200. That is a savings of more than $5,000 over the life of the loan.
Who Qualifies as a Good Cosigner
Not every willing friend or family member will help. Lenders have their own criteria for cosigners, and a weak cosigner may not improve your chances at all. Here is what to look for:
- Good to excellent credit: A score of 700 or higher is ideal. Scores below 650 may still help, but the benefit is smaller.
- Stable income: The cosigner needs enough income to cover their own obligations plus the new loan if you default.
- Low debt-to-income ratio: Lenders want to see that the cosigner is not already stretched thin.
- Clean credit history: No recent bankruptcies, foreclosures, or late payments.
- U.S. citizenship or permanent residency: Most lenders require this.
Before you ask someone to cosign, have an honest conversation about what it means. They need to understand that they are fully responsible if you stop paying. They also need to know that this loan will appear on their credit report and could affect their ability to get their own financing in the future.
The Risks and Responsibilities for Both Parties
Cosigning is not a favor without consequences. Both you and your cosigner take on significant risks. For you, the main risk is relational. If you fall behind on payments, you damage your cosigner's credit and potentially your relationship. For the cosigner, the risk is financial and legal. They can be sued for the remaining balance, and their credit score can drop by 100 points or more if the loan goes into default.
There is also the issue of credit utilization. The new auto loan will show up on the cosigner's credit report as an installment loan. If the cosigner already has high balances on other accounts, adding this loan could push their debt-to-income ratio too high, making it harder for them to qualify for a mortgage or another loan.
To protect both parties, set clear expectations before signing. Agree on who pays what, when payments are due, and what happens if you lose your job or face another financial emergency. Some cosigners ask for access to the loan account so they can monitor payments. Others set up automatic payments from a shared account. The more transparent you are, the lower the risk of a nasty surprise.
Alternatives to a Cosigner When Bad Credit Blocks You
A cosigner is not the only path to approval. If you cannot find someone willing to cosign, or if you prefer not to involve a loved one in your finances, there are other options. StartAutoLoan.com specializes in connecting borrowers with bad credit, no credit, or past bankruptcies to lenders who are more flexible than traditional banks. The platform is not a direct lender. It is a connection service that matches your application with a network of participating dealers and lenders.
Some borrowers qualify for a loan on their own by making a larger down payment. A down payment of 20 percent or more reduces the lender's risk and can offset a low credit score. Others choose a cheaper car. Financing $8,000 instead of $20,000 means the lender has less exposure, which can make approval easier even with bad credit.
Another option is to improve your credit before applying. Paying down high balances, disputing errors on your credit report, and making every payment on time for six to twelve months can raise your score enough to qualify for better terms. You can also ask a trusted family member to add you as an authorized user on their credit card, which may boost your score without making them responsible for your car loan.
For those who already have a car loan with a high interest rate, refinancing may be a better path than cosigning. If your credit has improved since you bought the car, you might qualify for a lower rate on your own. Platforms like CarLoanRefinancing.com offer educational resources and rate comparisons to help you evaluate whether refinancing makes sense. You can also check current market rates in our guide on auto loan rates today to see what a cosigner or refinance might save you.
How to Apply with a Cosigner Through StartAutoLoan.com
If you decide a cosigner is right for you, the application process is straightforward. StartAutoLoan.com works with a network of lenders and dealers who understand bad credit situations. The platform lets you submit one application and get matched with financing options rather than applying to dozens of lenders individually.
Here is a step-by-step look at how it works:
- Gather your information: You will need your driver's license, proof of income, and the cosigner's personal and financial details.
- Complete the online application: Fill out the secure form on StartAutoLoan.com. Include your cosigner's information where requested.
- Get matched with lenders: The platform shares your application with participating dealers and lenders who offer bad credit auto loans.
- Review offers: You may be contacted within minutes to hours. Compare APR, monthly payment, and loan term before choosing.
- Finalize the loan: Once you accept an offer, the dealer or lender will guide you through the final paperwork and vehicle purchase.
The entire process can move quickly. Some borrowers receive a response in as little as 10 minutes and get approved within 24 hours. Having a cosigner ready with their information can speed things up even more.
Is a Cosigner the Right Choice for You?
A cosigner can be a powerful tool when bad credit stands between you and a reliable vehicle. It can lower your interest rate, reduce your monthly payment, and increase your chances of approval. But it is not a decision to take lightly. The cosigner is putting their credit and finances on the line for you. If you are confident you can make every payment on time, a cosigner may be the fastest way to get behind the wheel.
If you would rather explore options on your own, StartAutoLoan.com connects borrowers with bad credit to lenders who specialize in these situations. You can request a quote and see what offers are available without obligation. Whether you choose a cosigner or go it alone, the key is to understand the terms, compare offers, and make a decision that protects both your finances and your relationships.