Car Loan With Unemployment or Gig Work Income: 2026 Guide
Learn how to get a car loan with unemployment income or gig work only. Discover which documents lenders accept and how to strengthen your application.
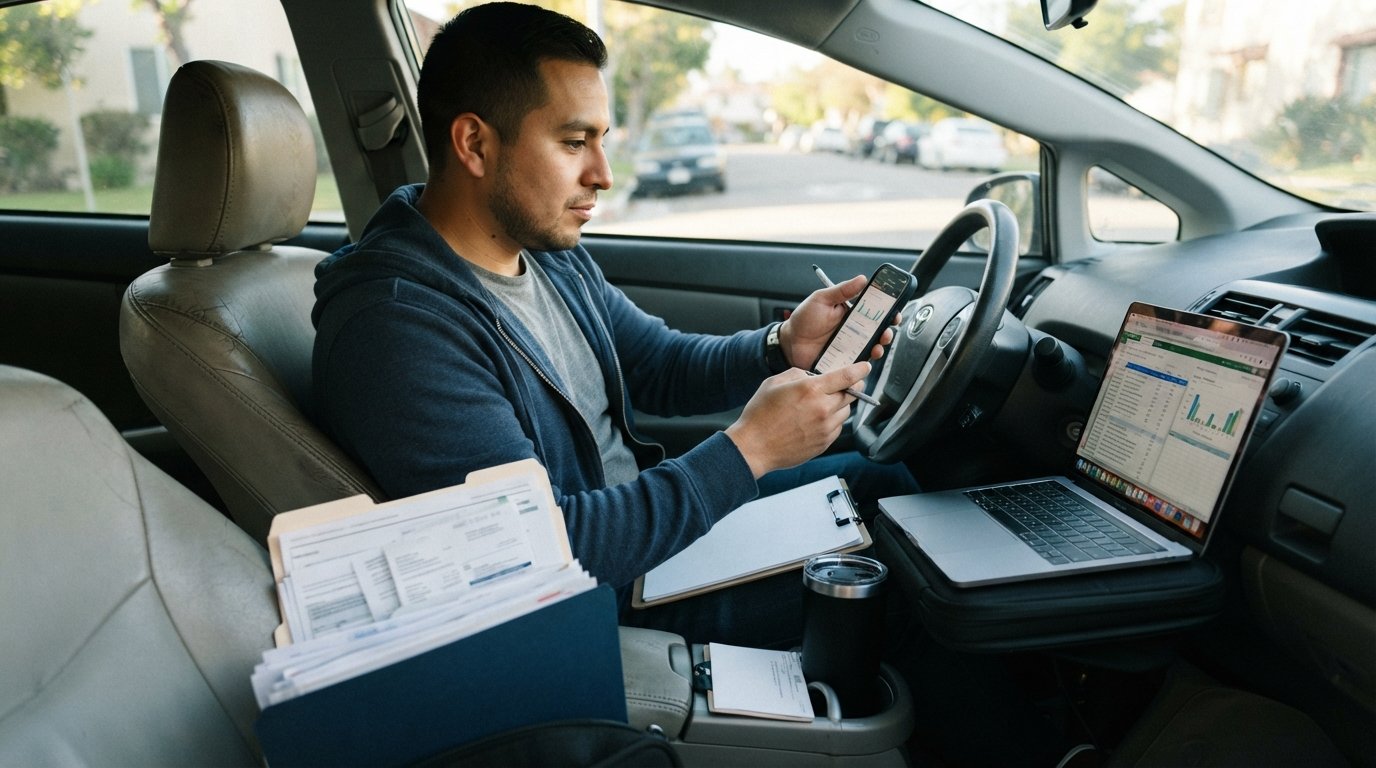
Getting approved for a car loan when your income comes from unemployment benefits or gig work can feel like an uphill battle. Traditional lenders often expect a steady paycheck and W-2 forms, leaving freelancers, rideshare drivers, and those receiving unemployment benefits wondering if financing is even possible. The good news is that it is possible. Lenders have adapted to the modern workforce, and there are specific pathways to secure a car loan with unemployment income or gig work only. This guide will walk you through the documentation lenders accept, how to present your income convincingly, and the strategies that can strengthen your application even when your earnings are irregular.
How Lenders Evaluate Nontraditional Income
When you apply for an auto loan, lenders are primarily concerned with one thing: your ability to repay. They assess this through your credit history, debt-to-income ratio, and proof of income. For applicants with traditional jobs, pay stubs and W-2s make this straightforward. For those with gig work or unemployment income, the verification process is more nuanced.
Lenders typically look at the stability and consistency of your income. Gig work, such as driving for a rideshare company or delivering packages, is considered self-employment income. Unemployment benefits, on the other hand, are viewed as temporary assistance. Each type of income requires different documentation and carries different weight in a lender's decision. Understanding these distinctions is the first step toward building a successful application.
Income Documentation for Gig Workers and Self-Employed Borrowers
If your income comes from gig work, you are essentially self-employed in the eyes of a lender. This means you will need to provide documentation that proves your earnings over time. The most common documents include:
- 1099 forms: These are issued by gig platforms and summarize your earnings for the year. Lenders often ask for the past two years of 1099s to establish a pattern of income.
- Bank statements: Three to six months of bank statements showing consistent deposits from your gig work can serve as proof of income. Lenders may look for regular deposits that align with your reported earnings.
- Profit and loss statements: If you have multiple income streams or have been self-employed for a while, a simple profit and loss statement prepared by you or your accountant can help.
- Tax returns: Filed tax returns for the past two years are often required for self-employed borrowers. They provide a comprehensive view of your income after deductions.
It is important to note that lenders may average your income over the past two years to smooth out fluctuations. If your gig work is relatively new (less than a year), some lenders may still consider your application, but they might require a larger down payment or a co-borrower to mitigate risk. Additionally, maintaining separate bank accounts for personal and business expenses can make it easier to document your income.
Using Bank Statements and 1099s in Place of Pay Stubs
For many gig workers, pay stubs are not available. Instead, bank statements and 1099s become the primary evidence of income. Lenders that specialize in serving borrowers with nontraditional income are accustomed to reviewing these documents. They look for consistency: regular deposits over several months, no unexplained gaps, and income that is sufficient to cover your proposed car payment and other debts.
When submitting bank statements, be prepared to explain any large or irregular deposits. Lenders may ask for additional context to ensure the funds are indeed income and not one-time gifts or loans. Similarly, 1099s should match the deposits in your bank accounts. Discrepancies can raise red flags and slow down the approval process. If you have multiple gig jobs, compile 1099s from all sources and organize them clearly. For those who have faced rejection from traditional lenders, Credit Acceptance car loans for bad credit offer a specialized path that considers nontraditional income documentation.
Why Unemployment Benefits Are Treated Differently
Unemployment income is fundamentally different from earned income because it is temporary by nature. Lenders view it as a stopgap measure rather than a stable source of repayment. While some lenders may accept unemployment benefits as part of your income, they often require additional assurances, such as a co-borrower with steady employment or a significant down payment.
If you are currently receiving unemployment benefits, you should be prepared to show the duration and amount of your benefits. Lenders may ask for a benefits statement or letter from the unemployment office. However, because these benefits can end, lenders may be hesitant to approve a long-term loan based solely on this income. In such cases, demonstrating other sources of income, even sporadic gig work, can help. It is also wise to consider a co-borrower who has a traditional income to strengthen your application.
How a Co-Borrower Offsets Irregular Income
Adding a co-borrower to your auto loan application can significantly improve your chances of approval, especially if your income is irregular. A co-borrower is equally responsible for the loan, and their income and credit history are considered alongside yours. If you have unemployment income or gig work earnings that fluctuate, a co-borrower with a steady job can provide the stability lenders look for.
When choosing a co-borrower, consider someone with good credit and a reliable income stream. A family member or close friend who understands the commitment can be a good fit. Keep in mind that the co-borrower's debt-to-income ratio will also be evaluated, so adding them to the loan could affect their ability to borrow in the future. Both parties should fully understand the responsibilities involved. For those exploring options, platforms like AutoTitleLoan can connect you with lenders who are more open to nontraditional income profiles.
Strengthening Your Application With a Longer Income History
Lenders value consistency. The longer your income history, the easier it is for them to predict your future earnings. If you have been doing gig work for only a few months, consider waiting until you have at least a year of documented income before applying. This may not always be possible, but a longer history can lead to better terms and a higher chance of approval.
To build a strong income history, keep meticulous records. Save all 1099s, bank statements, and tax returns. If you have multiple income sources, maintain a spreadsheet that tracks your earnings and expenses. This not only helps you understand your financial picture but also provides clear documentation for lenders. Additionally, consider setting aside a portion of your gig income as a down payment. A larger down payment reduces the lender's risk and can compensate for a shorter income history.
Steps to Apply for a Car Loan With Nontraditional Income
Applying for a car loan when you have unemployment income or gig work only requires a strategic approach. Here is a step-by-step framework to guide you:
- Gather your documentation: Collect 1099s, bank statements, tax returns, and any benefits statements. Organize them by year and source.
- Determine your budget: Calculate how much you can afford for a monthly car payment, factoring in insurance, fuel, and maintenance. Lenders will look at your debt-to-income ratio, so keep your total debt obligations in mind.
- Check your credit score: Knowing your credit score helps you understand which lenders to target. If your score is low, consider working on improving it before applying.
- Find lenders that accept nontraditional income: Not all lenders are created equal. Look for lenders that specialize in self-employed borrowers or those with bad credit. StartAutoLoan.com can match you with lenders who understand gig income and unemployment benefits.
- Consider a co-borrower or larger down payment: These can offset the risk associated with irregular income and improve your approval odds.
Following these steps can streamline the process and increase your chances of securing financing. Remember that each lender has its own criteria, so applying to multiple lenders (within a short window to avoid credit score damage) can help you compare offers.
Common Pitfalls to Avoid
When applying for a car loan with unemployment income or gig work only, there are several pitfalls to watch out for. First, avoid overestimating your income. Lenders will verify your earnings, and discrepancies can lead to denial. Be honest and accurate. Second, do not ignore your debt-to-income ratio. Even with a co-borrower, too much existing debt can derail your application. Third, be wary of lenders that promise guaranteed approval but charge exorbitant fees or interest rates. Always read the fine print and compare offers.
Another pitfall is neglecting to maintain a stable banking history. Lenders prefer to see regular deposits and a positive account balance. Overdrafts or insufficient funds can signal financial instability. Finally, if you are using unemployment benefits, be prepared for lenders to view your income as temporary. Having a plan for when benefits end, such as a job offer or additional gig work, can reassure lenders.
Final Thoughts on Securing Financing
Securing a car loan with unemployment income or gig work only is challenging but far from impossible. The key lies in understanding how lenders evaluate nontraditional income and presenting your financial picture in the best possible light. By providing comprehensive documentation, considering a co-borrower, and building a longer income history, you can strengthen your application and drive off the lot with confidence. StartAutoLoan.com is here to connect you with lenders who are experienced in working with borrowers like you, so you can explore your options and find the financing that fits your situation.