Beyond Monthly Payment: Hidden Costs of Car Ownership
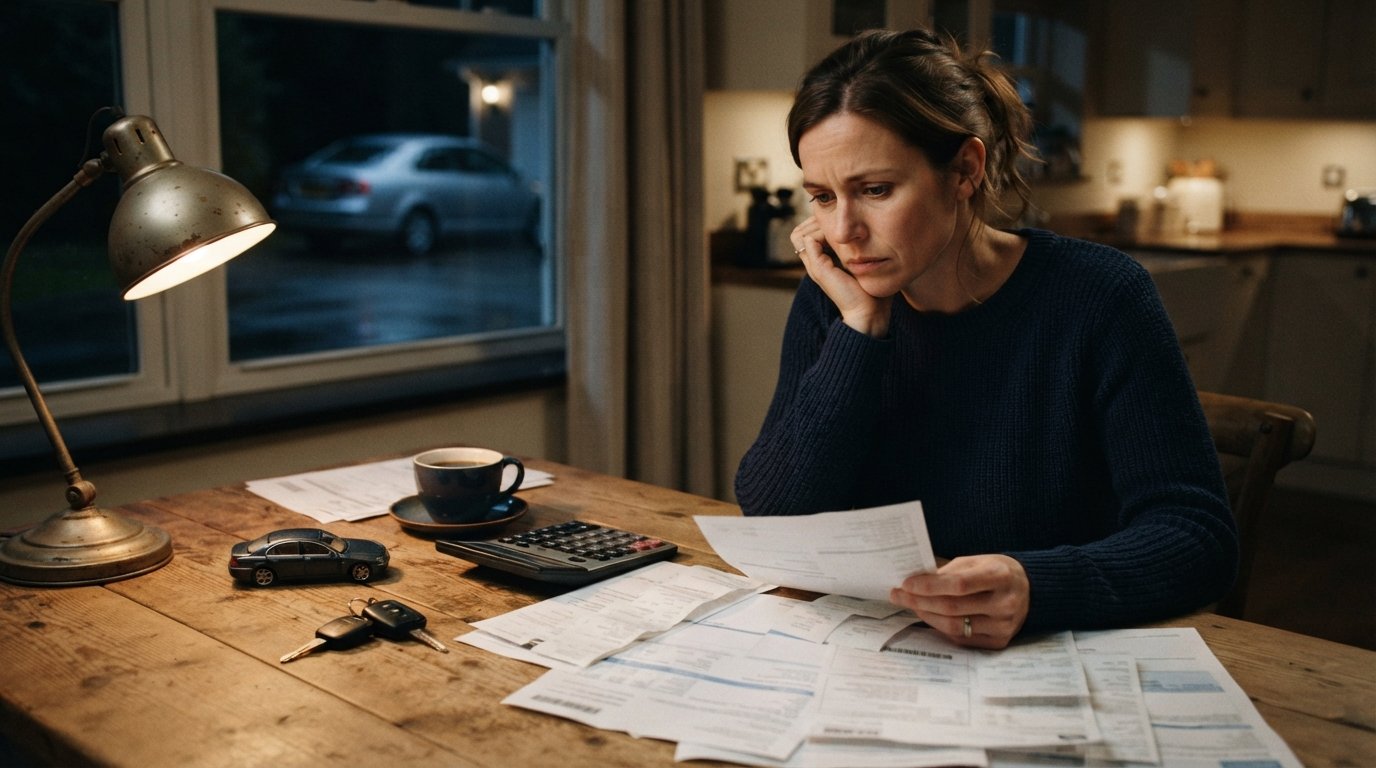
Beyond monthly payment hidden costs of car ownership add up fast. Budget for insurance, fuel, and repairs to avoid surprise bills.
By Olivia Ramirez
That shiny new car in the driveway comes with a sticker price, but the real financial commitment runs far deeper than the number on the window. Most buyers focus on the monthly payment, negotiating tirelessly to fit it into their budget. Yet the monthly loan payment is only one slice of a much larger pie. Insurance premiums, fuel, maintenance, repairs, registration fees, taxes, and depreciation all chip away at your wallet long after you drive off the lot. Understanding these beyond monthly payment hidden costs of car ownership is essential for anyone who wants to avoid financial strain and make a truly informed purchase decision.
For buyers with challenged credit or those navigating auto financing for the first time, these extra costs can be especially overwhelming. StartAutoLoan.com exists to help connect you with financing options that fit your situation, but even the best loan terms cannot protect you from the ongoing expenses of owning a vehicle. This article breaks down every major hidden cost so you can budget accurately and avoid unpleasant surprises.
The True Cost of Ownership: More Than a Loan
When you sign a car loan, you commit to a monthly payment for a set number of months. That payment covers the principal and interest on the amount you borrowed. It does not cover insurance, fuel, maintenance, or any of the other expenses that come with putting a car on the road. According to numerous industry studies, the average American spends thousands of dollars per year beyond their loan payment just to keep their vehicle operational and legal.
For example, a $15,000 car loan might come with a $300 monthly payment. But the total monthly cost of ownership could easily exceed $700 when you factor in insurance, gas, and maintenance. If you are not prepared for those additional expenses, you could find yourself struggling to make ends meet. This is why financial experts recommend budgeting for the total cost of ownership, not just the loan payment.
If you want to understand how loan terms and rates affect your monthly obligation, our guide on $15,000 car loan monthly payment breaks down the numbers in detail. But remember, that is just the starting point. The following sections explore the many other costs you will encounter.
Insurance: A Mandatory and Variable Expense
Auto insurance is required in nearly every state. Lenders also require comprehensive and collision coverage when you finance a vehicle, because they want to protect their investment. Insurance premiums vary widely based on factors like your age, driving record, location, credit score, and the type of vehicle you drive. For drivers with bad credit, insurance rates can be significantly higher, adding hundreds of dollars to your annual expenses.
Many first-time buyers are shocked to learn that their insurance premium can rival their car payment. A young driver with a new sports car might pay $400 or more per month for full coverage. Even a middle-aged driver with a clean record can expect to pay $100 to $200 monthly. Over the life of a five-year loan, that adds up to thousands of dollars that many buyers never factored into their budget.
To keep insurance costs manageable, consider these strategies:
- Shop around and compare quotes from multiple insurers before you buy a car.
- Choose a vehicle with safety features and a lower theft rate, as these can reduce premiums.
- Increase your deductible if you can afford to pay more out of pocket in the event of a claim.
- Ask about discounts for safe driving, bundling policies, or low annual mileage.
Even with these tactics, insurance remains a significant ongoing cost. It is not optional, and it does not go away when the loan is paid off. You will need insurance for as long as you own and drive the car.
Fuel, Maintenance, and Repairs: The Recurring Costs
Fuel is one of the most obvious ongoing expenses, but its impact varies dramatically based on your driving habits and the vehicle's fuel efficiency. A commuter who drives 15,000 miles per year in a car that gets 25 miles per gallon will spend roughly $1,800 annually on gas at $3 per gallon. A less efficient vehicle or a longer commute can push that number much higher. Electric vehicles reduce fuel costs but come with their own charging expenses and higher upfront prices.
Maintenance and repairs are another category that many buyers underestimate. Routine maintenance includes oil changes, tire rotations, brake inspections, fluid replacements, and more. These services are necessary to keep your car running safely and to preserve its value. The average driver spends $500 to $1,000 per year on routine maintenance alone. As a car ages, repair costs increase. A new transmission can cost $3,000 to $5,000, and even minor repairs like replacing a starter or alternator can set you back several hundred dollars.
To avoid being blindsided by repair bills, set aside a dedicated maintenance fund each month. Even $50 to $100 per month can help you cover unexpected repairs without resorting to credit cards or emergency loans. Regularly servicing your vehicle also helps you catch small problems before they become expensive ones.
Depreciation: The Silent Budget Killer
Depreciation is the decline in your car's value over time. It is not a bill you pay directly, but it represents a real financial loss, especially if you plan to sell or trade in your vehicle. New cars typically lose 20 percent of their value in the first year and about 60 percent over five years. That means a $30,000 new car could be worth only $12,000 after five years.
Depreciation matters because it affects your equity in the vehicle. If you finance a car with a small down payment and the car depreciates faster than you pay down the loan, you can end up owing more than the car is worth. This situation, known as being upside down or having negative equity, can make it difficult to sell or trade in the car without paying the difference out of pocket.
To mitigate depreciation, consider buying a gently used car instead of a brand-new one. The first owner absorbs the steepest depreciation, leaving you with a vehicle that still has plenty of life left but costs significantly less. Research the depreciation rates of different models before you buy, and choose a car known for holding its value.
Registration, Taxes, and Government Fees
Every state charges registration fees, and many also levy personal property taxes or excise taxes on vehicles. These fees vary widely but can easily amount to several hundred dollars per year. In some states, the fee is based on the vehicle's value, so a more expensive car means a higher annual bill. You will also pay sales tax when you purchase the vehicle, which can add thousands of dollars to the upfront cost.
In addition to registration, you may face fees for title transfer, license plates, and emissions testing. If you move to a different state, you will need to re-register your car and pay the associated fees. These costs are often overlooked during the excitement of buying a car, but they are mandatory and recurring.
To estimate your annual registration and tax burden, check with your state's Department of Motor Vehicles. Some states offer online calculators that let you estimate fees based on the vehicle's make, model, and year. Budgeting for these expenses in advance can prevent a cash flow crunch when the bills arrive.
The Impact of Hidden Costs on Your Overall Financial Health
When you add up insurance, fuel, maintenance, repairs, depreciation, registration, and taxes, the total cost of ownership can be staggering. For many households, these hidden costs exceed the monthly loan payment itself. If you have not planned for them, you may find yourself dipping into savings, using credit cards, or falling behind on other financial obligations.
This is particularly true for buyers with bad credit or those who are already stretching their budget to afford a car. A loan approval is not a green light to ignore the bigger picture. Before you commit to any financing, take the time to calculate the full monthly cost of ownership. Include every expense, from the obvious to the obscure, and make sure it fits comfortably within your budget.
If you are struggling to find affordable financing, remember that StartAutoLoan.com is not a lender but a connection service that can match you with lenders and dealers who work with challenged credit. Even so, the responsibility for budgeting for ongoing costs rests with you. Being proactive and informed is the best way to protect your financial well-being.
For those considering refinancing to lower their monthly payment, platforms like CarLoanRefinancing offer educational resources and tools that can help you explore your options. However, refinancing only addresses the loan itself, not the other ownership costs discussed here. A holistic approach is essential.
How to Budget for the Full Cost of Ownership
Creating a realistic budget for car ownership requires research and honesty about your driving habits and financial situation. Start by estimating each category of expense based on your specific circumstances. Use online calculators for fuel and insurance, and consult maintenance schedules for your chosen vehicle. Do not forget to account for depreciation, even though it is not a cash outlay.
Here is a simple framework to follow:
- Calculate your monthly loan payment using the loan amount, interest rate, and term.
- Get insurance quotes for the specific make and model you plan to buy.
- Estimate monthly fuel costs based on your average miles driven and the car's fuel economy.
- Set aside a monthly amount for maintenance and repairs, aiming for at least $50 to $100.
- Research annual registration fees and taxes, and divide by 12 to get a monthly equivalent.
- Add a buffer for unexpected expenses, such as a major repair or a spike in insurance rates.
Once you have a total, compare it to your monthly income and other obligations. If the total feels unmanageable, consider a less expensive vehicle, a larger down payment, or a longer loan term to reduce the monthly payment. Just be aware that a longer term means paying more interest over time and potentially staying upside down longer.
Strategies to Minimize Hidden Costs
While you cannot eliminate all ownership costs, you can take steps to keep them under control. One of the most effective strategies is to choose a vehicle that is reliable, fuel-efficient, and inexpensive to insure. A used sedan from a brand known for longevity often costs far less to own than a new luxury SUV.
Another strategy is to maintain your vehicle diligently. Regular oil changes, tire rotations, and brake checks can prevent costly breakdowns and extend the life of your car. A well-maintained car also retains more of its value, which helps with depreciation. Driving conservatively and avoiding aggressive acceleration can improve fuel economy and reduce wear and tear.
When it comes to insurance, review your policy annually and compare rates. Loyalty does not always pay. If you have improved your credit score or driving record, you may qualify for lower premiums. Raising your deductible can lower your monthly premium, but make sure you have enough savings to cover the higher out-of-pocket cost if you need to file a claim.
Finally, consider whether you truly need a car for every driver in the household. Sharing a vehicle, using public transit, or carpooling can dramatically reduce fuel, insurance, and maintenance costs. For some families, the savings from going car-light can be substantial.
Understanding the beyond monthly payment hidden costs of car ownership empowers you to make better financial decisions. Whether you are a first-time buyer or someone with past credit challenges, knowing what to expect can save you from stress and debt. StartAutoLoan.com is here to help you navigate the financing side, but the broader education is yours to embrace. Budget wisely, plan for the unexpected, and enjoy the ride without financial regret.