Auto Loans in Virginia: A 2026 Guide to Approval
Navigate auto loans in Virginia with confidence. Learn how to secure approval, compare rates, and improve your odds even with bad credit.
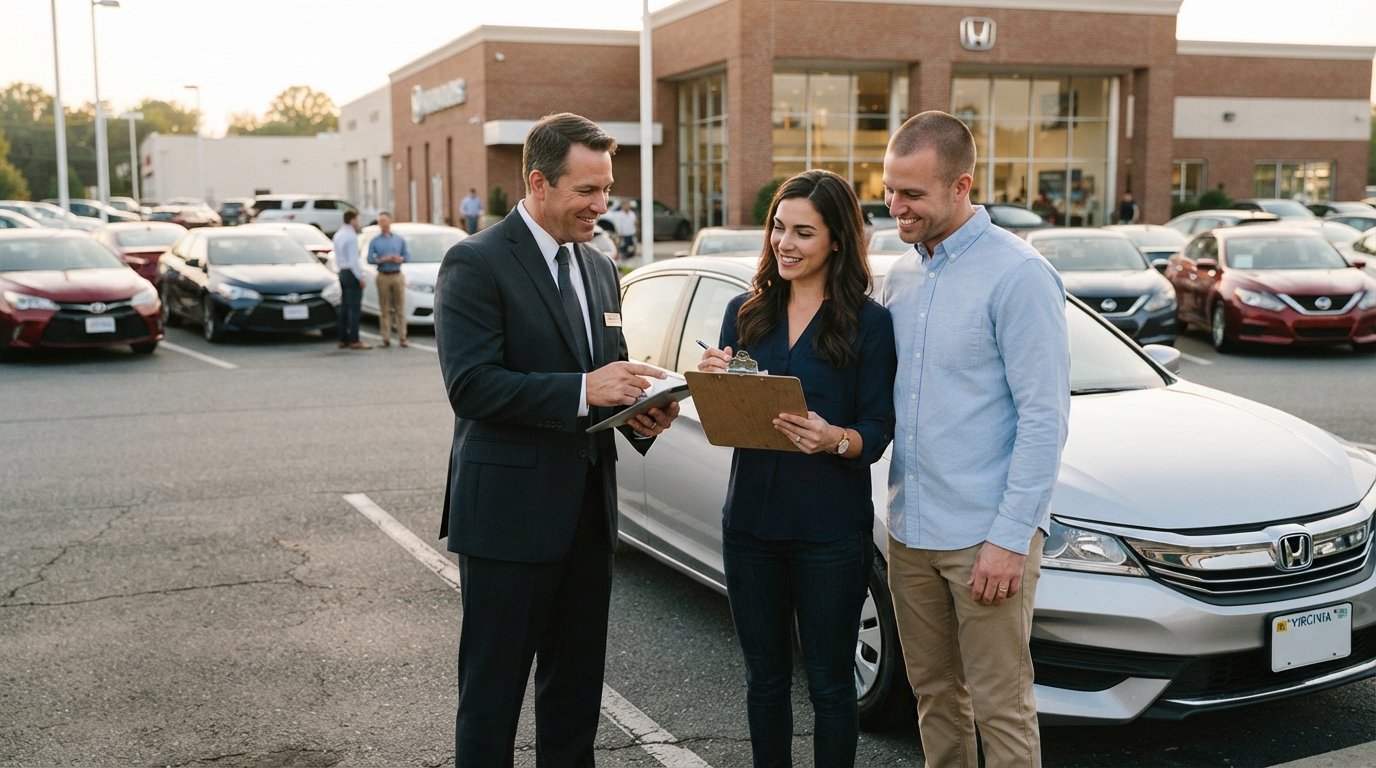
Finding the right financing for a vehicle in the Old Dominion can feel like navigating a maze of dealership offers, bank requirements, and credit hurdles. Whether you are buying a new truck for work in Richmond, a reliable sedan for commuting in Northern Virginia, or a first car for a teenager in Virginia Beach, the process of securing auto loans in Virginia starts with understanding your options and knowing where to look. This guide breaks down how vehicle financing works in the state, what lenders look for, and how you can position yourself for approval even if your credit history is less than perfect.
How Auto Loans in Virginia Work
Auto loans in Virginia function similarly to vehicle financing in other states: a lender provides funds to purchase a car, and you repay the loan with interest over a set term, typically 24 to 84 months. The loan is secured by the vehicle, meaning the lender holds a lien on the title until the debt is satisfied. What sets Virginia apart is a mix of state-specific regulations, a competitive lending market that includes national banks, local credit unions, and dealership financing, and a wide range of vehicle needs from rural trucks to urban commuters.
When you apply for auto loans in Virginia, lenders evaluate several factors: your credit score, income stability, debt-to-income ratio, the loan amount relative to the vehicle value (LTV), and the term length. A higher credit score and larger down payment generally lead to better interest rates. However, Virginia lenders also consider alternative data and may offer options for those with bad credit or no credit history. Understanding these criteria helps you shop smarter and avoid surprises at the dealership.
Another key aspect is the titling and registration process. Virginia requires that the lienholder be recorded on the title, and the lender typically handles this paperwork. You will also need to pay Virginia's motor vehicle sales tax (currently 4.15% for most vehicles, with additional local fees in some regions) and registration fees. Some lenders allow you to roll these costs into the loan, which increases the total amount financed. Being aware of these extra costs helps you budget accurately and avoid overborrowing.
Types of Auto Financing Available in Virginia
Virginia's lending landscape offers multiple avenues for vehicle financing, each with its own advantages and considerations. The best choice depends on your credit profile, whether you are buying new or used, and your timeline for approval.
Traditional Bank and Credit Union Loans
Banks and credit unions in Virginia often provide competitive rates, especially for members with strong credit. Credit unions, in particular, may offer lower rates and more flexible terms for members. However, their approval criteria can be strict, and applicants with bad credit or no credit history may face rejection. It helps to establish a relationship with a local credit union before applying, as some consider your history with them in the decision.
Dealership Financing
Many Virginia dealerships work with a network of lenders to offer on-the-spot financing. This convenience can be appealing, but it is important to compare the terms with outside offers. Dealership financing sometimes includes markup on the interest rate, so reviewing the contract carefully is essential. Some dealers specialize in helping buyers with challenged credit, which can be a valuable resource if traditional lenders have turned you down.
Online Connection Services
Online platforms that connect borrowers with lenders have become increasingly popular for auto loans in Virginia. These services allow you to submit one application and receive multiple offers from participating lenders and dealers. For individuals who have faced rejection elsewhere, a connection service can broaden your options without requiring you to visit multiple banks. One such platform is AutoTitleLoan, which connects consumers with financing options, including those with bad credit or past bankruptcies. It is not a direct lender but a connection service that helps match you with potential lenders.
Strategies to Improve Your Approval Odds
Securing auto loans in Virginia requires preparation, especially if your credit is less than stellar. Lenders want to see that you can manage a new monthly payment, so demonstrating financial responsibility is key. Start by checking your credit reports for errors and disputing any inaccuracies, as this can raise your score quickly. Next, save for a down payment: a larger down payment reduces the lender's risk and can offset a lower credit score. Even 10% down can make a difference.
Another effective strategy is to get preapproved before you shop. Preapproval gives you a clear budget and shows sellers you are serious, and it can streamline the buying process. Many Virginia lenders offer online preapproval with no impact to your credit score. Additionally, consider adding a cosigner with good credit; this can significantly improve your chances of approval and secure a lower interest rate. Finally, be realistic about the vehicle you can afford: lenders are more likely to approve a loan for a car that holds its value and fits within your budget.
If you have bad credit, you might think that auto loans in Virginia are out of reach, but that is not the case. Many lenders specialize in bad credit auto loans and will consider your income and down payment more heavily than your score. It is also worth exploring whether you can improve your credit before applying by paying down balances and avoiding new credit inquiries. For a deeper dive into strategies for approval, see our guide on auto loans with bad credit.
Understanding Rates and Terms in Virginia
Interest rates for auto loans in Virginia vary based on your credit score, loan term, vehicle age, and lender. As of 2026, average rates for new cars range from about 5% for excellent credit to over 15% for subprime borrowers. Used car rates tend to be slightly higher. Shopping around is crucial: even a difference of 1% can save you hundreds of dollars over the life of the loan. Do not accept the first offer you receive; compare at least three quotes from different sources.
Loan terms also matter. Longer terms lower your monthly payment but increase the total interest paid and can leave you upside down (owing more than the car is worth). A general rule is to keep your term at 60 months or less for new cars and 48 months or less for used cars. Be sure to factor in the total cost of ownership, including insurance, maintenance, and Virginia's personal property tax, which is assessed annually on vehicles. Some counties have higher rates than others, so check with your local commissioner of revenue.
Step-by-Step: Getting Auto Loans in Virginia
Ready to finance your next vehicle? Follow this roadmap to streamline the process and increase your chances of a favorable outcome.
- Check your credit and budget. Obtain your credit reports and scores, and calculate how much you can comfortably afford for a monthly payment. Aim for a payment that is no more than 15% of your take-home pay.
- Save for a down payment. A down payment of at least 10% to 20% reduces your loan amount and signals financial responsibility to lenders.
- Get preapproved. Apply for preapproval with multiple lenders, including banks, credit unions, and online services. Preapproval does not obligate you to borrow and gives you a negotiating edge.
- Shop for your vehicle. With preapproval in hand, negotiate the price of the car separately from the financing. This prevents the dealer from conflating the two and helps you stay within budget.
- Finalize the loan and paperwork. Review all terms, including the APR, fees, and total cost. Ensure the lien is recorded correctly and that you understand the repayment schedule.
Following these steps can demystify the process and help you avoid common pitfalls. Remember that auto loans in Virginia are a competitive market, so taking the time to compare offers is worth the effort.
Special Programs and Resources for Virginia Borrowers
Virginia offers several resources that can assist with vehicle financing. The Virginia Department of Motor Vehicles provides detailed information on titling, registration, and fees. For low-income residents, there may be assistance programs for transportation, though these are typically for specialized needs. Additionally, Virginia law requires that auto loan interest rates not exceed certain usury limits, which vary by loan amount and lender type; most mainstream lenders operate well within these limits.
First-time buyers in Virginia can benefit from programs offered by the Virginia Housing Development Authority (VHDA) for home loans, but for auto loans, it is best to work with lenders that specialize in first-time buyers. Many credit unions and online platforms offer educational resources and lenient criteria for those with no credit history. If you are a first-time buyer, look for lenders that report to credit bureaus, as this helps you build credit for future purchases.
For those with challenged credit, non-profit credit counseling agencies in Virginia can provide guidance on budgeting and credit repair. These services are often low-cost or free and can help you improve your credit profile before applying for auto loans in Virginia. Keep in mind that quick-fix credit repair scams should be avoided; legitimate counseling focuses on long-term financial health.
Common Pitfalls to Avoid
Even with preparation, some borrowers stumble into traps that cost them money. One common mistake is focusing solely on the monthly payment and ignoring the total cost of the loan. A low monthly payment over a long term can mean thousands more in interest. Another pitfall is accepting add-ons like extended warranties or gap insurance without evaluating whether they are necessary or fairly priced. While these products can offer peace of mind, they should be considered separately from the financing decision.
Another risk is borrowing more than the vehicle is worth. If you have negative equity from a previous loan, rolling it into a new loan can leave you upside down from the start. It is often better to pay down negative equity before trading in. Finally, be wary of lenders that pressure you to sign quickly or refuse to provide written terms. Reputable lenders encourage comparison shopping and provide clear disclosures.
Frequently Asked Questions About Auto Loans in Virginia
Can I get an auto loan in Virginia with bad credit?
Yes, many lenders in Virginia offer bad credit auto loans. These loans typically come with higher interest rates and may require a larger down payment, but they can help you get into a vehicle and rebuild your credit. Online connection services can match you with lenders that specialize in challenged credit.
What credit score do I need for a car loan in Virginia?
There is no universal minimum, but most traditional lenders prefer a score of 600 or higher. Some lenders work with scores as low as 500, especially if you have a strong down payment or a cosigner. Credit unions and online lenders may be more flexible than large banks.
How much can I borrow for a car in Virginia?
Loan amounts vary by lender and your credit profile. Some lenders offer up to $50,000 or more for new vehicles. However, it is wise to borrow only what you can comfortably repay. Use an auto loan calculator to estimate monthly payments and total interest.
Are there penalties for paying off my auto loan early in Virginia?
Most auto loans in Virginia do not have prepayment penalties, but it is essential to check your loan agreement. Some lenders may charge a fee if you pay off the loan before a certain period. Always read the fine print and ask about prepayment terms before signing.
How does Virginia's personal property tax affect my auto loan?
Virginia assesses a personal property tax on vehicles annually, separate from the auto loan. This tax is based on the vehicle's value and varies by locality. It is not included in your loan payment, so you should budget for it separately. Some lenders may offer to escrow the tax, but this is uncommon for auto loans.
Navigating auto loans in Virginia does not have to be overwhelming. With the right information and a strategic approach, you can secure financing that fits your budget and credit situation. Whether you are a first-time buyer or looking to refinance, take advantage of the resources and competition in the Virginia lending market to get the best possible terms.