Auto Loan Virginia: Smart Financing for Every Credit Profile
Find the best auto loan Virginia offers for bad credit, first-time buyers, and refinancing. Compare options and get approved in as little as 24 hours.
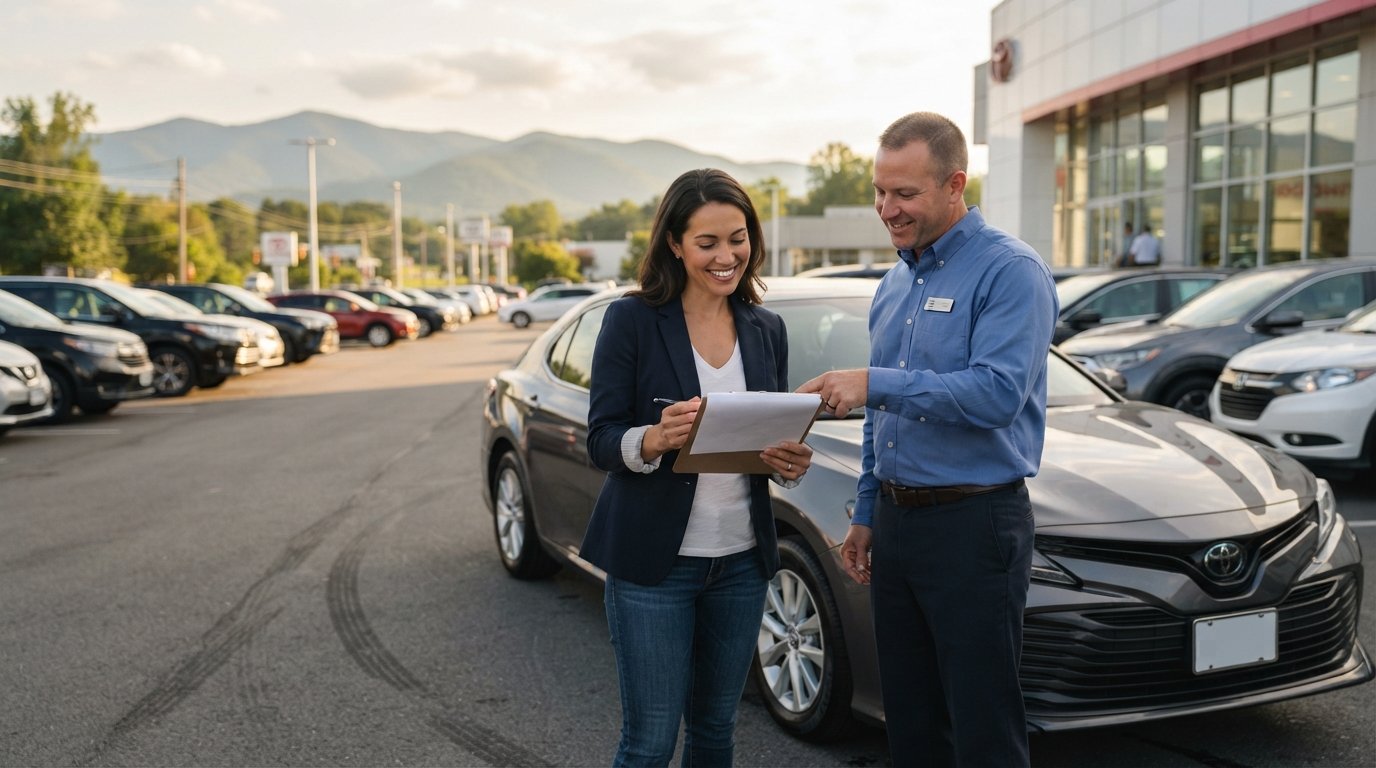
Finding the right auto loan in Virginia can feel like navigating a maze, especially if you have bad credit, no credit history, or a past bankruptcy. But here is the truth: Virginia drivers have more options than they realize, and the right strategy can turn a rejection letter into an approval. Whether you are buying a new car in Richmond, a used truck in Norfolk, or refinancing an existing loan in Arlington, understanding how auto loan Virginia works is your first step toward better terms and real savings.
How Auto Loans Work in Virginia
Virginia is a lender-friendly state with a wide range of financing sources, including banks, credit unions, online lenders, and dealership financing. The state does not cap auto loan interest rates, which means your credit profile and the lender you choose have a big impact on what you pay. That is why shopping around is not just a suggestion, it is a necessity. A difference of even two percentage points on a $25,000 loan can save you hundreds of dollars over the life of the loan.
Most Virginia auto loans are simple interest loans with terms ranging from 36 to 84 months. Shorter terms mean higher monthly payments but less total interest, while longer terms lower your payment but increase the overall cost. The key is finding a balance that fits your budget without stretching you too thin. Lenders in Virginia also consider factors beyond your credit score, including income stability, debt-to-income ratio, and down payment size. If you have been turned down by a traditional bank, it does not mean you cannot get financed. It means you need to look at alternative channels, including subprime lenders and dealer networks that specialize in challenging credit situations.
Where to Find Auto Loans in Virginia
Virginia borrowers have several lending channels to explore, each with its own advantages and trade-offs. Banks and credit unions often offer the lowest rates for well-qualified buyers, but their approval standards are strict. Online lenders and connection services, like StartAutoLoan.com, match you with a network of lenders and dealers who work with a broader range of credit profiles. Dealership financing is convenient but can come with higher rates if you do not negotiate or compare offers first.
Credit unions deserve special mention, especially in Virginia where institutions like Navy Federal and Virginia Credit Union have strong auto lending programs. They often offer competitive rates and more flexible underwriting than big banks, particularly for members with established relationships. However, if you have bad credit or no credit, a connection service can be a faster path to approval because it pre-screens you against multiple lenders at once. Instead of filling out five applications and waiting days for responses, you submit one request and get matched with options that fit your profile. This approach saves time and reduces the number of hard inquiries on your credit report.
Bad Credit Auto Loans in Virginia: What You Need to Know
Having bad credit does not disqualify you from getting an auto loan in Virginia, but it does change the landscape. Subprime lenders in the state specialize in working with borrowers who have scores below 600, and some even work with scores in the 500s. These loans come with higher interest rates, but they also give you a chance to rebuild your credit through on-time payments. The key is to go in with realistic expectations and a plan.
Before you apply, gather the documents most Virginia lenders will ask for: proof of income, proof of residence, a valid driver's license, and proof of insurance. You will also need to show that you can afford the payment, which means your debt-to-income ratio should ideally be below 50 percent. A larger down payment can offset credit risk and improve your approval odds. If you have a bankruptcy in your past, do not panic. Virginia lenders can approve auto loans after bankruptcy, especially if the discharge is at least a year old and you have reestablished some positive credit history. The important thing is to be honest on your application and to work with a lender or connection service that understands your situation.
- Subprime lenders: Specialize in bad credit and no credit buyers, with higher rates but more flexible approval standards.
- Buy-here-pay-here dealerships: Offer in-house financing, often with high rates and strict payment terms, best used as a last resort.
- Connection services: Match you with multiple lenders and dealers who work with challenged credit, saving you time and inquiries.
- Credit unions: May offer second-chance programs or more lenient underwriting for members with past credit issues.
One strategy that works well in Virginia is to get preapproved through a connection service before you visit a dealership. This gives you a realistic budget and leverage when negotiating. It also prevents the dealer from running your credit through multiple lenders, which can hurt your score. If you are unsure where to start, services like AutoTitleLoan connect consumers with financing options and can be a useful resource for understanding what is available. The goal is to turn a bad credit situation into a stepping stone toward better credit and a reliable vehicle.
First-Time Buyers: Building Credit with a Virginia Auto Loan
If you have never had a car loan or credit card, you are not alone. Many first-time buyers in Virginia face the same challenge: no credit history means no score, and no score means lenders cannot assess your risk. The good news is that auto loans are one of the easiest types of credit to obtain when you have no history, because the car itself serves as collateral. Lenders are more willing to take a chance on a first-time buyer when they know they can repossess the vehicle if payments stop.
To improve your odds, consider these steps: save for a down payment of at least 10 to 20 percent, add a co-signer with good credit if possible, and choose a car that fits your budget rather than the other way around. You should also check your credit reports for errors before applying, because a mistake on your report could be holding you back. In Virginia, first-time buyer programs through credit unions and connection services can help you get approved with no credit history. StartAutoLoan.com specializes in connecting first-time buyers with lenders who understand their situation, and the application takes just minutes. The key is to make your payments on time every month, because that is how you build the credit history that will unlock better rates in the future.
Refinancing Your Auto Loan in Virginia
If you already have a car loan with a high interest rate, refinancing could save you money. Virginia borrowers refinance for several reasons: to lower their monthly payment, to shorten the loan term, or to remove a co-signer. Refinancing works by paying off your existing loan with a new loan that has better terms. The process is similar to getting a new auto loan, but the car is already yours, which simplifies things.
To qualify for refinancing in Virginia, you generally need to have made at least three to six months of on-time payments on your current loan, and your credit score should have improved since you originally financed. The vehicle also needs to meet certain age and mileage requirements, typically less than 10 years old and under 100,000 miles. If you have bad credit, refinancing can still be possible through subprime lenders, though the savings may be smaller. The best approach is to get quotes from multiple lenders and compare the annual percentage rate (APR), not just the monthly payment. A lower APR means more of your payment goes toward the principal, which helps you pay off the car faster and pay less interest overall.
Understanding Rates and Terms in Virginia
Auto loan rates in Virginia vary widely based on your credit score, loan term, vehicle type, and lender. As of 2026, average rates for new cars range from about 5 percent for excellent credit to over 14 percent for bad credit. Used car rates are typically higher, sometimes by two to three percentage points. These are averages, though, and the rate you qualify for depends on your specific situation. That is why it is important to shop around and get personalized quotes rather than relying on advertised rates.
When comparing auto loan offers, look beyond the interest rate. Consider the origination fees, prepayment penalties, and any add-on products like extended warranties or gap insurance. A loan with a slightly higher rate but no fees could be cheaper than one with a low rate and high fees. Also, check whether the lender reports to the credit bureaus, because on-time payments can help you build credit. For a deeper dive into current rate trends and what they mean for your budget, see this guide on auto loan rates today. It breaks down how rates are set and how you can position yourself for the best possible offer.
Tips for Getting Approved in Virginia
Approval comes down to preparation. Before you apply for an auto loan in Virginia, take these steps to strengthen your application. First, pull your credit reports and dispute any errors. Second, calculate your debt-to-income ratio and pay down high balances if possible. Third, save for a down payment, even a small one can make a difference. Fourth, get preapproved so you know your budget and can negotiate from a position of strength. Finally, be honest about your income and employment history, because lenders will verify it.
If you have been rejected by a traditional lender, do not give up. Virginia has a robust network of alternative lenders and connection services that specialize in helping people with credit challenges. StartAutoLoan.com is one such service, and it is designed to match you with lenders who are likely to say yes. The application is secure and takes just minutes, and you could be contacted by a dealer or lender in as little as 10 minutes. Approval in 24 hours is possible for many applicants. The important thing is to take action and explore your options rather than assuming you cannot get financed.
Final Thoughts on Auto Loan Virginia
Getting an auto loan in Virginia does not have to be stressful, even if your credit is not perfect. By understanding your options, preparing your application, and shopping around, you can find financing that fits your budget and helps you move forward. Whether you are a first-time buyer, rebuilding after bad credit, or simply looking for a better rate, the Virginia auto loan market has something for you. Take the first step today, and you could be driving your next car sooner than you think.