Auto Loan Pre Approval vs Pre Qualification Difference
Understand the auto loan pre approval vs pre qualification difference and how each affects your rate, buying power, and dealership leverage.
By Jonathan Reed
You are standing in a dealership, keys in hand, ready to drive off the lot. Then the finance manager runs your credit and tells you the terms you expected are not the terms you get. The monthly payment jumps by eighty dollars, the interest rate climbs two points, and suddenly the car you budgeted for is out of reach. This scenario plays out every day, and it almost always traces back to one mistake: confusing pre qualification with pre approval. Understanding the auto loan pre approval vs pre qualification difference is not academic trivia. It is the difference between walking into a dealership as a negotiator with leverage and walking in as a hopeful buyer hoping the numbers work out. For borrowers with bad credit, no credit history, or a past bankruptcy, that difference matters even more, because the gap between an estimate and a commitment tends to be wider when lenders view your profile as higher risk.
This article breaks down exactly what each term means, how lenders treat them, and why the distinction can save you thousands of dollars over the life of your loan. You will also learn which one you should pursue first, how to use each to your advantage, and what to do if traditional banks have already turned you down.
Pre Qualification: A Quick Estimate, Not a Promise
Pre qualification is the looser of the two processes. It typically involves submitting basic information, your name, your income range, the type of vehicle you want, and sometimes a soft pull of your credit, and receiving a rough estimate of how much you might be able to borrow. The key word is might. A pre qualification letter or number is not a commitment from any lender. It is a snapshot based on limited data, and it comes with significant caveats.
Most pre qualification processes rely on a soft credit inquiry, which does not affect your credit score. That sounds appealing, and it is, but it also means the lender has not done a deep review of your financial profile. They have not verified your income, examined your debt to income ratio in detail, or scrutinized your credit report for anomalies. As a result, the estimated loan amount and interest rate you receive during pre qualification can shift dramatically once you move to the next stage.
Pre qualification serves a useful purpose as an early filtering tool. It helps you understand the general ballpark of what you can afford and prevents you from wasting time at dealerships or with lenders whose minimum requirements you clearly do not meet. But it should never be treated as a green light to start shopping with confidence. Here is what pre qualification typically involves:
- Basic personal and financial information (name, address, income range)
- A soft credit pull that does not impact your score
- An estimated loan range and sometimes an estimated rate
- No verification of income, employment, or existing debts
- No binding commitment from the lender
Because pre qualification is so preliminary, it is also fast. You can often complete the process in a few minutes online. That speed makes it a convenient first step, especially if you are months away from buying and just want to start planning. However, if you are ready to buy now, or if you have already been rejected by traditional lenders, pre qualification alone will not give you the certainty you need. You need something stronger.
Pre Approval: A Conditional Commitment With Real Weight
Pre approval goes several steps further. During pre approval, the lender conducts a hard credit inquiry, which does temporarily affect your credit score, usually by a few points. In exchange for that inquiry, the lender performs a much deeper review of your finances. They verify your income, check your employment, calculate your debt to income ratio, and assess your overall creditworthiness with far more rigor than they would during pre qualification.
The result is a conditional commitment. The lender is saying, in effect: based on what we have verified, we are willing to lend you up to this amount at this rate, provided the vehicle meets our criteria and nothing changes in your financial situation. That conditional commitment carries real weight when you sit down at the dealership. You are no longer a buyer hoping for approval. You are a buyer with financing already lined up, and that changes the entire negotiation dynamic.
Pre approval letters typically include the loan amount, the interest rate, the term length, and any conditions that must be met before final funding. Those conditions might include a maximum mileage limit on the vehicle, a minimum down payment, or proof of insurance. As long as you satisfy those conditions, the lender is committed to the loan. This is why pre approval is the gold standard for car buyers, especially those who have faced financing challenges in the past. If you have bad credit and have been turned down before, exploring auto loan pre approval for bad credit borrowers can help you understand how to approach lenders who specialize in your situation.
Why the Difference Matters at the Dealership
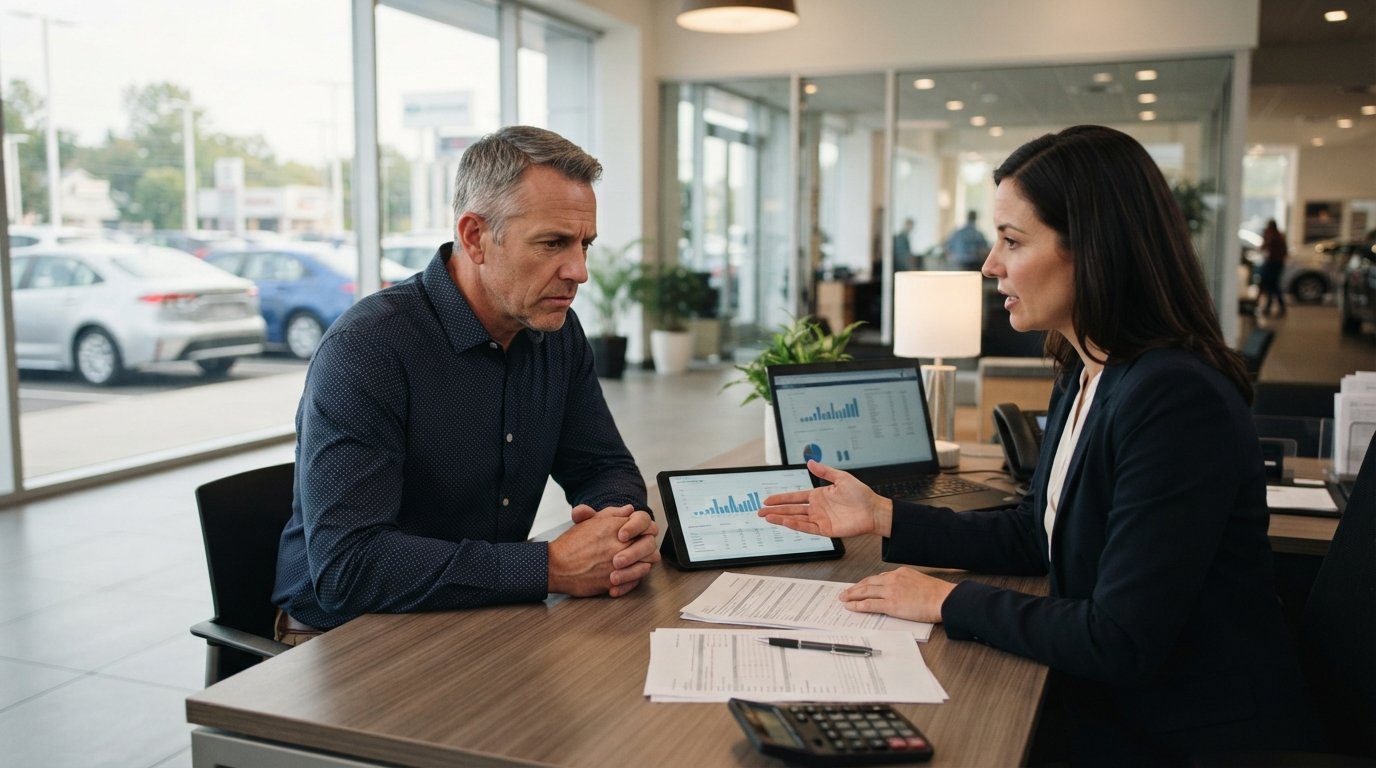
The gap between pre qualification and pre approval becomes painfully clear at the dealership. When you arrive with only a pre qualification, the finance manager knows you have not been fully vetted. They may use that as an opening to present you with terms that are less favorable than what you expected, or to steer you toward financing options that benefit the dealership rather than you. You are in a weaker position because you do not have a competing offer to fall back on.
When you arrive with a pre approval letter, the dynamic shifts. You know exactly what rate you qualify for and how much you can borrow. If the dealership offers you a better rate, great. If they offer you a worse one, you can simply use your pre approval instead. You have options, and options equal leverage. This is especially important for borrowers with challenged credit, who are more likely to be offered subprime rates with unfavorable terms. A pre approval from a lender who has already reviewed your profile gives you a benchmark against which to compare any dealer financing offer.
There is also a practical timing consideration. Pre approvals usually have an expiration window, often thirty to sixty days. That window gives you a defined period during which you can shop with confidence, knowing your financing is locked in. Pre qualifications may not have the same formal structure, and their estimates can change at any time. If you are serious about buying, the clock on a pre approval also creates a helpful sense of urgency that can keep your car search focused.
How Lenders View Each Process
From the lender's perspective, pre qualification and pre approval are two very different risk assessments. Pre qualification is a marketing tool as much as anything else. It allows lenders to cast a wide net, collecting leads from consumers who are early in the buying process. The estimates provided are intentionally broad because the lender has not invested the resources to verify anything. They are not on the hook for those numbers.
Pre approval, by contrast, represents a real investment of time and analysis. The lender has pulled your full credit report, verified your income, and run your numbers through their underwriting models. They have made an internal decision to extend credit, subject to conditions. That decision is not something they take lightly, and it is not something they will easily walk back. This is why a pre approval letter carries so much more weight, both in your mind and in the minds of dealership finance managers.
For borrowers with bad credit or no credit history, the lender's perspective is even more critical. These borrowers often need to work with lenders who specialize in subprime or alternative financing. Those lenders may have different pre qualification and pre approval processes, and understanding how they evaluate risk can help you present your strongest case. A platform like CarLoanRefinancing can provide educational resources and rate comparisons that help you understand what lenders are looking for before you apply.
Which Should You Get First?
The short answer is both, but in the right order. Start with pre qualification if you are in the early stages of research and want a general sense of your borrowing range. It is quick, it does not hurt your credit, and it can help you narrow your search to vehicles that fit your budget. Once you are within a month or two of buying, move to pre approval. That is when you need a firm commitment, not an estimate.
If you have already been rejected by traditional lenders, you may want to skip pre qualification entirely and go straight to pre approval with lenders who work with challenged credit. The pre qualification stage is most useful when you have a reasonable expectation of approval. If that expectation is uncertain, the deeper review of pre approval will give you a clearer answer faster. Here is a simple framework to decide:
- If you are more than three months from buying: start with pre qualification to establish a budget range.
- If you are one to three months from buying: pursue pre approval to lock in your terms.
- If you have bad credit or have been rejected before: go directly to pre approval with lenders who specialize in your situation.
- If you are already at the dealership: do not sign anything until you have a pre approval letter in hand.
Following this sequence helps you avoid the most common mistake, which is arriving at the dealership with only a pre qualification and assuming it is as good as a pre approval. It is not, and the difference can cost you real money.
Common Myths About Pre Qualification and Pre Approval
There is a lot of misinformation about these two processes, and it often leads borrowers astray. One persistent myth is that pre qualification and pre approval are basically the same thing, just with different names. They are not. The depth of review, the binding nature of the commitment, and the impact on your credit are all different. Treating them as interchangeable is a recipe for disappointment.
Another myth is that pre approval guarantees you will get the loan. It does not. Pre approval is conditional, and those conditions matter. If you change jobs, take on new debt, or choose a vehicle that does not meet the lender's criteria, the loan can fall through. Similarly, some borrowers believe that pre qualification hurts their credit score. It typically does not, because it usually involves a soft inquiry. Pre approval does involve a hard inquiry, but the impact is usually small and temporary, especially if you complete multiple pre approvals within a short window, which credit scoring models treat as a single inquiry.
A third myth is that you should always accept the dealership's financing because it is more convenient. Convenience has value, but it should not come at the cost of thousands of dollars in extra interest. Having a pre approval in hand gives you the ability to compare the dealership's offer against your own financing and choose the better deal. That comparison is only possible if you have done the work upfront.
Special Considerations for Bad Credit and First Time Buyers
If you have bad credit, no credit history, or a past bankruptcy, the pre approval vs pre qualification difference takes on added significance. Traditional lenders are often reluctant to work with borrowers in these categories, and the ones who do may offer less favorable terms. Getting a pre approval from a lender who specializes in challenged credit gives you a realistic picture of what you qualify for and protects you from being taken advantage of at the dealership.
First time buyers face a similar challenge. Without an established credit profile, it can be hard to know what to expect. Pre qualification can give you a rough starting point, but pre approval is what will actually get you into a car. Many first time buyer programs through credit unions and online lenders offer pre approval with more flexible criteria, and taking advantage of those programs can make the difference between driving home in a new car and continuing to take the bus.
For both groups, the key is to work with lenders and platforms that understand your situation. StartAutoLoan.com, for example, connects borrowers with a network of participating lenders and dealers who work with bad credit, no credit, and bankruptcy situations. Submitting a request through their platform can connect you with financing options that traditional banks would not offer, and it can help you move from pre qualification to pre approval more efficiently.
Practical Steps to Get Pre Approved
Getting pre approved does not have to be complicated, but it does require some preparation. Before you apply, gather your documents: proof of income, proof of employment, your driver's license, and your most recent bank statements. Check your credit report for errors and dispute anything that looks wrong. A single incorrect late payment notation can drag your score down and cost you a better rate.
Once your documents are in order, apply with more than one lender. Multiple pre approvals within a short window are typically treated as a single inquiry by credit scoring models, so you do not need to worry about a large score drop. Comparing offers from several lenders gives you the best chance of finding favorable terms. When you receive your pre approval letters, read the conditions carefully. Understand the maximum loan amount, the rate, the term, and any restrictions on the vehicle you can buy.
Finally, keep your financial situation stable between pre approval and closing. Do not change jobs, finance a large purchase, or open new credit cards. Any of those actions could invalidate your pre approval and force you to start over. Once you have your pre approval and you have found the right vehicle, you can move forward with confidence, knowing exactly what you are signing up for.
Understanding the auto loan pre approval vs pre qualification difference is one of the most valuable pieces of knowledge you can have as a car buyer. It shapes your budget, your negotiating power, and your monthly payment for years to come. Whether you have perfect credit or you are rebuilding after a financial setback, taking the time to get pre approved before you shop is a decision you will not regret.