Auto Loan for a Car With High Mileage and Bad Credit
Financing a high-mileage car with bad credit is possible with the right lender and strategy. Learn mileage cutoffs, down payment tips, and alternatives.
A car with 150,000 miles on the odometer and a credit score that has seen better days can feel like a double rejection waiting to happen. You need reliable transportation, but the vehicle you can afford has high mileage, and your credit history makes lenders nervous. The good news is that this combination does not automatically shut you out of financing. There are lenders and dealerships that specialize in exactly this situation, and understanding how they evaluate risk can help you walk into the process with realistic expectations and a stronger application.
The key is to stop thinking like a traditional bank and start thinking like a subprime lender. These lenders look at the whole picture: your income stability, your down payment, the vehicle's condition, and your willingness to accept terms that offset their risk. A high-mileage car with bad credit is not an impossible loan, but it does require a different strategy than someone buying a three-year-old sedan with a 750 credit score. This guide walks you through the mileage cutoffs lenders use, why your down payment matters more than ever, how to protect yourself with a proper inspection, and what to do if the specific car you want cannot be financed.
How Lenders View High-Mileage Vehicles and Bad Credit
Lenders use mileage and vehicle age as proxies for risk. A car with 120,000 miles has more wear on its engine, transmission, and suspension than one with 40,000 miles. When that car breaks down, the borrower may struggle to make payments, and the lender is left with a vehicle that is expensive to repossess and hard to sell. For borrowers with bad credit, the lender is already accepting a higher probability of default. Adding a high-mileage vehicle to that equation makes the loan even riskier, so lenders respond by tightening their approval criteria.
Most traditional banks and credit unions will not finance vehicles over a certain mileage threshold, often somewhere between 100,000 and 125,000 miles. Some draw the line at seven to ten years of vehicle age regardless of mileage. These cutoffs exist because the collateral value drops sharply as vehicles age, and lenders want to avoid being underwater on a loan if they need to repossess. However, subprime lenders and buy-here-pay-here dealerships operate with more flexibility. They may finance vehicles up to 150,000 miles or even higher, but they compensate for the added risk with higher interest rates and larger down payment requirements.
Your credit score affects which tier of lender will work with you. Borrowers with scores below 600 are typically classified as subprime, and those below 500 are deep subprime. At these levels, you are looking at interest rates that can range from 15% to 25% or more, depending on your state's usury laws and the lender's risk appetite. The combination of bad credit and high mileage means you should expect to work harder to find a lender, and you should be prepared to accept less favorable terms than someone with pristine credit. That said, the loan is still worth pursuing if it gets you reliable transportation and you can afford the payments.
Mileage and Age Cutoffs That Limit Financing
Understanding lender cutoffs helps you target your search and avoid wasted applications. Different lenders have different rules, but some common patterns emerge in the subprime auto lending space. The table below outlines typical thresholds, though you should confirm specifics with any lender or dealer you work with.
- Traditional banks and credit unions: Often cap financing at 100,000 to 125,000 miles and may require the vehicle to be less than seven to ten years old.
- Subprime lenders: May finance vehicles up to 150,000 miles, sometimes higher, with larger down payments and shorter loan terms.
- Buy-here-pay-here dealerships: Often finance vehicles up to 200,000 miles or more, but with very high interest rates and strict payment schedules.
- Credit unions with first-time buyer programs: Some have flexible mileage caps for members, especially if you have an established relationship.
These cutoffs are not arbitrary. They reflect the lender's assessment of how much the vehicle will be worth if they need to repossess it and how likely it is to need major repairs during the loan term. A vehicle with 180,000 miles might need a new transmission within a year, and that repair could cost more than the car is worth. Lenders know this, and they price the loan accordingly. Your job is to find the lender whose cutoff matches the vehicle you want and whose terms you can realistically afford.
It also helps to understand that mileage cutoffs can vary by vehicle type. Trucks and SUVs often have higher mileage limits because they hold their value better and are perceived as more durable. Economy cars with high mileage are harder to finance because their resale value drops faster. If you are shopping for a high-mileage vehicle, consider whether a truck or SUV might open more financing doors, even if the fuel costs are higher.
Why High-Mileage Vehicles Require Larger Down Payments and Shorter Terms
When a lender approves a loan for a high-mileage vehicle, they are taking on the risk that the car will depreciate faster than the loan balance decreases. To protect themselves, they require a larger down payment. A down payment does two things: it reduces the amount the lender has to finance, and it gives the borrower immediate equity in the vehicle. If you put 20% down on a $10,000 car, you owe $8,000, and the car is worth $10,000. If you default and the lender repossesses, they can sell the car and recover more of their money.
For borrowers with bad credit, the down payment requirement is often higher, sometimes 20% to 30% or more. On a $12,000 high-mileage vehicle, that means $2,400 to $3,600 upfront. This can be a barrier, but it is also an opportunity. A larger down payment reduces your monthly payment and the total interest you pay over the life of the loan. If you can save up a substantial down payment, you improve your chances of approval and reduce the cost of borrowing.
Shorter loan terms are the other tool lenders use to manage risk. A 72-month loan on a 10-year-old car with 130,000 miles is a recipe for being underwater for most of the loan term. The vehicle will continue to depreciate, and by the time the loan is paid off, it may be worth very little. Lenders prefer 36-month to 48-month terms for high-mileage vehicles, and some will not go beyond 60 months. Shorter terms mean higher monthly payments, but they also mean you pay less interest and you are less likely to owe more than the car is worth.
Here is a simple framework for thinking about down payment and term length: the older and higher-mileage the vehicle, the more you should put down and the shorter your term should be. If you cannot afford the monthly payment on a 36-month loan with 20% down, the vehicle may be too expensive for your budget, and you should look at a cheaper car or save more money before buying.
Inspection and Valuation Steps That Protect the Borrower
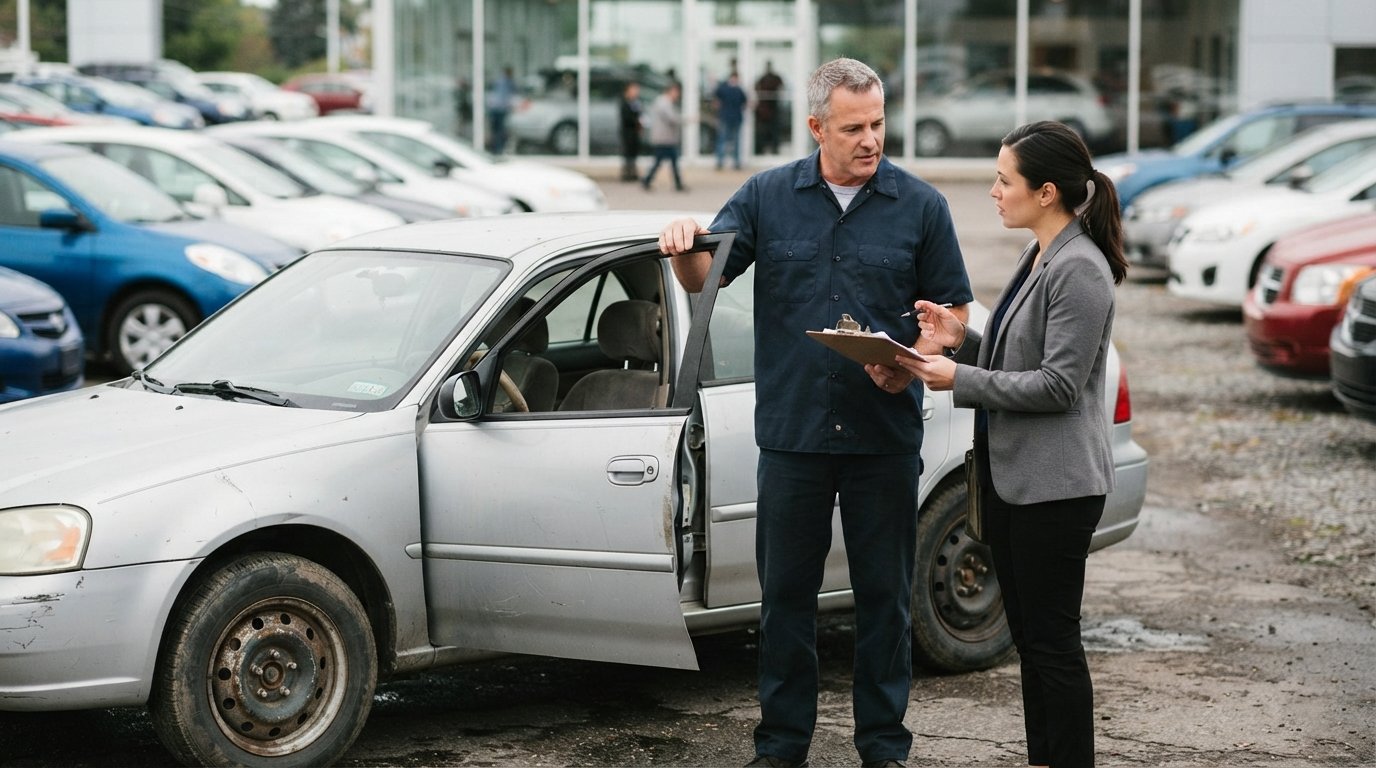
When you buy a high-mileage vehicle, the inspection is not optional. It is your best defense against buying a car that will need expensive repairs shortly after you drive it off the lot. A pre-purchase inspection by an independent mechanic costs $100 to $200 and can reveal problems that the seller may not disclose or may not even know about. Look for a mechanic who specializes in the type of vehicle you are considering, and ask for a compression test, a check of the transmission fluid, and a review of the suspension and brakes.
Valuation is the other half of the equation. Lenders will only finance up to a certain percentage of the vehicle's value, known as the loan-to-value ratio. If you are paying $10,000 for a car that the lender values at $8,000, you may need to cover the difference with a larger down payment. Use resources like Kelley Blue Book, NADA Guides, and local listings to get a sense of what the car is actually worth in your market. Do not rely solely on the seller's asking price, especially at a small dealership that may have inflated the price to accommodate financing fees.
Here are the steps to take before you commit to financing a high-mileage vehicle:
- Get a vehicle history report to check for accidents, title issues, and odometer rollback.
- Arrange a pre-purchase inspection with an independent mechanic.
- Research the vehicle's value using multiple sources and compare it to the asking price.
- Ask the seller for maintenance records, especially for major services like timing belt replacement and transmission fluid changes.
- Confirm the lender's mileage and age cutoffs before you apply, so you do not waste time on a vehicle that cannot be financed.
These steps protect you from overpaying and from buying a car that will drain your savings. They also strengthen your application because you can show the lender that you have done your homework and that the vehicle is worth the loan amount. If a seller refuses to allow an inspection, that is a red flag, and you should walk away.
How Loan-to-Value Thresholds Apply to Older Vehicles
Loan-to-value, or LTV, is the ratio of the loan amount to the vehicle's value. If you borrow $9,000 to buy a car worth $10,000, your LTV is 90%. Lenders use LTV to assess risk because it tells them how much they would lose if they had to repossess and sell the vehicle. A lower LTV means more equity and less risk for the lender. A higher LTV means the lender is exposed to more potential loss.
For high-mileage vehicles, lenders typically set stricter LTV limits. A traditional lender might allow 100% to 110% LTV on a newer car, but a subprime lender might cap LTV at 80% to 90% for a high-mileage vehicle. That means if the car is worth $10,000, the lender will only finance $8,000 to $9,000, and you need to cover the rest with a down payment or trade-in. If you are upside down on a trade-in, meaning you owe more than the car is worth, that negative equity can make it even harder to get approved for a high-mileage vehicle.
Understanding LTV helps you negotiate. If the seller is asking $12,000 for a car that the lender values at $9,000, you have a problem. You can try to negotiate the price down, or you can find a different vehicle that is priced more in line with its value. You can also look for a vehicle that holds its value better, such as a Toyota or Honda with high mileage, because lenders may be more willing to finance a vehicle with a strong reputation for reliability. To see how current rates and lender criteria are shifting, our guide on auto loan rates today explains what borrowers should expect in the current market.
It also helps to know that some lenders will finance the vehicle's value plus taxes, title, and fees, while others will not. If you are buying from a dealership, the dealer may try to roll fees into the loan, which increases your LTV. Ask for a breakdown of all costs and confirm what the lender will and will not finance before you sign anything.
Alternatives When a Specific Car Cannot Be Financed
Sometimes the car you want simply cannot be financed. The mileage is too high, the age exceeds the lender's cutoff, or the LTV is too far out of range. When that happens, you have several options. The first is to find a different vehicle that meets the lender's criteria. That might mean choosing a car with slightly lower mileage or a newer model year, even if it costs a bit more. The second is to save a larger down payment so you can reduce the loan amount and bring the LTV into an acceptable range.
Another option is to work with a connection service that specializes in matching borrowers with lenders who are comfortable with high-mileage vehicles and bad credit. StartAutoLoan.com is an independent online platform that connects consumers with a network of participating lenders and dealers. Instead of applying to multiple lenders one by one and risking damage to your credit score from repeated hard inquiries, you can submit one request and get matched with financing options that fit your situation. The service is free to use, and there is no obligation to accept any offer. You can explore auto loan connection options to see how this approach works in practice.
If you cannot find financing for a high-mileage vehicle, consider whether you can wait and save more money. A larger down payment improves your chances of approval and reduces your monthly payment. You might also consider buying a cheaper car with cash and avoiding financing altogether, at least until your credit score improves. Finally, if you have a vehicle that is already paid off or has significant equity, you might use it as a trade-in to reduce the amount you need to finance on the next vehicle.
It is also worth checking whether your credit score can be improved quickly. Paying down credit card balances, disputing errors on your credit report, and avoiding new credit applications can raise your score by 20 to 50 points in a few months. That improvement might move you from a subprime tier to a near-prime tier, which could open up better terms and higher mileage limits. The effort is worth it if you have the time to wait.
Steps to Improve Your Approval Odds
If you are determined to finance a high-mileage vehicle with bad credit, there are concrete steps you can take to improve your chances. Start by gathering your documents: proof of income, proof of residence, a valid driver's license, and references. Lenders want to see stability, so if you have been at your job for at least a year and at your address for at least six months, highlight that in your application. A steady income and a stable living situation go a long way toward offsetting a low credit score.
Next, save as much as you can for a down payment. Even an extra $500 or $1,000 can make a difference in the lender's decision. If you have a trade-in, get it appraised and use that value toward the down payment. Be honest about your credit history and your income. Lenders appreciate transparency, and hiding information can lead to a denial or a rescinded offer. If you have had a bankruptcy, bring documentation showing that it is discharged and that you have rebuilt some credit since then.
Finally, be realistic about what you can afford. A high-mileage vehicle with bad credit will come with a higher interest rate, and you do not want to take on a payment that strains your budget. Use a loan calculator to estimate your monthly payment, and factor in insurance, fuel, and maintenance. A car that costs $300 per month to finance but requires $200 per month in repairs is not a good deal. Choose a vehicle that fits your budget and your lifestyle, and work with a lender or connection service that understands your situation.
Financing a high-mileage car with bad credit is challenging, but it is not impossible. By understanding lender cutoffs, preparing a larger down payment, insisting on a proper inspection, and knowing your alternatives, you can navigate the process with confidence. The key is to be patient, do your research, and work with partners who specialize in helping borrowers like you find a path to approval.