Auto Loan Escrow Account Explained: How It Protects You
Auto loan escrow account explained: a neutral third party holds funds until the title is clear, protecting both buyer and lender from fraud and surprise liens.
By Olivia Ramirez
You are sitting at the dealership finance desk, or maybe you are finalizing a private seller deal, and the term "escrow" suddenly enters the conversation. The finance manager mentions it casually, the seller nods, and you are left wondering whether this is a standard step or a warning sign. That uncertainty is common, and it can cost you money if you do not understand what an escrow account actually does in an auto loan transaction. This auto loan escrow account explained guide breaks down the concept in plain language, shows you when escrow is required, how it interacts with your financing and title transfer, and which red flags should make you walk away.
What an Auto Loan Escrow Account Actually Is
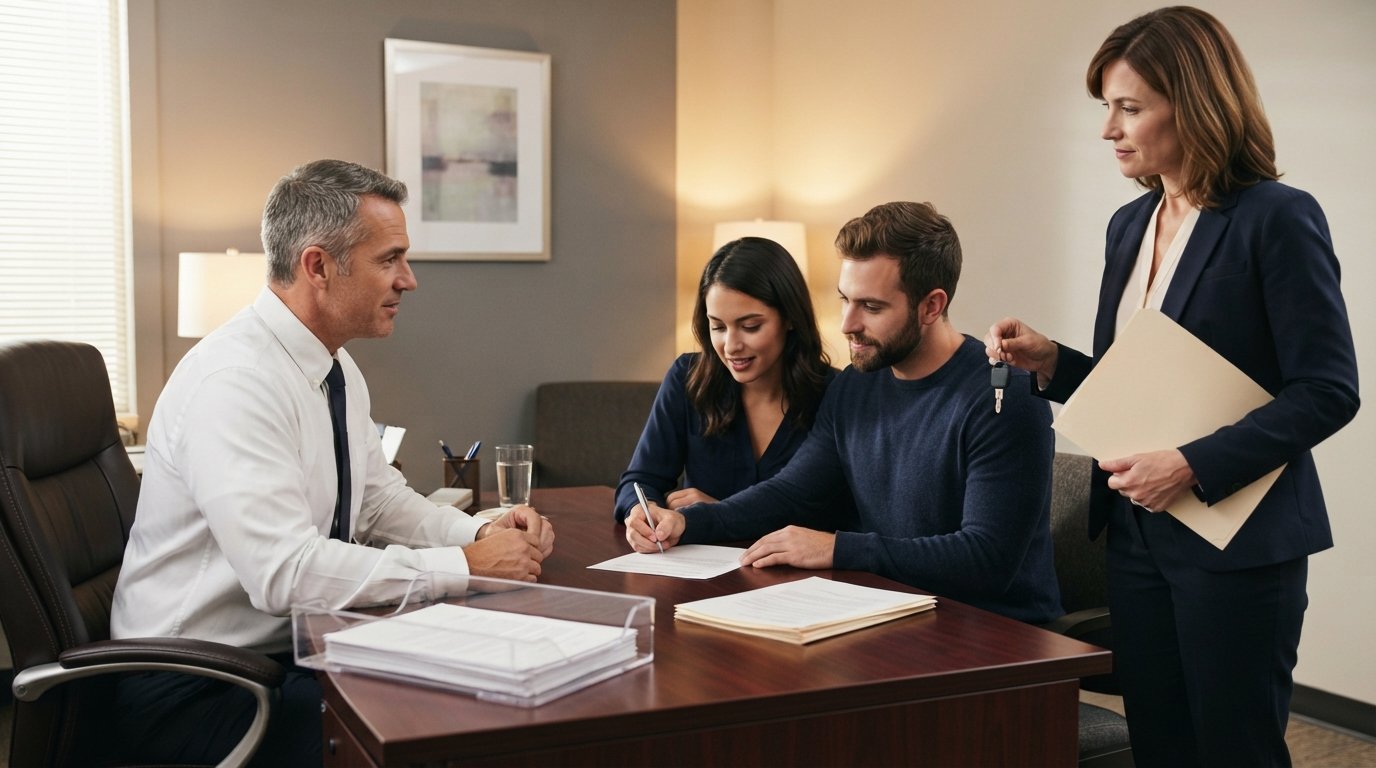
An escrow account is a neutral, third-party holding account managed by an escrow agent, which is often a title company, an attorney, or a specialized escrow service. In a vehicle purchase, the buyer deposits funds into this account, and the agent holds them until specific conditions are met. Those conditions typically include the seller delivering a clear title, the buyer securing final loan approval, and both parties signing the required paperwork. Once every condition is satisfied, the agent releases the money to the seller and the title to the buyer.
The key idea is trust. Neither party has to hand over cash or a title first. The escrow agent acts as a referee who verifies that each side has done what they promised before any value changes hands. For a financed purchase, the lender may also be involved because the loan funds often flow through the escrow agent to the seller, and the title is transferred with the lender listed as lienholder.
It helps to separate two things that sound similar but serve different purposes. An escrow account in a vehicle purchase is a temporary holding account for a single transaction. A lender escrow account, sometimes called an impound account, is an ongoing account tied to your monthly payment that covers property taxes and insurance. The second type is common with mortgages, not auto loans. When someone says "auto loan escrow account explained," they almost always mean the temporary transaction account, so keep that distinction in mind as you read.
When a Lender or Seller Might Require Escrow
Escrow is not mandatory in every car deal. Many dealership purchases close without it because the dealer handles title work in-house and the lender wires funds directly. However, certain situations make escrow more likely, and understanding them helps you anticipate the process.
The most common scenario is a private party sale with financing. The seller does not know you, and you do not know the seller. The seller wants assurance that your check or loan funds are real, and you want assurance that the title is clean and will be transferred. An escrow agent solves both problems at once. Another common trigger is an out-of-state purchase, where the buyer and seller are in different states and cannot easily meet in person. Escrow protects both sides across the distance.
Lenders may also require escrow when the loan amount is large, when the vehicle is being shipped, or when the title has a lien that must be paid off before the transfer. In those cases, the escrow agent may pay the existing lienholder directly, then send the remaining balance to the seller and the clean title to the buyer. Here are the situations where escrow is most likely to appear:
- Private party sales where the buyer is using a loan and the seller wants verified funds before releasing the title.
- Out-of-state or long-distance purchases where the vehicle and title must be shipped or mailed.
- Deals where the seller still owes money on the car and the existing lien must be cleared first.
- High-value vehicles or classic cars where both parties want extra protection.
- Transactions involving a power of attorney or an absent seller.
If you are working with a lender through a connection service, ask whether escrow is part of the process before you sign anything. Knowing this upfront prevents surprises at closing and helps you budget for any escrow fees, which are usually split between buyer and seller or paid by the buyer depending on the agreement.
How Escrow Interacts With Financing and Title Transfer
When you finance a car, the lender holds a lien on the title until the loan is paid off. That lien is the lender's protection, and it must be recorded correctly during the title transfer. An escrow agent helps coordinate this three-way relationship between buyer, seller, and lender. The agent collects the down payment and the lender's funds, verifies the title is clean, and ensures the new title is issued with the lender listed as lienholder.
The sequence usually follows a predictable path. First, the buyer and seller sign a purchase agreement that sets the escrow terms. Second, the buyer deposits earnest money or the full down payment into escrow. Third, the lender sends loan documents and funds to the escrow agent. Fourth, the agent verifies the title, pays off any existing lien, and obtains the signed title from the seller. Fifth, the agent releases funds to the seller and forwards the title paperwork to the department of motor vehicles so the buyer is recorded as the new owner with the lender as lienholder.
This process protects the lender as much as it protects you. The lender wants to be certain that its money buys a vehicle with a clean title and that its lien is properly recorded. If you are exploring financing options and want to understand how loan amounts affect your budget, our guide on a 50k auto loan payment guide walks through the numbers. For buyers who have struggled to get approved, working with a platform that connects you to lenders familiar with escrow and title procedures can make the process smoother. Services like AutoTitleLoan connect consumers with financing options, and understanding how escrow fits into that process helps you ask the right questions before you commit.
Steps to Expect in a Financed Escrow Transaction
- Sign a purchase agreement that names the escrow agent and lists the conditions for release.
- Deposit your down payment or earnest money into the escrow account.
- Complete loan paperwork so the lender can fund the escrow account.
- Wait for the agent to verify the title and clear any existing liens.
- Receive the title and vehicle once the agent confirms all conditions are met.
Each step should be documented in writing. Ask for copies of the escrow instructions, the title verification, and the release authorization. If a seller or dealer resists providing these documents, treat that as a warning sign. A legitimate escrow process is transparent by design, and the agent should be easy to contact and willing to explain each stage.
Escrow Fees, Who Pays, and What Is Normal
Escrow fees vary by state and by the agent handling the transaction. In many private sales, the fee is split evenly between buyer and seller, while in some deals the buyer pays the full amount. Typical fees range from a flat charge to a percentage of the sale price, and you should confirm the amount before you agree to the deal. The fee covers the agent's work: verifying the title, holding funds, coordinating with the lender, and handling the paperwork.
What is not normal is an escrow fee that appears out of nowhere after you have already committed, or a request to pay the fee directly to the seller rather than to the escrow agent. Legitimate fees are disclosed in the escrow instructions and paid to the agent's company, not to an individual. If the numbers do not add up or the explanation keeps changing, pause the transaction and ask for a written breakdown.
Keep in mind that escrow is a service, and like any service it should come with a clear scope. The agent should tell you what is covered, how long the process takes, and what happens if a condition is not met. If the deal falls through, the escrow instructions should explain how the funds are returned and who keeps any earnest money. Read that section carefully, because it determines what you get back if the seller fails to deliver a clean title.
Red Flags That Suggest Escrow Fraud
Escrow is supposed to add safety, but scammers have learned to use the word to create false confidence. The most common scheme involves a fake escrow agent or a fake escrow website that looks official. The seller insists on using "their" escrow company, sends you a link, and asks you to wire funds. Once the money is sent, the site disappears and the seller stops responding. To avoid this, verify the escrow agent independently: look up the company's license, call a phone number you find yourself rather than the one provided, and confirm the agent is registered in your state.
Another red flag is pressure to move fast. Legitimate escrow takes time because documents must be verified. If a seller or agent pushes you to wire money within hours, or refuses to let you speak with a supervisor, that is a warning. Also watch for requests to send funds to a personal account, to a different company name than the one on the escrow instructions, or through a payment app rather than a traceable bank transfer. Escrow funds should go to a dedicated trust account held by the escrow company, never to an individual.
Finally, be skeptical of any deal where the seller claims escrow is required but cannot explain why, or where the escrow agent is also the seller's attorney or business partner. Independence is the whole point of escrow. If the agent is not neutral, the protection is gone. Trust your instincts: if the process feels rushed, secretive, or inconsistent, stop and verify before you send a single dollar.
How Escrow Fits Into the Broader Auto Loan Process
For most buyers, escrow is one step in a longer journey that starts with understanding your budget and your credit profile. If you have bad credit, no credit history, or a past bankruptcy, the financing stage can feel like the hardest part. That is where a connection service can help. StartAutoLoan.com matches buyers with participating lenders and dealers who work with a range of credit situations, and the process is designed to be straightforward: submit your information, get matched, and discuss options with a dealer or lender. Approval can come in as little as 24 hours, and loans are available up to $50,000.
Once financing is in place, escrow may or may not be part of the closing depending on the seller and the state. If it is, you now know what to expect: a neutral agent, written instructions, verified title, and a clear release of funds. If it is not, the lender and dealer will handle title work directly. Either way, the goal is the same: make sure the money, the title, and the lien all line up correctly so you drive away with a clean ownership record.
Before you sign, ask three questions: Who is the escrow agent, what conditions must be met before funds are released, and what happens if the deal falls through? The answers should be in writing. If you are still shopping for financing, take a few minutes to review your options and get prequalified so you know your budget before you negotiate. Understanding escrow is one more tool that helps you protect yourself, and the more you know, the more confident you will be at the closing table.